Bank of England
View:
September 23, 2026
DM Rates Outlook: Long-term challenges, but selective short-term value

September 23, 2026 6:15 AM UTC
*Overweight gilts for 2027, focusing on intermediates. Large ‘policy uncertainty’ premium offers value on any less adverse Middle East scenario.
* Treasuries may offer tactical opportunity into weakness over Q4 2026-Q1 2027, with US10s projected back towards 4½% in respite. Longer term issues re
September 22, 2026
DM ex U.S.: Weathering Higher Energy Prices

September 22, 2026 1:22 PM UTC
· EZ. We expect the Eurozone economy to remain resilient in coming quarters despite the ongoing energy shock. Household consumption growth should strengthen into 2027, supported by a recovery in real wage growth and by favourable employment increases. Increased defence and infrastructur
September 17, 2026
BOE Keeps Rates Unchanged but November Meeting a Close Call
September 17, 2026 12:29 PM UTC
As expected, the BOE kept rates unchanged with the committee voting 6-3 in favour of staying at 3.75%. MPC members Green, Mann and Pill voted to increase rates by 25bp, as they did in July. Today’s monetary policy statement is essentially unchanged from the July statement, with the focus still on
BOE Keeps Rates Unchanged but November Meeting a Close Call
September 17, 2026 12:26 PM UTC
As expected, the BOE kept rates unchanged with the committee voting 6-3 in favour of staying at 3.75%. MPC members Green, Mann and Pill voted to increase rates by 25bp, as they did in July. Today’s monetary policy statement is essentially unchanged from the July statement, with the focus still on
September 16, 2026
UK CPI Higher in August But as Expected
September 16, 2026 7:20 AM UTC
Headline inflation increased to 3.1% in August from 2.9% before and in line with expectations with the largest upward contribution coming from transport and in particularly motor fuels. The figures are not a surprise given that July’s short-lived dip in petrol and diesel prices were reversed in
UK CPI Higher in August But as Expected
September 16, 2026 7:20 AM UTC
Headline inflation increased to 3.1% in August from 2.9% before and in line with expectations with the largest upward contribution coming from transport and in particularly motor fuels. The figures are not a surprise given that July’s short-lived dip in petrol and diesel prices were reversed in
September 14, 2026
UK CPI Preview: Headline Inflation to Increase on Higher Energy Costs but no Second Round Effects
September 14, 2026 9:24 AM UTC
· Inflation figures will come ahead of BoE meeting on September 17 in which the Bank is expected to keep rates on hold. Headline annual inflation rose to 2.9% in July and is forecast to increase to 3.1% in August with core also ticking up to 2.7% from 2.6% previously. The numbers are un
UK CPI Preview: Headline Inflation to Increase on Higher Energy Costs but no Second Round Effects
September 14, 2026 9:22 AM UTC
· Inflation figures will come ahead of BoE meeting on September 17 in which the Bank is expected to keep rates on hold. Headline annual inflation rose to 2.9% in July and is forecast to increase to 3.1% in August with core also ticking up to 2.7% from 2.6% previously. The numbers are un
September 11, 2026

QT: BOE Slowdown But Not BOJ/ECB Yet
September 11, 2026 11:50 AM UTC
· The BOE will likely slow the pace of QT to GBP50bln pa at the September 17 MPC meeting, but the BOJ/ECB have no current plans to slow QT. The BOJ QT at 6% of GDP is huge and pushing up JGB yields and the BOJ could slow the pace over the winter into the spring once the next 25bps pol

UK GDP Growth defies expectations in July but expected to slow ahead
September 11, 2026 7:53 AM UTC
Contrary to expectations, the UK economy grew by 0.4% in July (on a month-on-month basis) against a forecast of zero growth. Activity during the month was driven by services (0.4%), production (0.2%) and construction (0.1%). The sector breakdown shows that growth in the services sector was driven pa
September 02, 2026
BOE September Preview: No 2026 Hike
September 2, 2026 10:31 AM UTC
· BOE Bailey at Jackson hole highlighted the quite subdued 2nd round effects from the Iran war surge in energy prices, which suggests that the bulk of the MPC will likely not vote for a hike at the September 17 MPC meeting. A risk does exist of a Q4 hike, though our central view is fo
BOE September Preview: No 2026 Hike
September 2, 2026 10:30 AM UTC
· BOE Bailey at Jackson hole highlighted the quite subdued 2nd round effects from the Iran war surge in energy prices, which suggests that the bulk of the MPC will likely not vote for a hike at the September 17 MPC meeting. A risk does exist of a Q4 hike, though our central view is fo
August 31, 2026
UK External Account: The Ugly and the Good
August 31, 2026 11:02 AM UTC
· The UK has seen a ugly persistent worsening of the EU goods trade deficit since leaving the EU in 2020, but two current account trends are good. The UK is helped by a surging services surplus and also a pick-up in investment income from UK portfolios invested overseas. Nevertheless, G
August 25, 2026
UK inflation momentum, persistence and 2nd round: BoE in ‘wait and see’
August 25, 2026 8:36 AM UTC
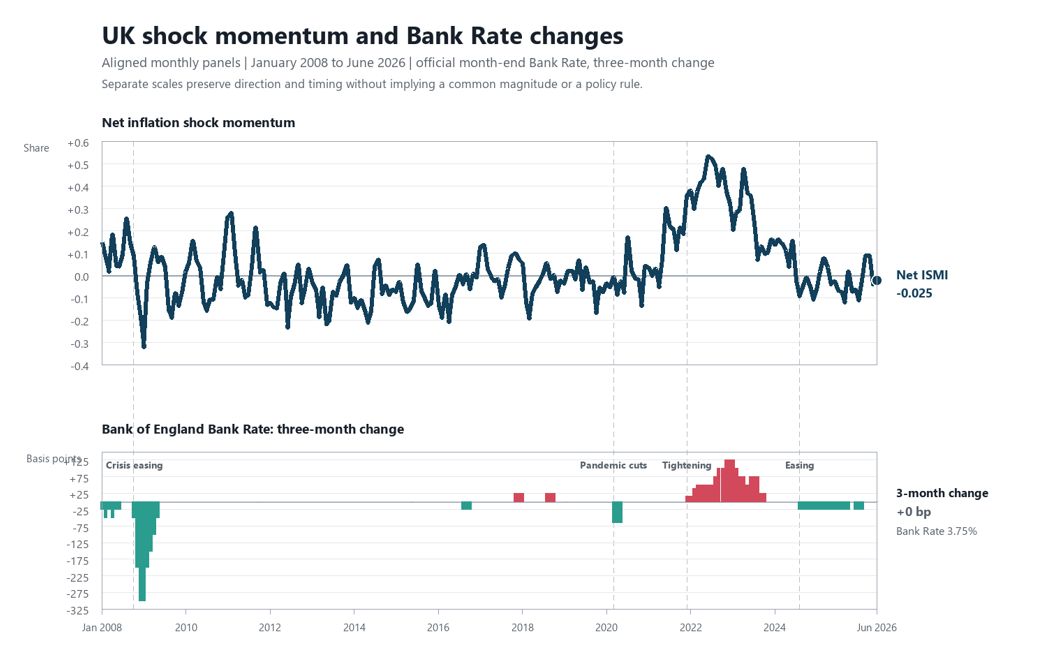
* Constructing alternative measures of inflation from the perspective of momentum, persistence, and second round expectations is useful when considering the BoE’s reaction function
* The message is partly reassuring but not fully and gives a nuanced picture
* Recent signals give time to wait and see
August 20, 2026

DM Central Banks Watching Stablecoins
August 20, 2026 10:55 AM UTC
· Overall, DM central banks have a watching brief for stablecoins and the scale of growth in the next 5 years. This is largely a USD centric issue, with stablecoins dominated by USD issuance. Central banks are watchful on whether it impacts access to low cost deposit for banks; guardi
August 19, 2026
UK CPI: Energy Prices and Weak Labour Market
August 19, 2026 6:29 AM UTC
· July UK CPI was broadly as expected and the new few months will be volatile and dependent on whether more shipping can go through the Straits of Hormuz and reduce energy prices (our baseline with a 60% probability). Underlying inflation trends in the UK are lower, as labour market d

UK CPI: Energy Prices and Weak Labour Market
August 19, 2026 6:28 AM UTC
· July UK CPI was broadly as expected and the new few months will be volatile and dependent on whether more shipping can go through the Straits of Hormuz and reduce energy prices (our baseline with a 60% probability). Underlying inflation trends in the UK are lower, as labour market d
July 30, 2026
BOE: Split Does Not Mean September Hike
July 30, 2026 12:45 PM UTC
. · Overall, the July MPC minutes and monetary policy report/press conference suggest that the MPC is not convinced of a September hike and a worsening of energy price rises and/or 2nd round effects would be required to shift the voting to a 25bps hike. While the MPC has a hawkish
BOE: Split Does Not Mean September Hike
July 30, 2026 12:44 PM UTC
· Overall, the July MPC minutes and monetary policy report/press conference suggest that the MPC is not convinced of a September hike and a worsening of energy price rises and/or 2nd round effects would be required to shift the voting to a 25bps hike. While the MPC has a hawkish bias
July 22, 2026
BOE Preview: Hawkish Noises
July 22, 2026 6:12 AM UTC
• The BOE will likely maintain a hawkish bias on July 30, but are unlikely to signal a September hike. The June CPI did not really change this picture, with the core unchanged at 2.6%. Though BOE Bailey recently noted the unstable process (in the Straits of Hormuz and for energy prices), he
BOE Preview After CPI: Hawkish Noises
July 22, 2026 6:11 AM UTC
• The BOE will likely maintain a hawkish bias on July 30, but are unlikely to signal a September hike. The June CPI did not really change this picture, with the core unchanged at 2.6%. Though BOE Bailey recently noted the unstable process (in the Straits of Hormuz and for energy prices), he
July 21, 2026
UK Fiscal Policy and the New Chancellor
July 21, 2026 6:18 AM UTC
· Apprehension will exist until the Autumn budget, despite a repeated commitment by PM Burnham to stick to the fiscal rules. Spending commitments are clearer than tax raises measures, while new Chancellor Healey may not be strong enough to curtail spending pressures. This could mean
July 16, 2026
UK GDP and BOE Question
July 16, 2026 6:23 AM UTC
· UK GDP rose 0.1% in May as expected, helped by services but with softness remaining in other areas. H2 will depend on businesses and consumers, where a BOE rate hike would dent sentiment and spending – we look for no change in policy rates in 2026 however, followed by 2027 cuts. A
June 30, 2026
UK GDP Outlook Update – Still Fragile With Surveys Negative
June 30, 2026 4:13 PM UTC
It is the relative norm for an economy to be offering disparate signals at any one juncture, if not actual conflicting ones. This is certainly the case in the UK currently, where upbeat Q1 GDP data of 0.6% q/q have been, confirmed and notably by a perkier consumer. Such shots of real growth ar
June 23, 2026
DM Rates Outlook: Tightening or Easing?
June 23, 2026 8:15 AM UTC
· With the U.S./Iran interim agreement likely to hold and energy prices softening, our projected consumer slowdown will likely tilt the Fed not to hike in H2 2026 and to actually ease by 50bps in 2027, with 25bps moves in both Q2 and Q3. With 2yr yields consistent with a hike, the tra
DM ex U.S. EZ Outlook (Japan and Western Europe): Navigating the Post Iran War Period?
June 23, 2026 7:43 AM UTC
· We have revised 2026 Japan GDP only slightly lower to 0.8% as wage growth is solidly above 3%, which will support consumption for the rest of 2026/27. The extension of energy stimulus will cap headline inflation for Q2/Q3 2026. For the BOJ, despite hawkish forward guidance, the 1% r
June 18, 2026
BOE: Gang of 6 and Steady 2026 Rates
June 18, 2026 11:27 AM UTC
Though Megan Greene joined Huw Pill in calling for a one off 25bps risk management hike, 6 MPC members feel that disinflation is showing through and a soft economy and labor market warrants waiting to see energy prices and potential 2nd round effects. This gang of 6 also feels that markets have ti
June 17, 2026
UK CPI Review: Inflation Peaking?
June 17, 2026 7:40 AM UTC
What have been energy induced price rises are starting to ease and may do so further In June before the OFGEM induced price rise hits July numbers. But a less worrying picture emerges in the latest (ie May) CPI and even PPI data. Indeed, once again, actual CPI have offered a more benign picture
June 12, 2026
UK GDP Review: GDP Upside Surprises Persist?
June 12, 2026 6:56 AM UTC
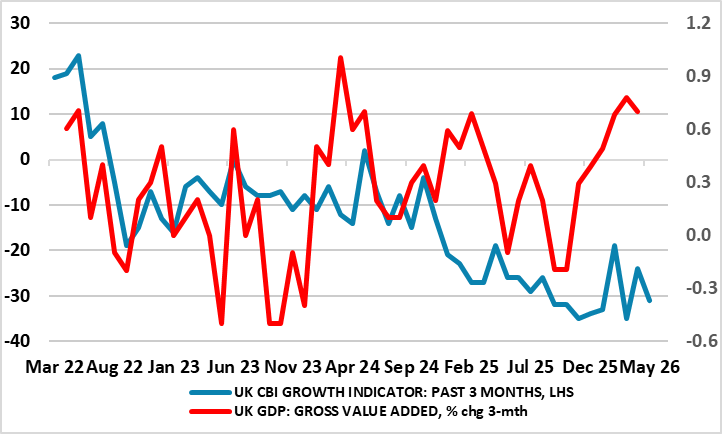
Perhaps it is a supreme irony that just as business surveys suggest clear weakness, if not fresh contraction, the actual real economy has surprised on the upside, even now into the second month after the Middle East conflict started. Indeed, and in perspective, official GDP data suggest that since
June 11, 2026
BoE Preview (Jun 18): Splits to Widen, But Stable Policy Outlook Intact
June 11, 2026 10:26 AM UTC
Not only this month, but we see the BoE being on hold for the rest of the year with rate cuts then resuming through 2027. Although markets are pricing just over two hikes from the current 3.75% with a 50%-plus probability of the first being delivered at the July 30 MPC meeting, our view is hardly
June 09, 2026
UK CPI Preview (Jun 17): Inflation Peaking?
June 9, 2026 9:37 AM UTC
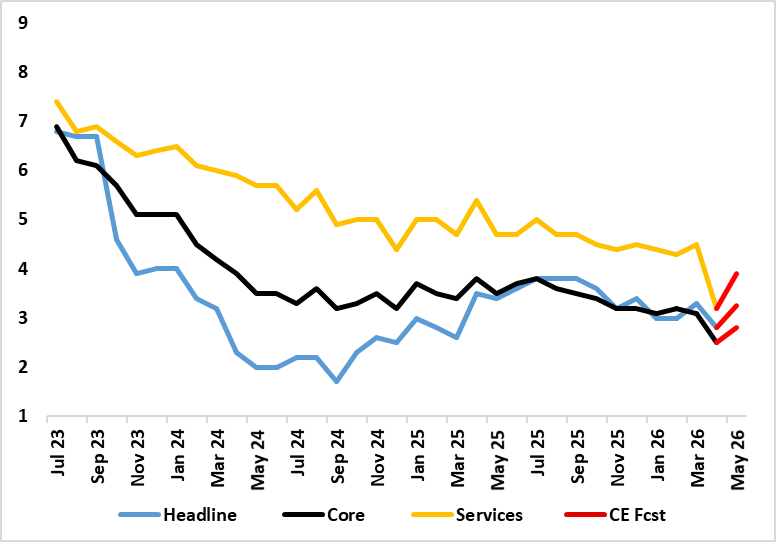
What have been energy induced price rises are now very evident, even more so in some aspects of the latest PPI data. Regardless, actual CPI have offered a more benign picture both in terms fo headline and underlying trends. Indeed, having seen headline CPI jump to 3.3% in March and where service
June 04, 2026
UK GDP Preview (Jun 12): GDP Upside Surprises To Reverse?
June 4, 2026 9:49 AM UTC
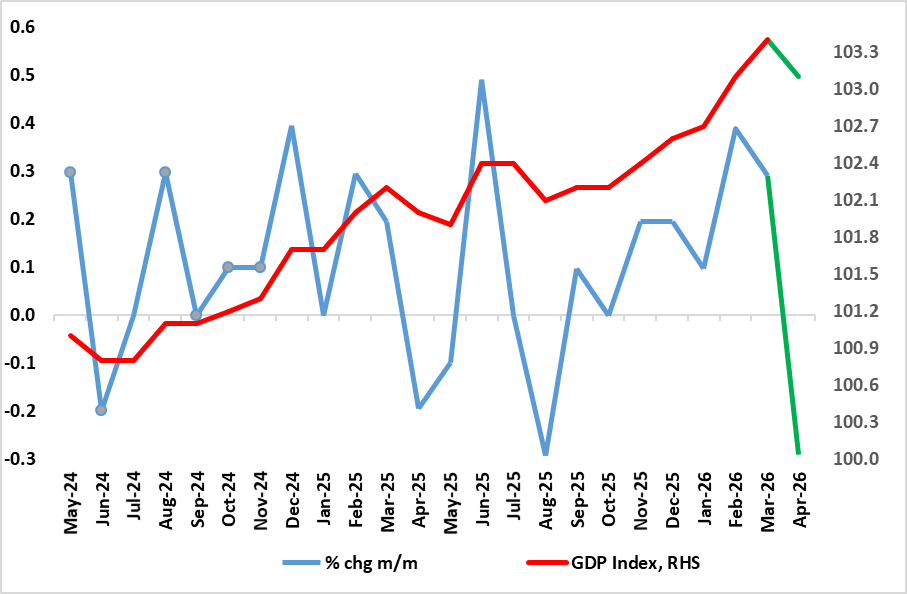
Perhaps it is a supreme irony that just as business surveys suggest clear weakness, if not fresh contraction, the actual real economy has surprised on the upside, even in the first month after the Middle East conflict. Indeed, and in perspective, official GDP data suggest that since Labour took of
May 20, 2026
UK CPI Review: Inflation Falls Broadly But A Calm Before the Storm?
May 20, 2026 6:42 AM UTC
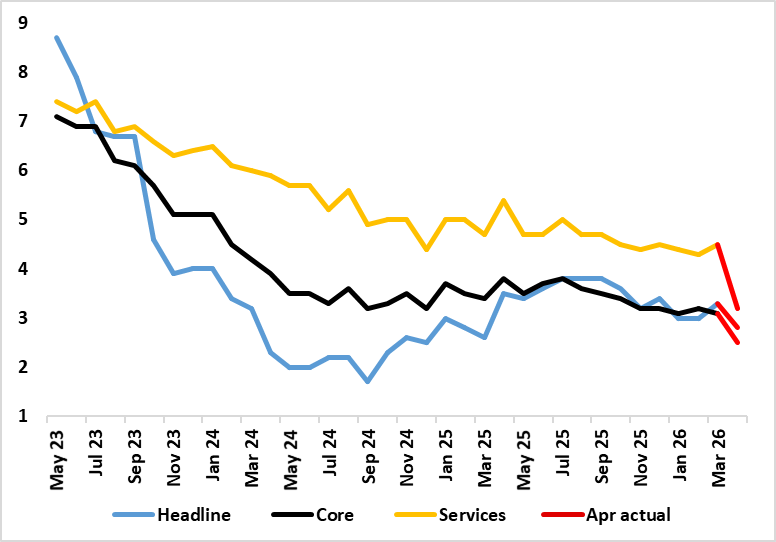
What are energy induced price rises are now very evident, even more so in the latest PPI data very much contrasting with the more benign picture in April’s more closely watched CPI figures. Thus, having seen headline CPI jump to 3.3% in March and where services rose to 4.5% on the back if what may
May 19, 2026
UK Labor Market: Core Wage Pressures hit New Cycle -Low as Jobs Growth into Sharp Reverse
May 19, 2026 6:56 AM UTC
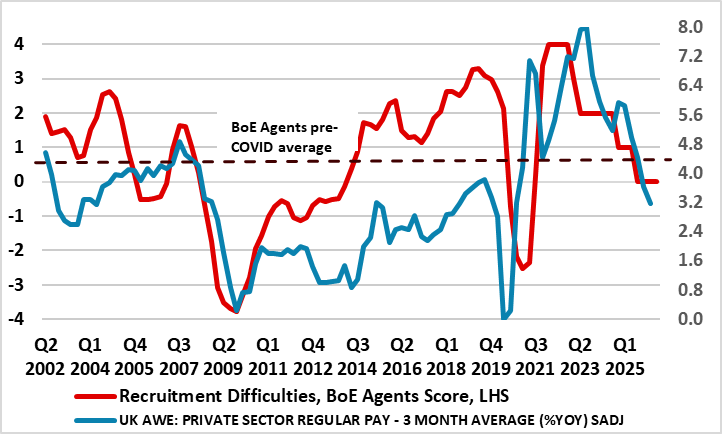
Even more clearly, there are further signs that the labor market is haemorrhaging jobs both clearly and broadly with fresh falls in the more authoritative measure of jobs covering payrolls. Indeed, private sector payrolls are still falling, down over 0.8 ppt in y/y terms with the m/m drop the larg
May 14, 2026
UK Politics – A Laboured Labour Election Ahead?
May 14, 2026 12:55 PM UTC
It is somewhat ironic that as markets (particularly gilts) fret over a shift to the left causing less fiscal prudency, it is actually the centre of the Labour party that is fermenting the most uncertainty. (Now Ex) Secretary Streeting has yet to make a formal bid to challenge PM Starmer for the le
UK GDP Review: GDP Upside Surprises Continue, Correction Due or Fresh Trend?
May 14, 2026 6:59 AM UTC
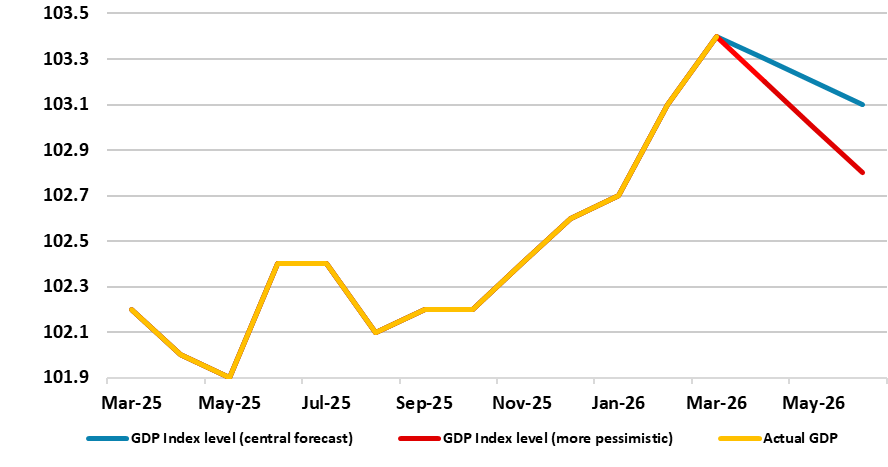
Perhaps it is a supreme irony that just as the Labour government tears itself apart after disastrous election results last week, the actual real economy continues to surprise on the upside. Notably, since taking office in July 2024, the economy has grown a cumulative 2%-plus, ie over 1% per year.?
May 12, 2026
UK CPI Preview (May 20): Inflation Sedate For Now But Wages Still on the Wane?
May 12, 2026 12:05 PM UTC
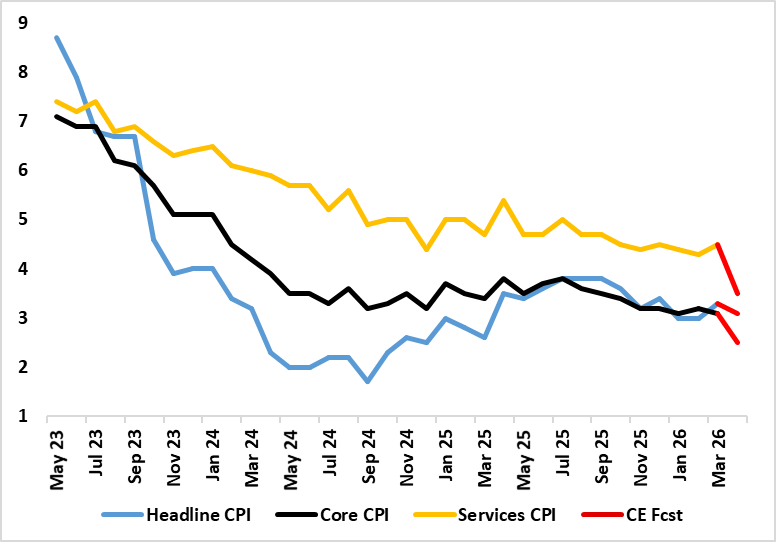
What are energy induced price rises are now very evident, most notably in PPI data as well as the more closely watched CPI figures. Thus after a stable 3.0% (a 10-mth low) February’s headline – matching the consensus, headline CPI jumped to 3.3% in March. Services, however, rose from 4.3% a fo
May 05, 2026
UK GDP Preview (May 14): March GDP Drop Expected, Correction or Fresh Trend?
May 5, 2026 10:16 AM UTC
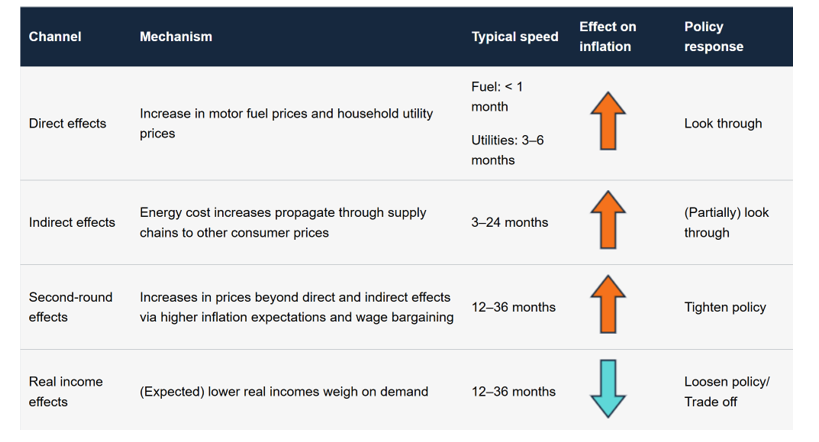
Before the outbreak of the Iran War there was already a split within the MPC about the policy outlook and that such divisions may have been accentuated by the much stronger than expected February GDP update which showed a m/m rise of 0.5%, the strongest in 14 months. This is likely to have been ab
April 30, 2026
BoE Review: MPC Playing Its Cards Safely (For Now)?
April 30, 2026 12:29 PM UTC
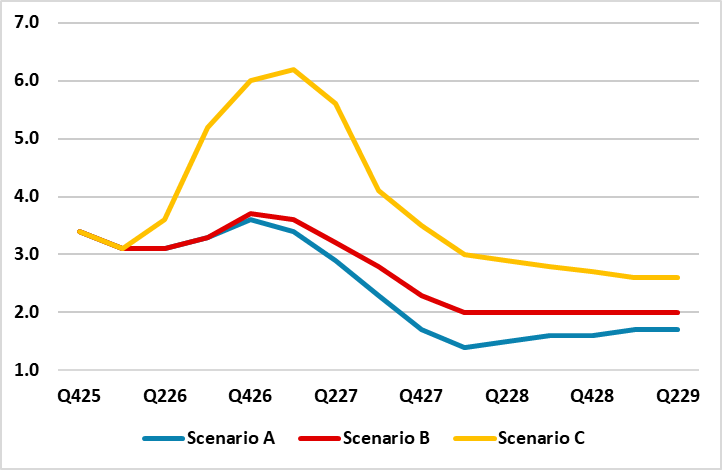
Very clearly, the BoE kept rates on hold with the MPC last month and the same decision was both expected and delivered this time around but with only token fresh dissent, with Chief Economist Pill wanting an immediate hike from the current 3.75%. But splits were more evident in the individual MPC
April 29, 2026
UK Political Risk – Bad Things Come in Threes?
April 29, 2026 12:12 PM UTC
The biggest set of elections since the 2024 general election takes place on 7 May in the UK. Already, UK markets are fretting about the possible outcome, in particular that serious electoral damage to the Labour Party currently running the government could make it swing more to left and dilute fis
April 24, 2026
BoE Preview (Apr 30) Divided Again But Unmoved (For Now)?
April 24, 2026 9:34 AM UTC
Very clearly, the BoE kept rates on hold with the MPC unanimous last month and the same decision is expected this time around but with probable fresh dissent, with up to 2-3 members opting for an immediate hike. These splits will be even more evident in the individual MPC member statements (as exp
April 22, 2026
UK CPI Review: Inflation Being Fuelled But Wages Still on the Wane?
April 22, 2026 6:35 AM UTC
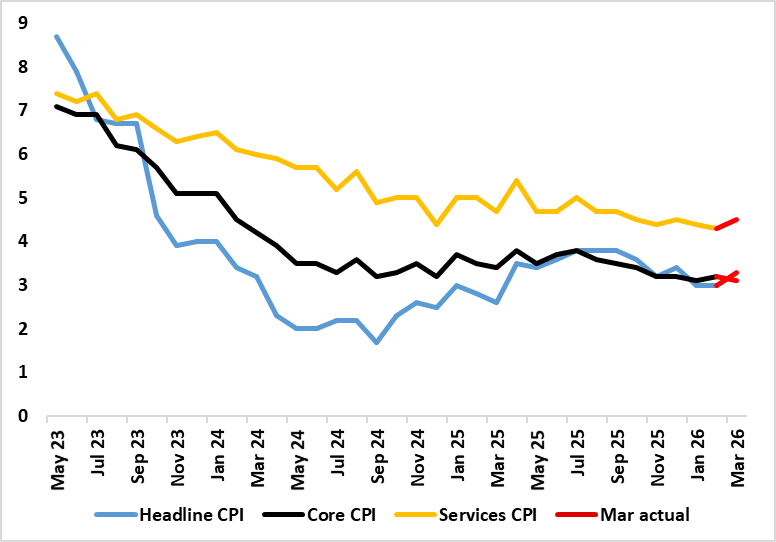
What are energy induced price rises are now very evident, most notably in PPI data as well as the more closely watched CPI figures. Thus after a stable 3.0% (a 10-mth low) February’s headline – matching the consensus, headline CPI jumped to 3.3% in March. Services, however, rose from 4.3% a fo
April 21, 2026
UK Labor Market: Lower Jobless Rates Misleading, as Wage Pressures hit New Cycle -Low
April 21, 2026 6:54 AM UTC
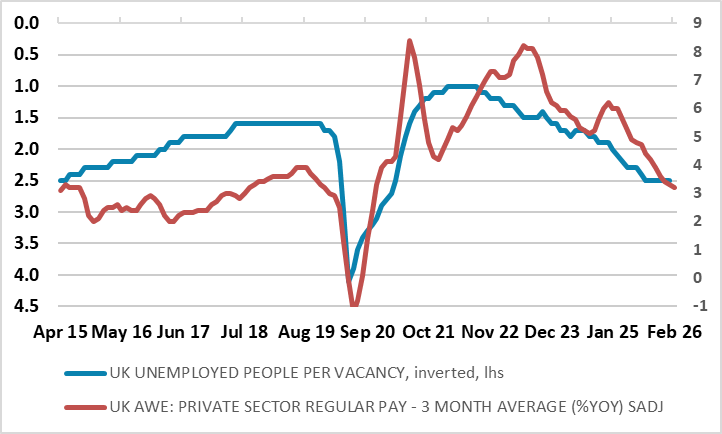
There are further signs that the labor market is haemorrhaging jobs both clearly and broadly with fresh falls in the more authoritative measure of jobs covering payrolls. Indeed, private sector payrolls are still falling, down over 0.5 ppt in y/y terms. Admittedly, headlines may be formed around
April 16, 2026
UK GDP Review (Apr 16): Fresh But Fleeting Momentum Before the War
April 16, 2026 7:10 AM UTC
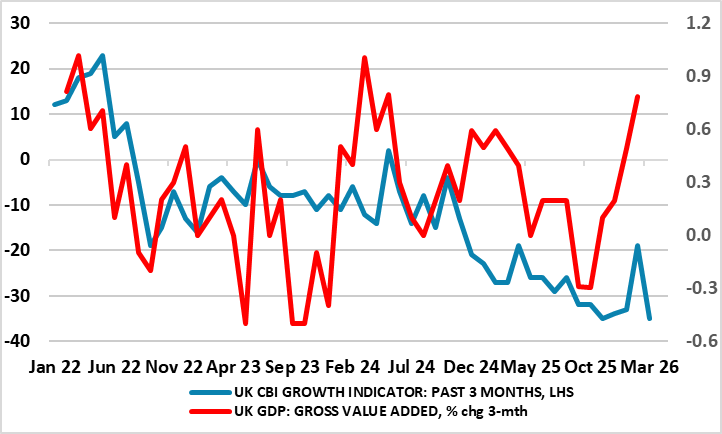
Without the outbreak of the Iran War there was already a split within the MPC about the policy outlook and that such divisions may have been accentuated by this latest GDP update which showed a very much above consensus m/m rise of 0.5%, the strongest in 14 months. But of course, the conflict has ch
April 13, 2026
UK CPI Preview (Apr 22): Inflation Being Fuelled But Watch Financial Conditions?
April 13, 2026 2:39 PM UTC
The stormy weather inflation wise is now very evident, most notably in UK fuel prices surging. Thus after a stable 3.0% (a 10-mth low) February’s headline – matching both consensus and BoE projections we see it jumping to 3.5% in March. Services, however, may stay at 4.3% which was a four-year
April 09, 2026
UK GDP Preview (Apr 16): Moving Sideways Even Before Conflict?
April 9, 2026 8:01 AM UTC
Fresh downside surprises were the story from the January GDP numbers and we expect a similarly muted outcome for the looming February numbers. There were expectations that the economy would enjoy a further successive rise in January, thereby providing the best three-month showing in two years were
March 25, 2026
UK CPI Review: Goodbye to the Good Old Days?
March 25, 2026 7:33 AM UTC
After January’s clear fall, even in the core rate, where the headline CPI rate fell from December’s 3.4% to 3.0% (a 10-mth low) it stayed there in February’s numbers – matching both consensus and BoE projections. Services fell 0.1 ppt to 4.3% which was a four-year low (Figure 1) but the co
March 24, 2026
DM Rates Outlook: Mixed Policy Rate and Yield Paths
March 24, 2026 8:46 AM UTC
· The multi quarter outlook for DM rates depends on the length of the Iran war Our baseline is that it will be a 4-8 week war (here) and a 3-4 quarter retracement of oil prices back to pre-war levels – longer from Europe and Asian gas prices. We forecast WTI down to USD80-85 by June
Western Europe Outlook: Economies Slip on Oil
March 24, 2026 8:00 AM UTC
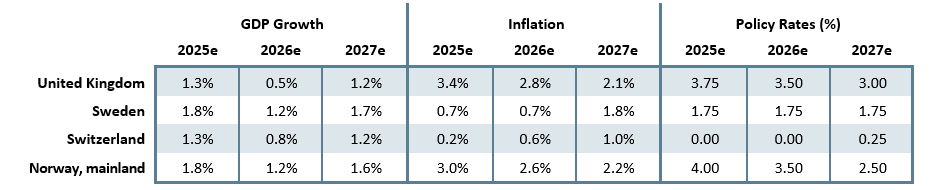
· In the UK, even without the Middle East impact we were suggesting a sub-consensus 2026 GDP picture which now has even greater downside risks attached. Our baseline is for 4-8 week war and a reversal of oil prices over 3 quarters. The BoE has a symmetric stance between 2nd round effe
March 19, 2026
BoE Review: A Fragile MPC Truce?
March 19, 2026 12:59 PM UTC
Very clearly, the BoE kept rates on hold with no dissents as it understandably waits for more information about the length, breadth and repercussions of the Iran war. The individual MPC member statements (as expected) showed diverging views as to the extent and reaction of what are now unfolding r