View:
FX Daily Strategy: Asia, Oct 22

October 21, 2026 2:35 PM UTC
Positioning and oversold conditions obstructing euro follow through traction; downside focus switching to options protection
AUD lifted by short-covering and momentum swing towards a Nov hike pricing
Focus remains news driven rather than calendar-centric

UK Q3 GDP Preview - Strong Growth Expected in Q3 But Thereafter?
November 9, 2026 7:09 PM UTC
Despite higher energy costs, growing uncertainty and tighter financial conditions, the UK economy likely continued to grow rapidly in Q3. We expect quarter on quarter growth to have increased by 0.7%, in line with estimates produced by the BoE in last week’s Monetary Policy Report (see Figure 1).
UK Q3 GDP Preview - Strong Growth Expected in Q3 But Thereafter?
November 9, 2026 7:09 PM UTC
Despite higher energy costs, growing uncertainty and tighter financial conditions, the UK economy likely continued to grow rapidly in Q3. We expect quarter on quarter growth to have increased by 0.7%, in line with estimates produced by the BoE in last week’s Monetary Policy Report (see Figure 1).
FX Daily Strategy: Asia, Nov 10
November 9, 2026 4:15 PM UTC
Risk attempts to bounce on oil and tech lift, but outlook still unclear
Back from the noise, EUR/USD not far from 1.12 pivot, and DXY stuck in a 1 figure range
Positioning does remain heavily defensive, especially on yen risk crosses
US CPI offers some normality. On-consensus results anticipated
Preview: Due November 10 - U.S. October CPI - A more moderate month
November 9, 2026 1:04 PM UTC
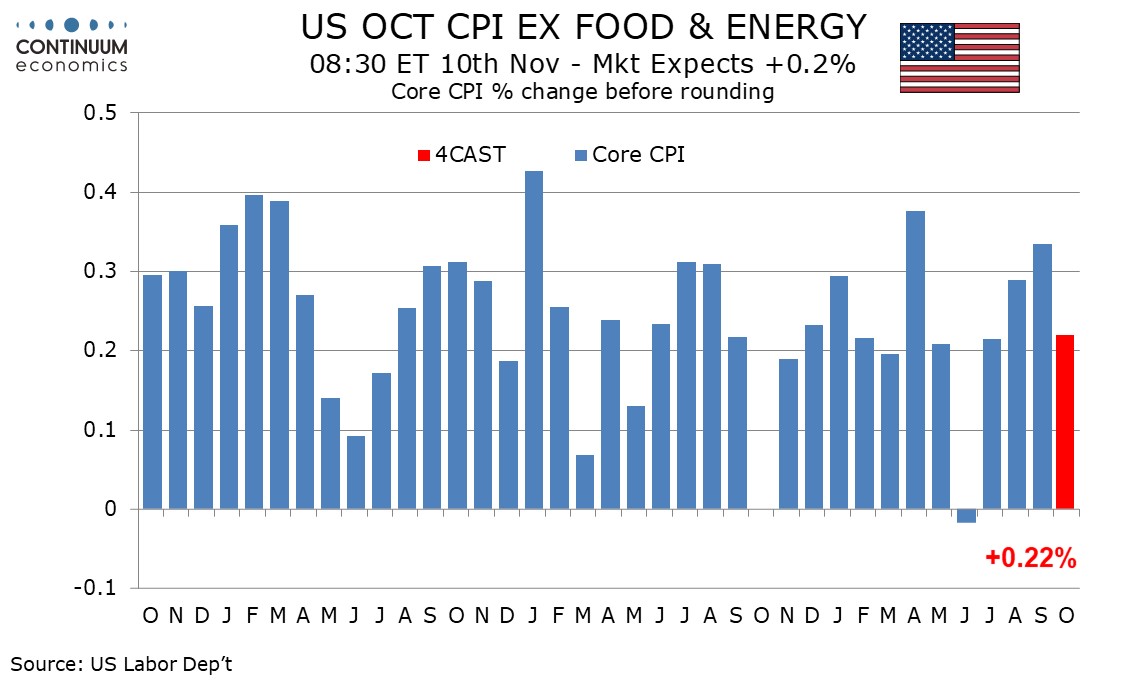
We expect more subdued CPI in October after two straight disappointing 0.3% gains in the core rate, with October’s core rate seen at 0.2%, 0.22% before rounding. Gasoline prices have seen only a marginal rise on the month, and we expect overall CPI to also rise by 0.2%, though at 0.24% before roun