View:
October 30, 2026
Eurozone Economy Remains Resilient in Q3 - Headwinds Ahead?

October 30, 2026 11:41 AM UTC
The economy expanded more than expected in Q3, rising 0.4% q/q from 0.6% before, with the Eurozone aggregate benefitting from Ireland’s large and volatile growth rate. Most of the larger member countries experienced weak quarter on quarter growth, with Germany’s economy increasing 0.2%, Italy’
October 29, 2026
EZ Q3 GDP to Show Ongoing Resilience
October 29, 2026 9:00 PM UTC
GDP is expected to grow 0.2% q/q in Q3 following a large quarterly gain of 0.6% in Q2, a figure that had been boosted by Ireland’s significant expansion of 10.2% q/q - driven largely by a surge in multinational-dominated sectors, led by Information & Communication and high-value industry. Once Ire
ECB Review: ECB Stays Put But December Hike Likely

October 29, 2026 3:27 PM UTC
As expected, the ECB kept the deposit rate unchanged at 2.50% but President Lagarde’s comments in the press conference largely paved the way for a 25bp hike in December, unless it is derailed by a further deterioration in financing conditions and a sharp worsening of the growth outlook. President
U.S. Q3 GDP strong outside net exports
October 29, 2026 1:13 PM UTC
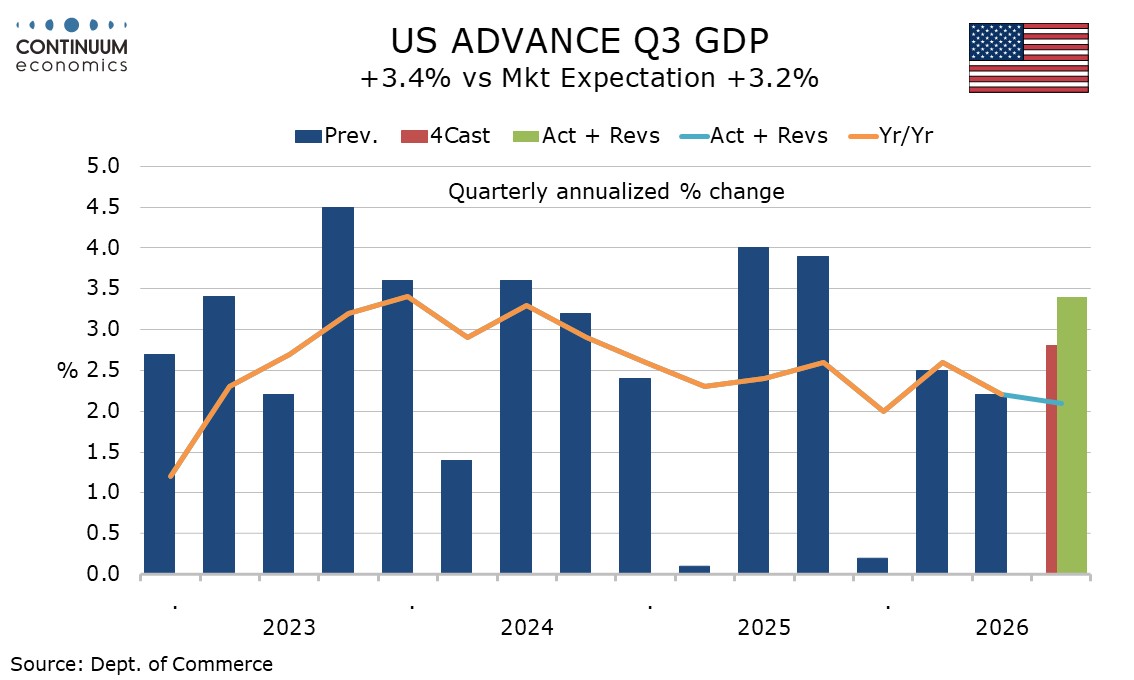
There are no major surprises in the latest US data, but it is generally healthy, with Q3 GDP slightly stronger than expected at 3.4%, with the details strong outside net exports. September personal income rose by 0.2% with spending up by 0.5%, both slightly slower than expected. Core PCE prices rose
October 28, 2026
FOMC - Pause, but no clear dovish signals
October 28, 2026 7:40 PM UTC
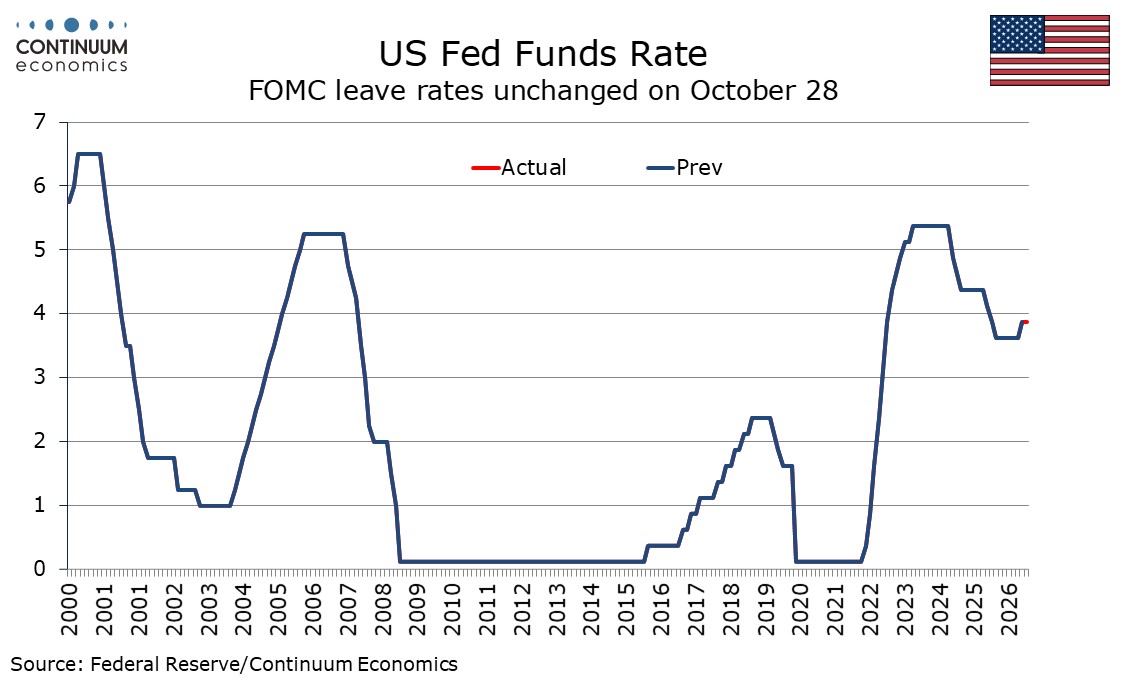
The FOMC left rates unchanged at 3.75-4.0% as expected but still appears to be on track for a December tightening. The Fed stated accumulation of more information will help the Fed determine the appropriate stance to return inflation to the 2% target. We suspect a slowing economy and stabilizing inf
ECB Preview: October Hold but Markets to Focus on Response to Widening Spreads
October 28, 2026 3:55 PM UTC
The ECB is widely expected to keep rates on hold this Thursday with financial markets instead focusing on the tone of the statement and President Lagarde’s comments in the press conference. In particular, analysts will be keen to hear whether September’s hawkish language has changed given France
Bank of Canada - A cautious tightening cycle starts
October 28, 2026 3:31 PM UTC
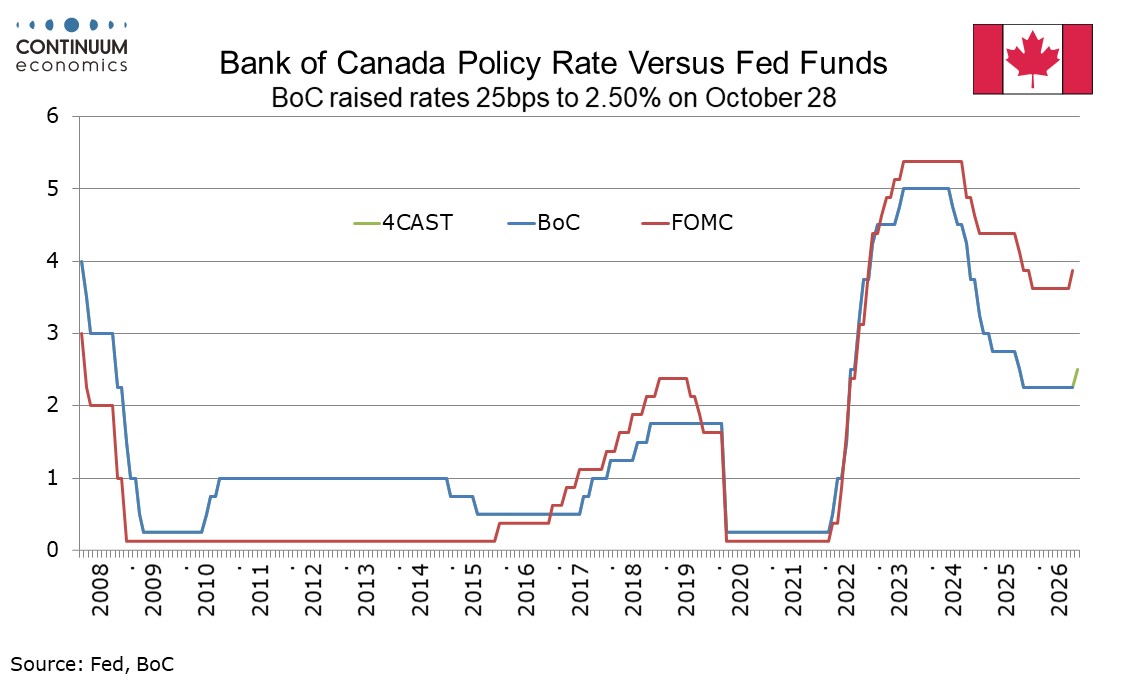
The Bank of Canada’s decision to tighten by 25bps to 2.50% was as expected by the markets with the risks of elevated oil prices the principal reason behind the move. Uncertainty means the BoC will be cautious going forward, but further rate hikes look likely, if not at consecutive meetings. We now
U.S. September Advance Goods Trade - Deficit higher on capital goods imports
October 28, 2026 12:42 PM UTC
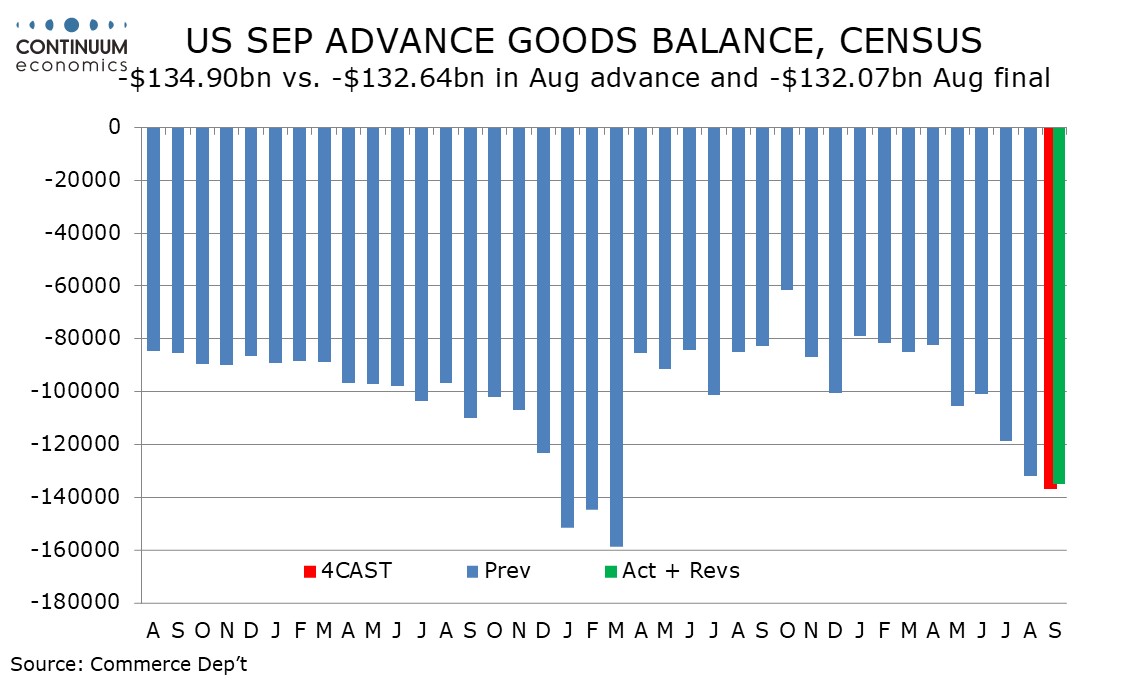
September’s advance goods trade deficit of $134.9bn from $132.1bn, continues to deteriorate, ensuring that net exports will be a significant negative in what is likely to be an otherwise strong Q3 GDP report tomorrow.
October 27, 2026
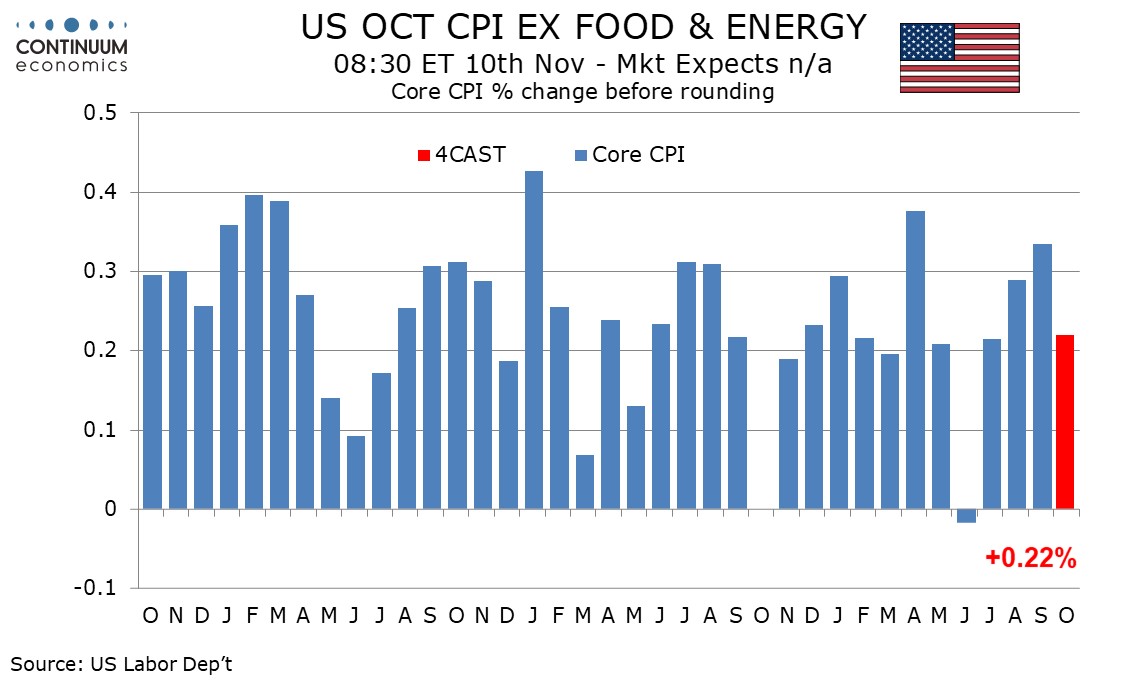
Preview: Due November 10 - U.S. October CPI - A more moderate month
October 27, 2026 6:55 PM UTC
We expect more subdued CPI in October after two straight disappointing 0.3% gains in the core rate, with October’s core rate seen at 0.2%, 0.22% before rounding. Gasoline prices have seen only a marginal rise on the month, and we expect overall CPI to also rise by 0.2%, though at 0.24% before roun
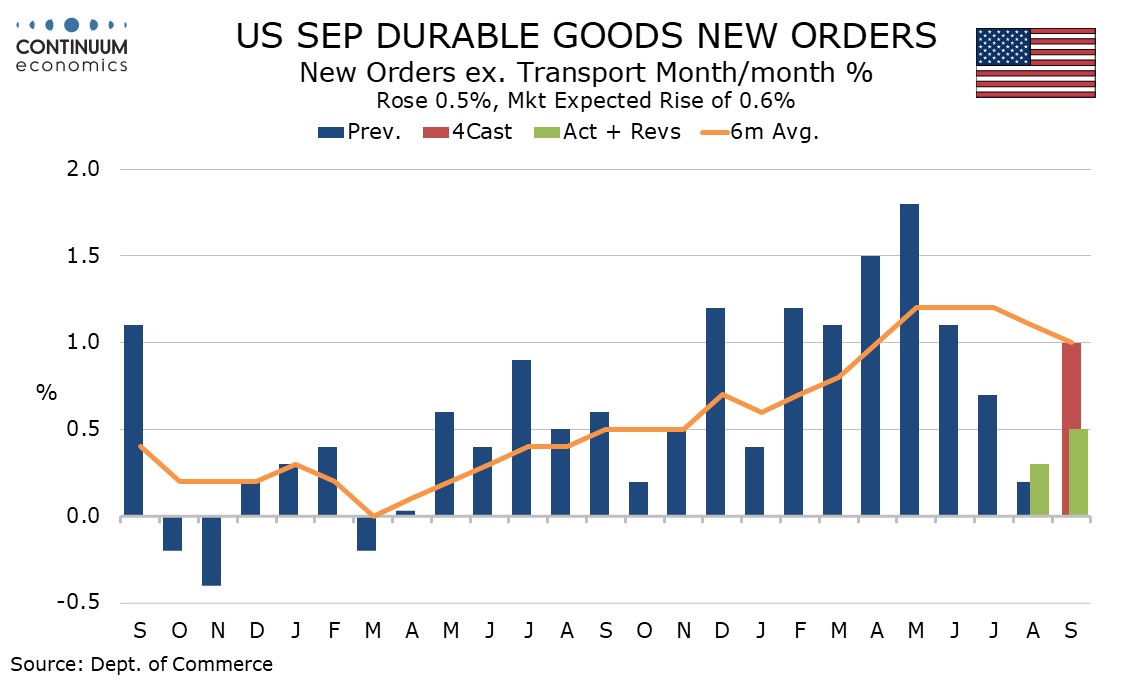
U.S. September Durable Goods Orders - Some loss of underlying momentum in Q3
October 27, 2026 12:47 PM UTC
September durable goods orders are in line with expectations, up by 1.8% overall and 0.5% ex transport. The ex transport trend remains positive but has lost some momentum in Q3 after a very strong Q2.
October 26, 2026
October 25, 2026
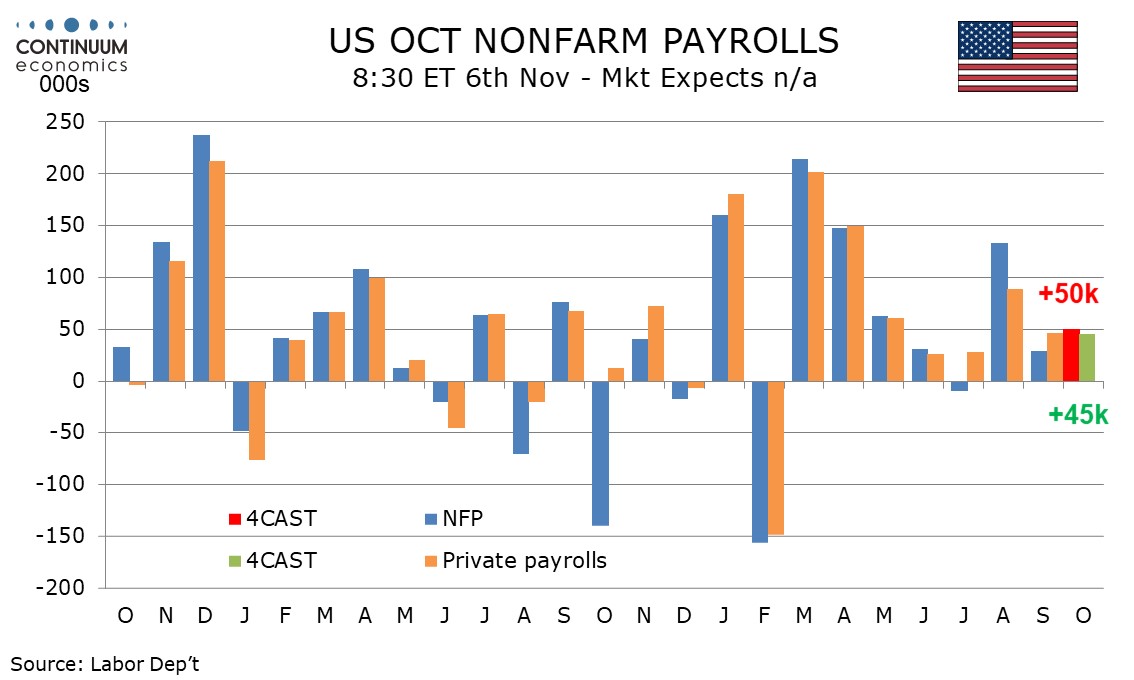
Preview: Due November 6 - U.S. October Employment (Non-Farm Payrolls) - Subdued report to hint at Q4 slowing
October 25, 2026 2:30 PM UTC
We expect October’s non-farm payroll to rise by 50k and by 45k in the private sector, in line with recent trend. We expect unemployment to remain at 4.2%, sustaining September’s increase after two months at 4.1%. We expect a modest 0.2% rise in average hourly earnings and a fall in the workweek
October 23, 2026
October 22, 2026
October 21, 2026
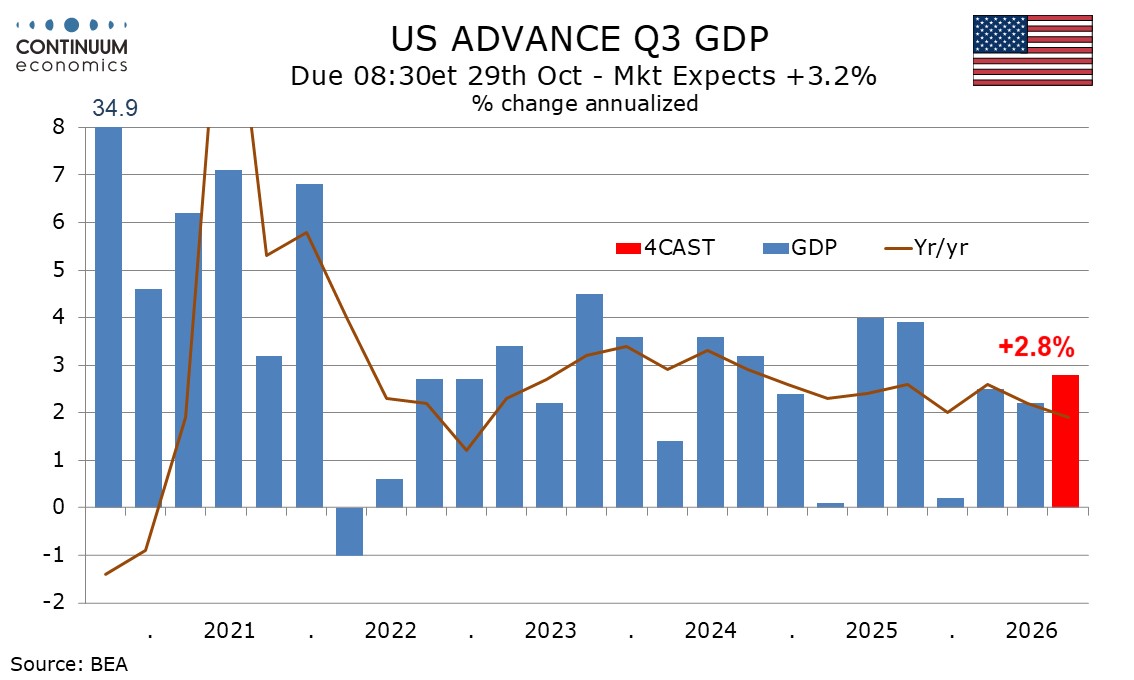
Preview: Due October 29 - U.S. Q3 GDP - Stronger growth, slower inflation
October 21, 2026 4:03 PM UTC
We expect a Q3 GDP increase of 2.8% annualized, a modest acceleration from the two preceding quarters to a 4-quarter high. We expect a 2.4% increase in core PCE prices, still above target but the slowest since a matching Q3 2024.
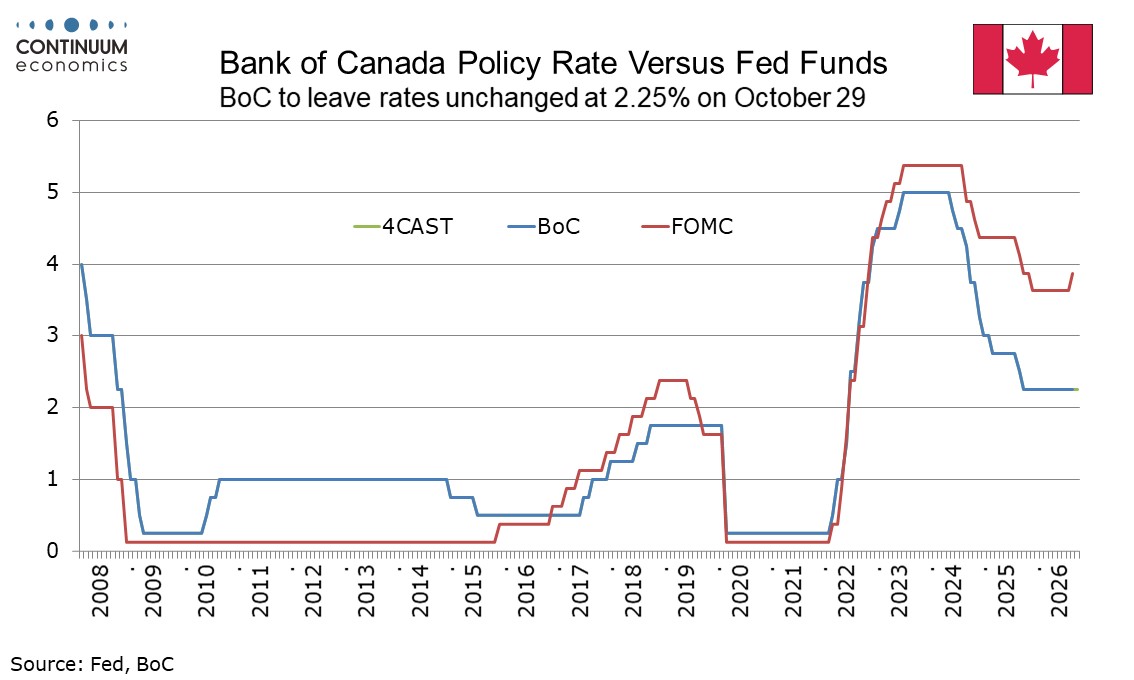
Bank of Canada Preview for October 28: Steady, December tightening not a done deal
October 21, 2026 2:04 PM UTC
The Bank of Canada meets on October 28 and recent soft employment and core inflation data suggest rates will be left unchanged at 2.25%. The BoC is still likely to express more concern about upside than downside risks, but may sound a little more balanced than was the case at the last meeting on Sep
Strains bring financial conditions into the eurozone mix
October 21, 2026 9:06 AM UTC
* French stress and ECB Lagarde comments switch focus to the tightening in financial conditions
*Past studies show material impact from significant episodes...
* ...with possible implications for core bond demand, ECB pricing and the wider appetite for risk across FX and markets.
October 20, 2026
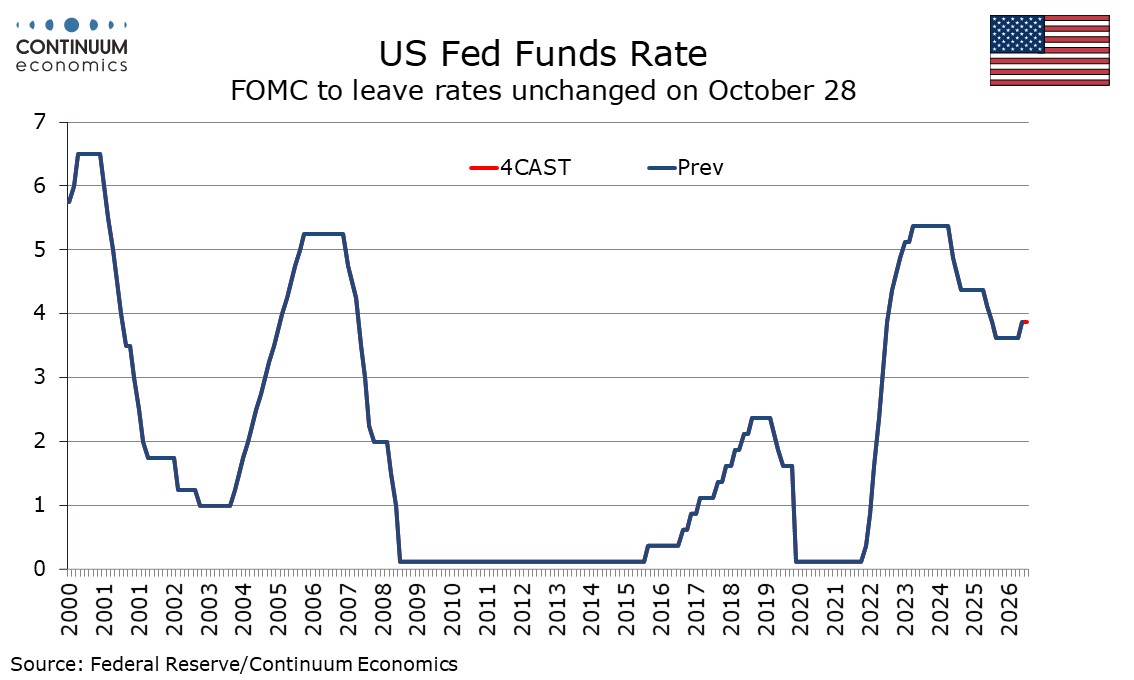
FOMC Preview for October 28: Tightening to be debated but delayed
October 20, 2026 2:58 PM UTC
The FOMC meets on October 28 and a strong case for a second straight tightening can be made and will certainly be debated at the meeting. However to appears more likely that the Fed will leave rates unchanged at 3.75-4.0%. It is likely that December’s meeting will see a tightening, but Chairman Wa
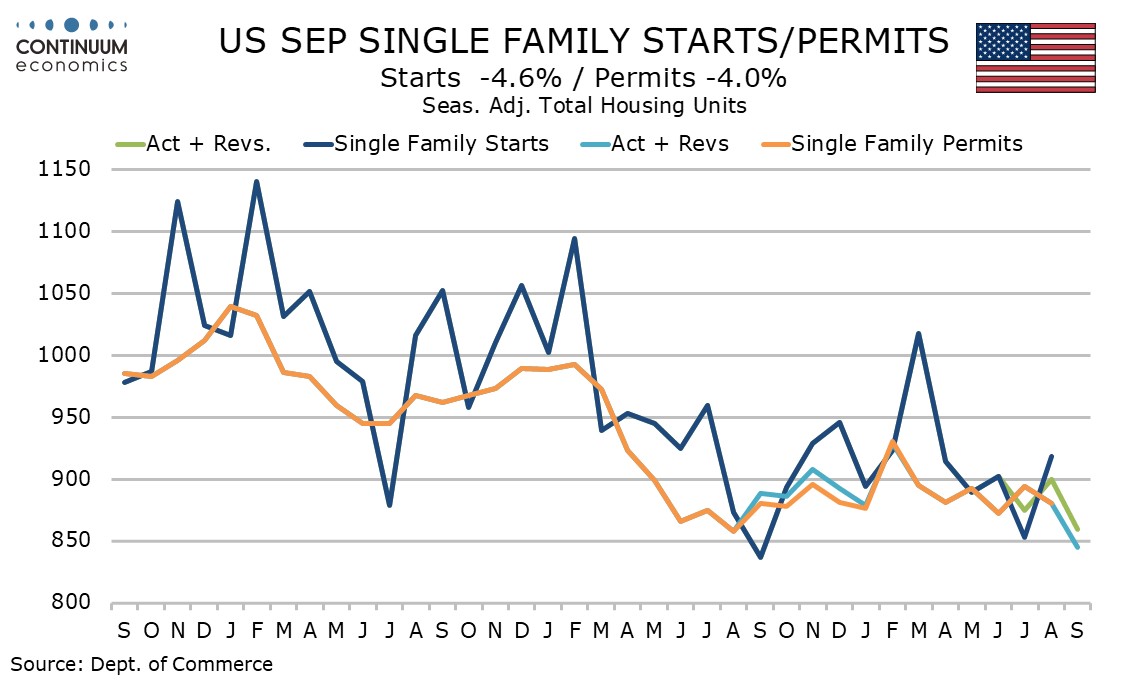
U.S. September Housing Starts and Permits - Signs of weakness building
October 20, 2026 12:50 PM UTC
September housing starts are clearly weaker than expected, -5.2% to 1221k, with both singles and multiples lower. Permits held up better, -0.2% to 1400k, but with multiples up and singles down the net message is for a slowing housing sector, restrained by rising mortgage rates.