View:
AI and The U.S. Economy
October 9, 2026 8:15 AM UTC
· The AI boom is boosting the U.S. economy through three channels (semiconductor and other product enablers for AI; the data center construction boom and wealth effects boosting consumption for rich households). If AI labs revenue growth remains fast then the boom can continue through
DM Money Supply and Private Sector Debt/GDP: Not Enough Borrowing?

October 16, 2026 9:05 AM UTC
· The surge in U.S. household wealth from the post GFC boom in equity and house prices has meant household lending has been subdued but not hitting consumption. The AI infrastructure lending boom needs to be watched in the coming years, especially with the U.S. easing capital ratios.
?
China’s Quite 2nd Tier Banking Clean Up

October 12, 2026 7:05 AM UTC
· The quite though large scale action for rural banks takeover and mergers in 2025 shows that the authorities are proactive. This is good long-term, but the transition risks rural and city commercial banks restraining credit supply. Equity capital injections to 8 large state banks is
French Bonds: Global Spillover or Fiscal Crisis?
October 5, 2026 12:36 PM UTC
Overall, the current French government bond widening could partially reverse short-term on U.S. Treasury yields becoming less worried about Fed tightening and also hopes that the 2027 French government budget plan could actually pass. Some ECB officials could also note the existence of the Transmi
Strains bring financial conditions into the eurozone mix
October 21, 2026 9:06 AM UTC
* French stress and ECB Lagarde comments switch focus to the tightening in financial conditions
*Past studies show material impact from significant episodes...
* ...with possible implications for core bond demand, ECB pricing and the wider appetite for risk across FX and markets.
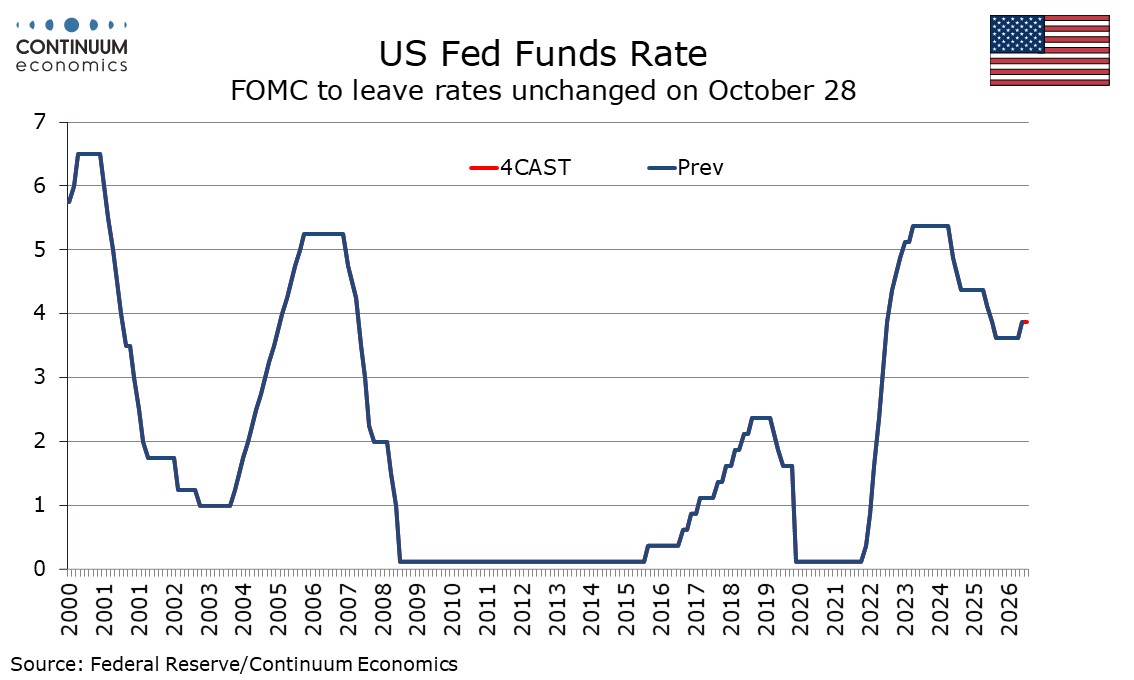
FOMC Preview for October 28: Tightening to be debated but delayed
October 20, 2026 2:58 PM UTC
The FOMC meets on October 28 and a strong case for a second straight tightening can be made and will certainly be debated at the meeting. However to appears more likely that the Fed will leave rates unchanged at 3.75-4.0%. It is likely that December’s meeting will see a tightening, but Chairman Wa
Confidence with a K
October 16, 2026 12:35 PM UTC
* Recessionary confidence, resilient spending. Political divisions are evident beneath the headline, but don't explain the macro divergence. High prices part of the story and backed up by micro data research
* Confidence with a K - exceptionally large gap in 'current conditions' sentiment for large e
ECB won’t come to France’s rescue
October 7, 2026 1:54 PM UTC
Bottom Line: France’s 10-year government bond spread to Germany widened past the 2012 highs last week prompting market speculation that the ECB could soon deploy its Transmission Protection Instrument (TPI). However, TPI is unlikely to be implemented, firstly because the ECB has firmly dismissed t
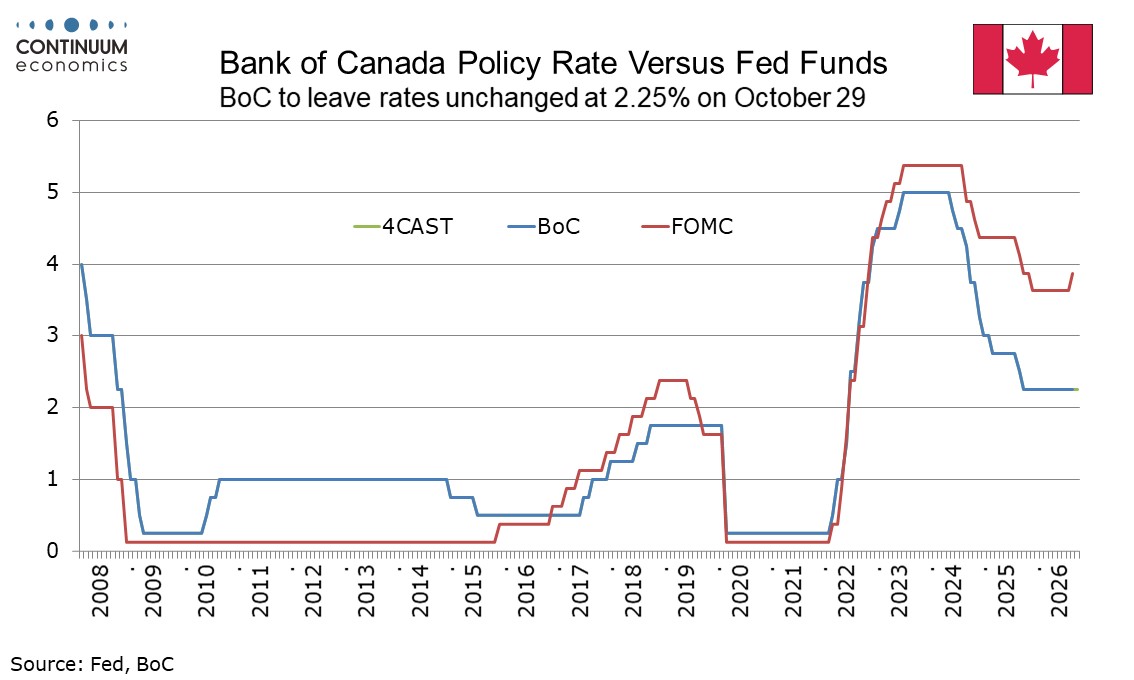
Bank of Canada Preview for October 28: Steady, December tightening not a done deal
October 21, 2026 2:04 PM UTC
The Bank of Canada meets on October 28 and recent soft employment and core inflation data suggest rates will be left unchanged at 2.25%. The BoC is still likely to express more concern about upside than downside risks, but may sound a little more balanced than was the case at the last meeting on Sep
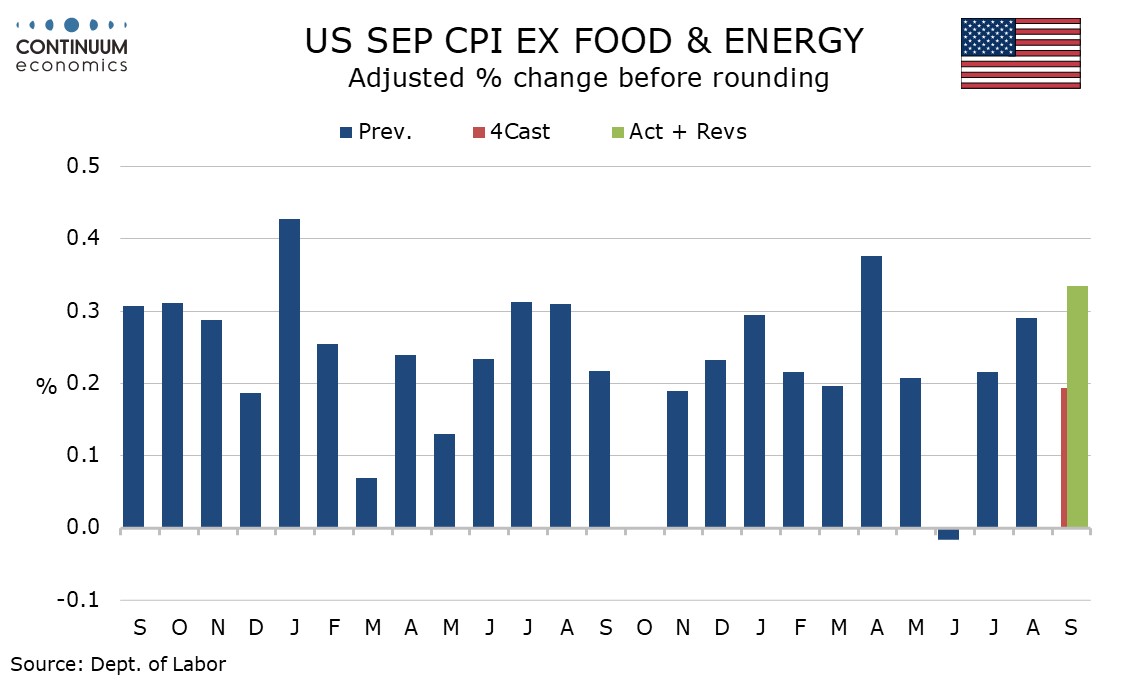
U.S. September CPI - Makes a case for tightening, will Warsh?
October 14, 2026 1:19 PM UTC
September’s core CPI is stronger than expected at 0.3% and at 0.335% before rounding a clear disappointment, with the strength broader based than August’s 0.29% when almost 0.1% came from what has proven a one-time bounce in telephone services. Overall CPI rise by 0.6% as expected, but was 0.649
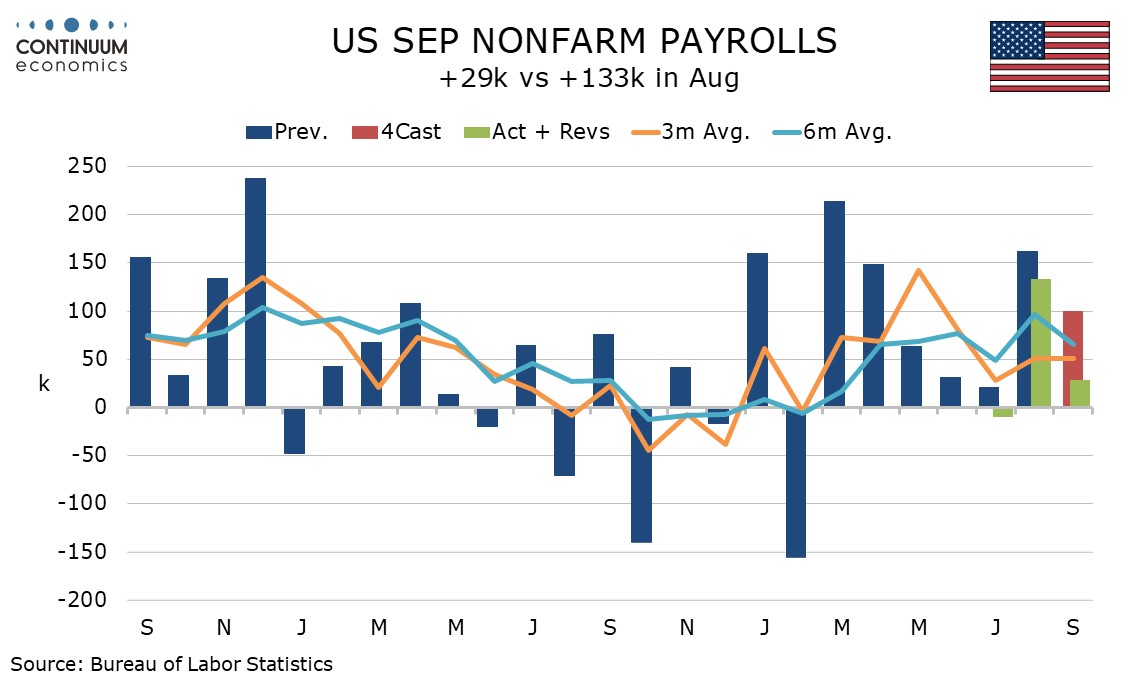
U.S. September Employment - Trend looking subdued again
October 2, 2026 1:12 PM UTC
September’s non-farm payroll at 23k, 46k private, with negative back revisions, is weaker than expected and returns the picture to near flat after the stronger August. Average hourly earnings are slowing, up only 0.1%, though the rise in unemployment to 4.2% from 4.1% is on a rise in the labor for
ECB Minutes Showed Unanimous Support for September’s hike
October 8, 2026 12:46 PM UTC
Minutes to the September meeting at which the deposit rate was increased by 25bps to 2.50% was backed by all members of the committee. The next meeting takes place in October 29th and it’s unlikely that the macro picture will have changed much in the next three weeks. One obvious discussion point
ECB won’t come to France’s rescue
October 7, 2026 1:55 PM UTC
Bottom Line: France’s 10-year government bond spread to Germany widened past the 2012 highs last week prompting market speculation that the ECB could soon deploy its Transmission Protection Instrument (TPI). However, TPI is unlikely to be implemented, firstly because the ECB has firmly dismissed t
UK GDP Preview: Growth Could Surprise Negatively in August
October 12, 2026 4:04 PM UTC
The economy is expected to have contracted by -0.1% m/m in August following a gain of 0.4% in July. Recall that July’s outturn was better than markets had ben expecting with growth boosted by the services sector, computer programming, and a spending boom in AI and cloud computing activities. Beyon
US Sep CPI in focus – upside risks persist?
October 12, 2026 11:28 AM UTC
While we look for a consensus 0.2% core CPI, background trends do suggest some risks
Both seasonals and high headline CPI months bring some generic upside skews
Along with French/euro developments, CPI prints are the major focus for the week, dollar defensively supported prior
DM Yield Curves and 2yr to Policy Rate Spreads
October 7, 2026 9:45 AM UTC
· The scale of the September yield rise was driven mainly policy rate tightening ideas and an extra real yield premium. However, the rise in bond volatility, plus the role of speculative funds appears to have amplified the move. Moderate or major bond positive news could see a parti
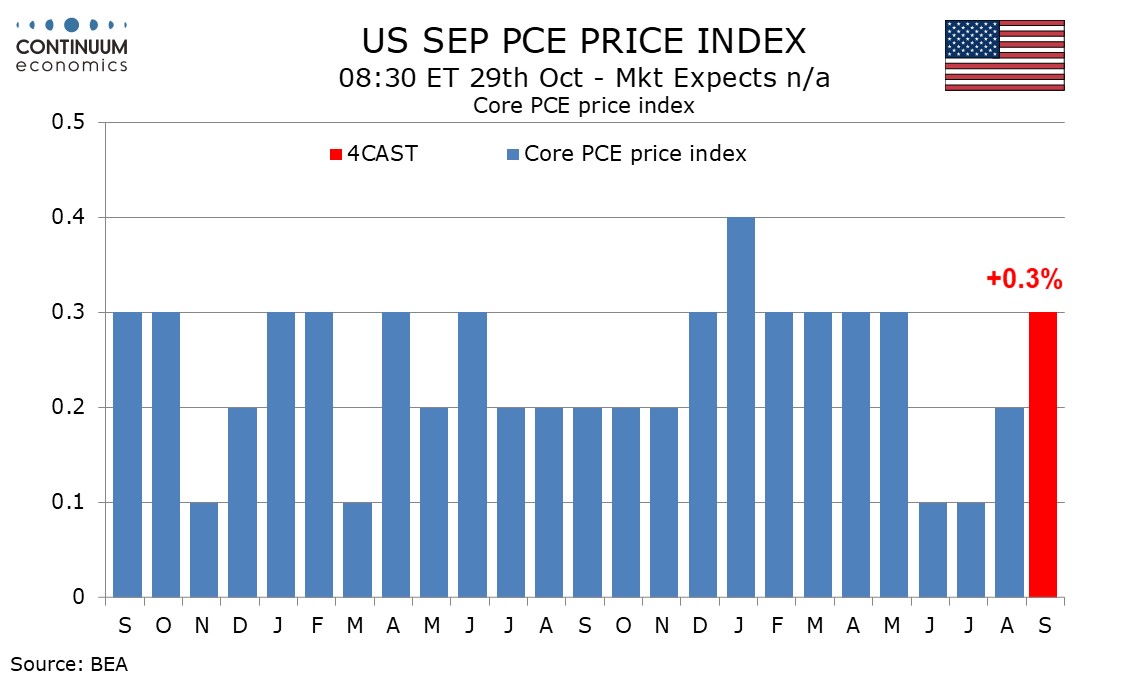
Preview: Due October 29 - U.S. September Personal Income and Spending - Four-month high for core PCE prices
October 15, 2026 6:03 PM UTC
September’s personal income and spending report may be overshadowed by the Q3 GDP release which is due at the same time and will include Q3 totals for each of its components. We expect a 0.3% rise in personal income and a 0.6% rise in spending, with overall PCE prices up by 0.5%, exceeding perso
UK Growth Resilience Continues in August
October 15, 2026 7:32 AM UTC
In the event, growth did not contract by 0.1% m/m as consensus had expected, but grew 0.1% in August. While the month-on-month number can be volatile, the more reliable 3-month measure is showing the economy is proving to be a lot more resilient than many had expected. The better growth outturn alon