View:
November 09, 2026

FX Daily Strategy: Asia, Nov 10

November 9, 2026 4:15 PM UTC
Risk attempts to bounce on oil and tech lift, but outlook still unclear
Back from the noise, EUR/USD not far from 1.12 pivot, and DXY stuck in a 1 figure range
Positioning does remain heavily defensive, especially on yen risk crosses
US CPI offers some normality. On-consensus results anticipated
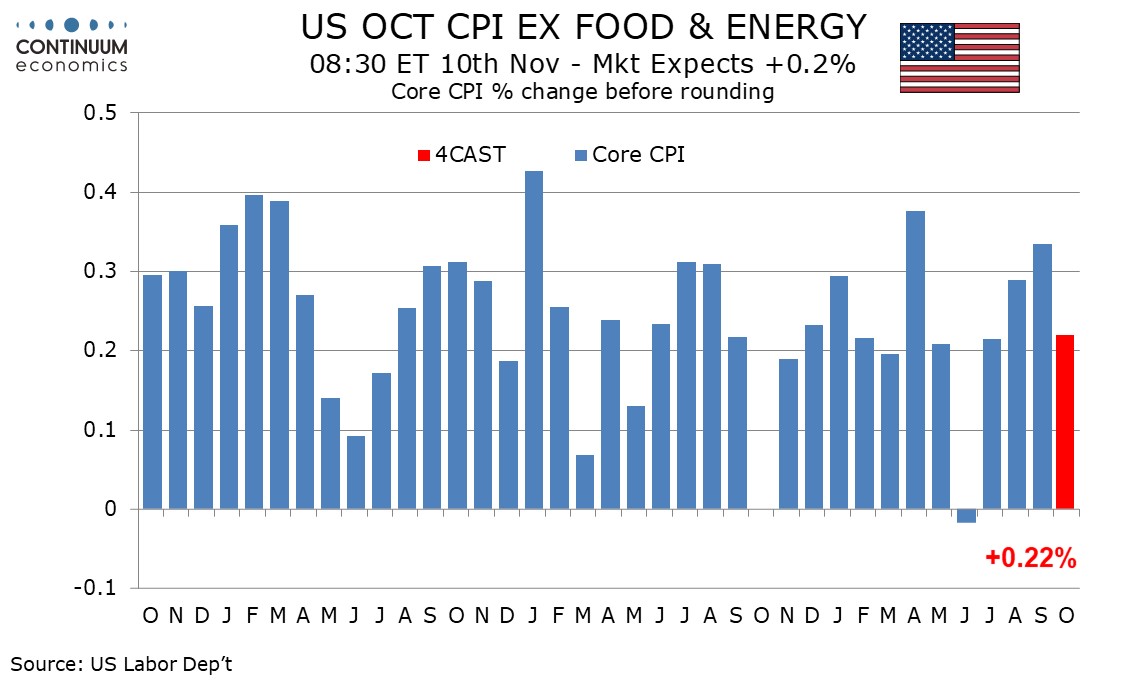
Preview: Due November 10 - U.S. October CPI - A more moderate month
November 9, 2026 1:04 PM UTC
We expect more subdued CPI in October after two straight disappointing 0.3% gains in the core rate, with October’s core rate seen at 0.2%, 0.22% before rounding. Gasoline prices have seen only a marginal rise on the month, and we expect overall CPI to also rise by 0.2%, though at 0.24% before roun
FX Weekly Strategy: N America, Nov 9-13
November 9, 2026 10:05 AM UTC
Focus remains on AI-risk. Nasdaq attempted to bounce but hasn't broken weak structure yet
US CPI, a relatively sedate month expected. Only partial offset to payrolls, though mmkt /bonds still more impulsively driven by risk
Even if some reactive consolidation, hard to pivot from defensive view on FX r
IMM Commitment of Traders Reports - euro shorts extend; large yen cross positioning
November 9, 2026 9:31 AM UTC
IMM data shows euro shorts nudging out further, now some 1.7stdev, largest since 2015 that got 10% bigger at peak
GBP short's retreat - though remain - on it's recent policy and fiscal rank re-pricing
Positioning in classic risk off crosses quite extreme, NZD and AUD +2.7 and 2.5 stdev, versus -1.8std
FX Weekly Strategy: Europe, Nov 9-13
November 9, 2026 7:40 AM UTC
Focus remains on AI-risk. Nasdaq attempted to bounce but hasn't broken weak structure yet
US CPI, a relatively sedate month expected. Only partial offset to payrolls, though mmkt /bonds still more impulsively driven by risk
Even if some reactive consolidation, hard to pivot from defensive view on FX r
November 06, 2026
FX Weekly Strategy: Asia, Nov 9-13
November 6, 2026 4:14 PM UTC
Focus remains on AI-risk. Nasdaq attempts to bounce but hasn't broken weak structure yet
US CPI, a relatively sedate month expected. Only partial offset to payrolls, though mmkt /bonds still more impulsively driven by risk
Even if some reactive consolidation, hard to pivot from defensive view on FX ri
Canada October Employment - Even weaker outside public sector correction
November 6, 2026 2:25 PM UTC
Canada’s 4.7k decline in October employment is not as sharp as in the two preceding months but looks worse in the details. September’s 68.3k decline was fully explained by a 70k decline in the public sector. October’s decline came despite a 49.6k rebound in the public sector.