Macro Strategy
View:
October 02, 2026
U.S. September Employment - Trend looking subdued again

October 2, 2026 1:12 PM UTC
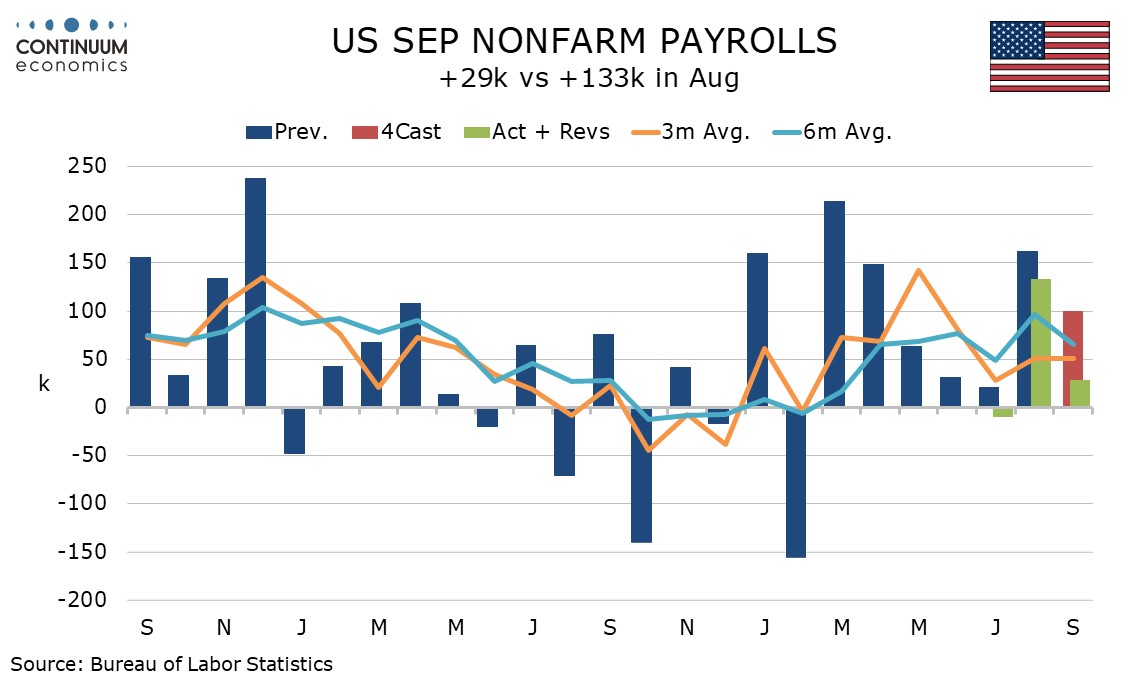
September’s non-farm payroll at 23k, 46k private, with negative back revisions, is weaker than expected and returns the picture to near flat after the stronger August. Average hourly earnings are slowing, up only 0.1%, though the rise in unemployment to 4.2% from 4.1% is on a rise in the labor for
U.S. September Employment - Trend looking subdued again
October 2, 2026 1:12 PM UTC
September’s non-farm payroll at 23k, 46k private, with negative back revisions, is weaker than expected and returns the picture to near flat after the stronger August. Average hourly earnings are slowing, up only 0.1%, though the rise in unemployment to 4.2% from 4.1% is on a rise in the labor for
October 01, 2026
Preview: Due October 2 - U.S. September Employment (Non-Farm Payrolls) - Healthy if less strong than August
October 1, 2026 1:06 PM UTC
We expect September’s non-farm payroll to rise by 100k both overall and in the private sector, slower than in August but still implying a healthy trend. We expect a 4.1% unemployment rate for a third straight month but a slightly slower 0.2% rise in average hourly earnings and a stable workweek. O
September 30, 2026
U.S. GDP, Income, Spending and PCE Price revisions mostly encouraging, but Trade Deficit is rising
September 30, 2026 1:51 PM UTC
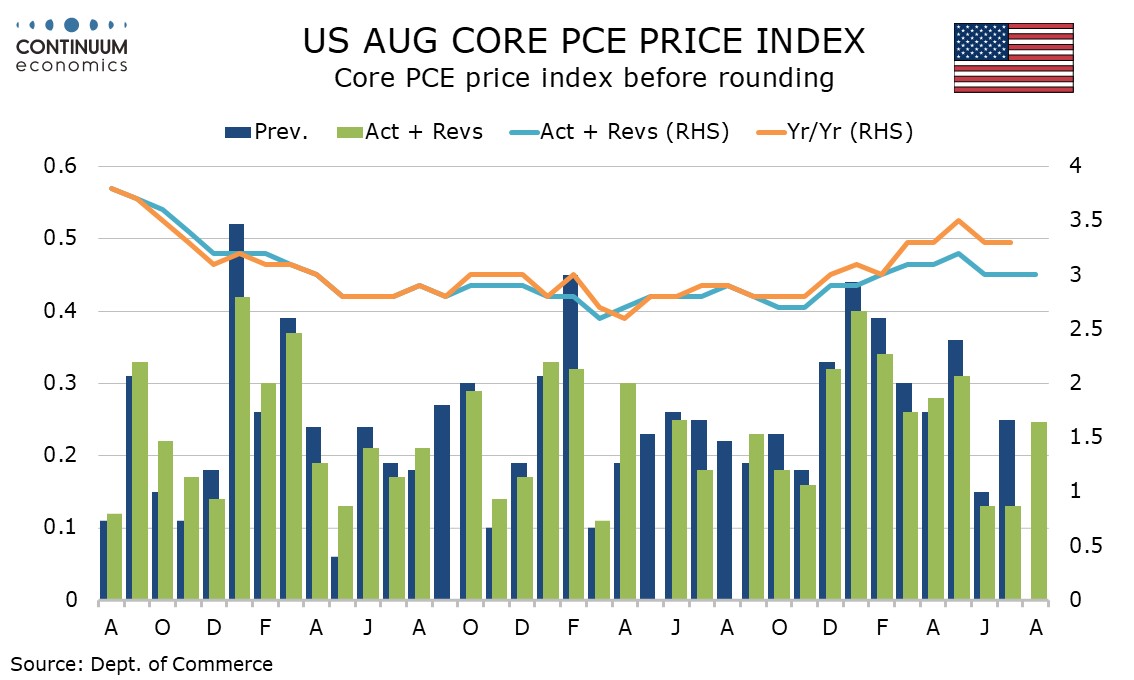
The final Q2 GDP report and August’s personal income and spending data are notable for historical revisions going back to 2021. The news in the revisions is generally encouraging, with upward revisions to GDP and real disposable income but downward revisions to PCE prices, led by non-market prices
U.S. GDP, Income, Spending and PCE Price revisions mostly encouraging, but Trade Deficit is rising
September 30, 2026 1:51 PM UTC
The final Q2 GDP report and August’s personal income and spending data are notable for historical revisions going back to 2021. The news in the revisions is generally encouraging, with upward revisions to GDP and real disposable income but downward revisions to PCE prices, led by non-market prices
September 29, 2026
Preview: Due October 14 - U.S. September CPI - Stronger, but with a slower core rate
September 29, 2026 6:03 PM UTC
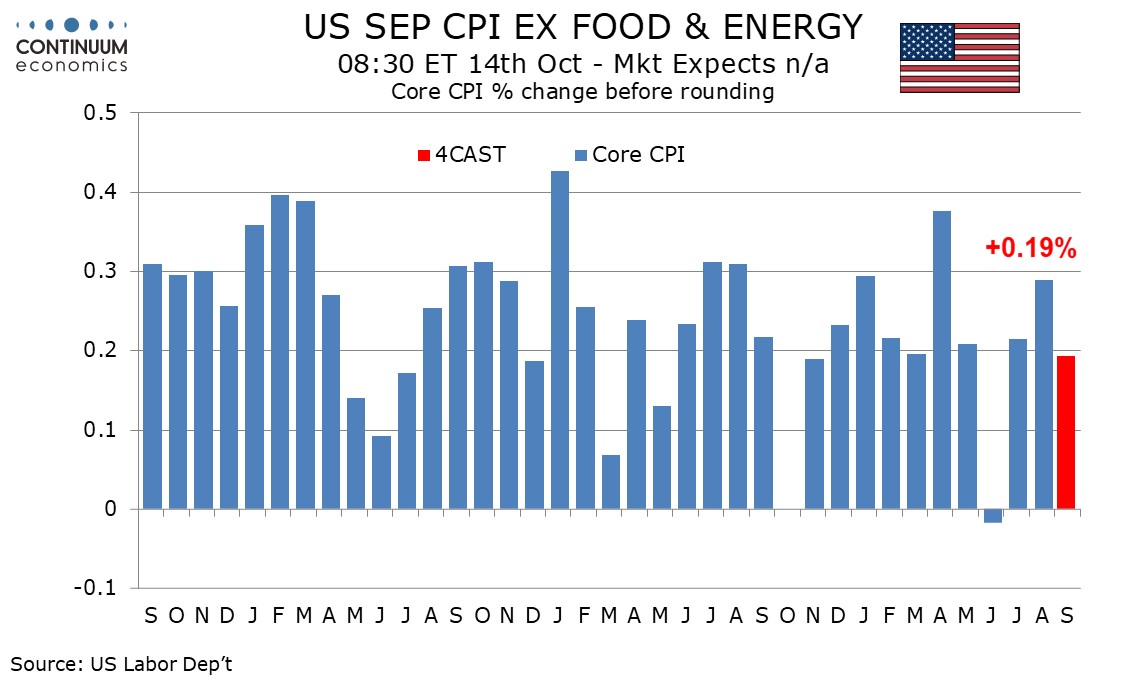
We expect a stronger rise of 0.6% in overall CPI in September, but a moderate 0.2% increase ex food and energy. Before rounding we expect the respective gains to be 0.57% and 0.19%. The latter would be a significant slowing from August’s 0.29%, but the former would be the strongest since April.
Preview: Due October 14 - U.S. September CPI - Stronger, but with a slower core rate
September 29, 2026 6:02 PM UTC
We expect a stronger rise of 0.6% in overall CPI in September, but a moderate 0.2% increase ex food and energy. Before rounding we expect the respective gains to be 0.57% and 0.19%. The latter would be a significant slowing from August’s 0.29%, but the former would be the strongest since April.
The 18yr Housing Cycle: Bent, Broken, or Still on Track
September 29, 2026 2:21 PM UTC
* Housing has reached the end of its classic 18yr cycle. Did Covid bring the peak, and part of the bust, forward? Or merely muddy a cycle that is still running into familiar inflation-rates pressure and financial cycle dangers on cue?
* Performances vary globally. Resilient cash prices disguise a rea
September 24, 2026
September 23, 2026
Outlook Overview: Navigation Into 2027
September 23, 2026 2:30 PM UTC
· The hot phase of the Iran war is over, but the intermittent conflict between the U.S. and Iran is stopping shipping via the Straits of Hormuz from fully recovering and keeping energy prices elevated. Some DM and EM central banks are guarding against 2nd round effects with modest tig
DM Rates Outlook: Long-term challenges, but selective short-term value
September 23, 2026 6:15 AM UTC
*Overweight gilts for 2027, focusing on intermediates. Large ‘policy uncertainty’ premium offers value on any less adverse Middle East scenario.
* Treasuries may offer tactical opportunity into weakness over Q4 2026-Q1 2027, with US10s projected back towards 4½% in respite. Longer term issues re
September 22, 2026
U.S. Outlook: Growth Overly Dependent on AI
September 22, 2026 1:34 PM UTC
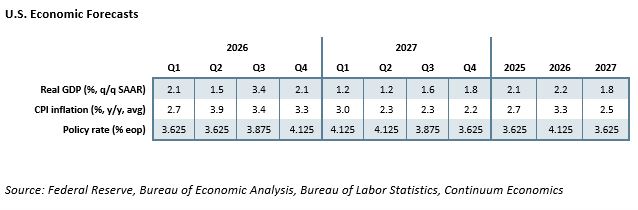
• The US economy is currently showing signs of acceleration with business investment strong led by AI and consumer spending outperforming real disposable income, in part because of AI-assisted strength in equities. We expect continued strength in business investment though a modest slowing
September 21, 2026
Preview: Due October 2 - U.S. September Employment (Non-Farm Payrolls) - Healthy if less strong than August
September 21, 2026 6:29 PM UTC
We expect September’s non-farm payroll to rise by 100k both overall and in the private sector, slower than in August but still maintaining a healthy trend. We expect a 4.1% unemployment rate for a third straight month but a slightly slower 0.2% rise in average hourly earnings and a stable workweek
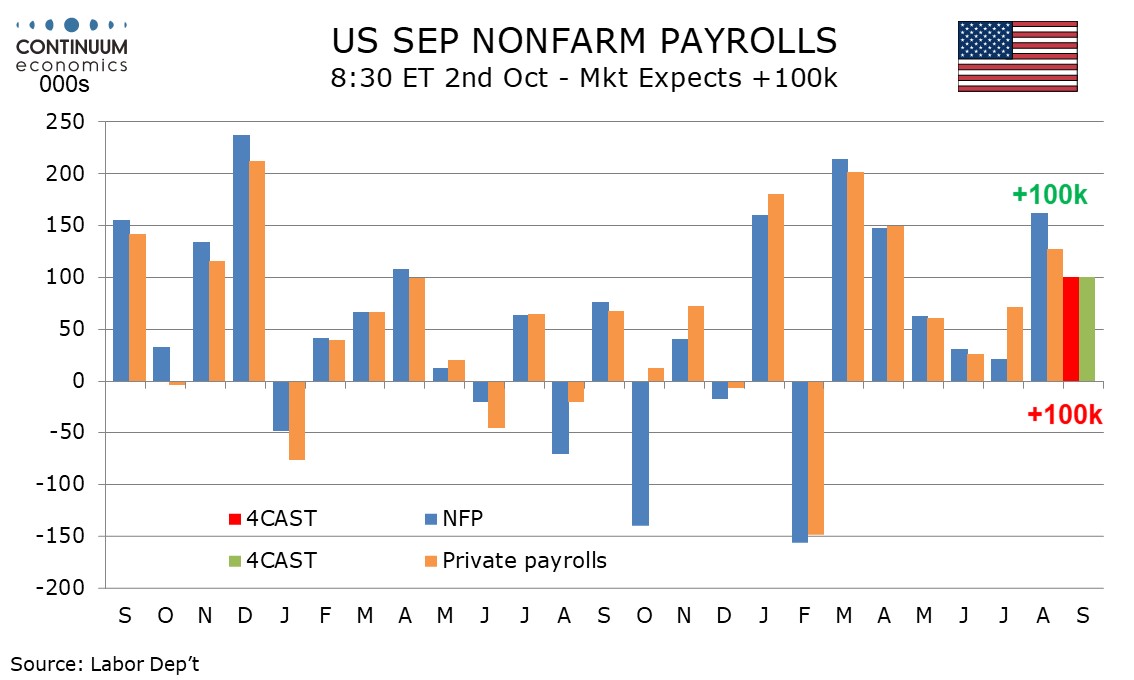
Preview: Due October 2 - U.S. September Employment (Non-Farm Payrolls) - Healthy if less strong than August
September 21, 2026 6:28 PM UTC
We expect September’s non-farm payroll to rise by 100k both overall and in the private sector, slower than in August but still maintaining a healthy trend. We expect a 4.1% unemployment rate for a third straight month but a slightly slower 0.2% rise in average hourly earnings and a stable workweek
Commodities Outlook: Brinkmanship
September 21, 2026 9:30 AM UTC
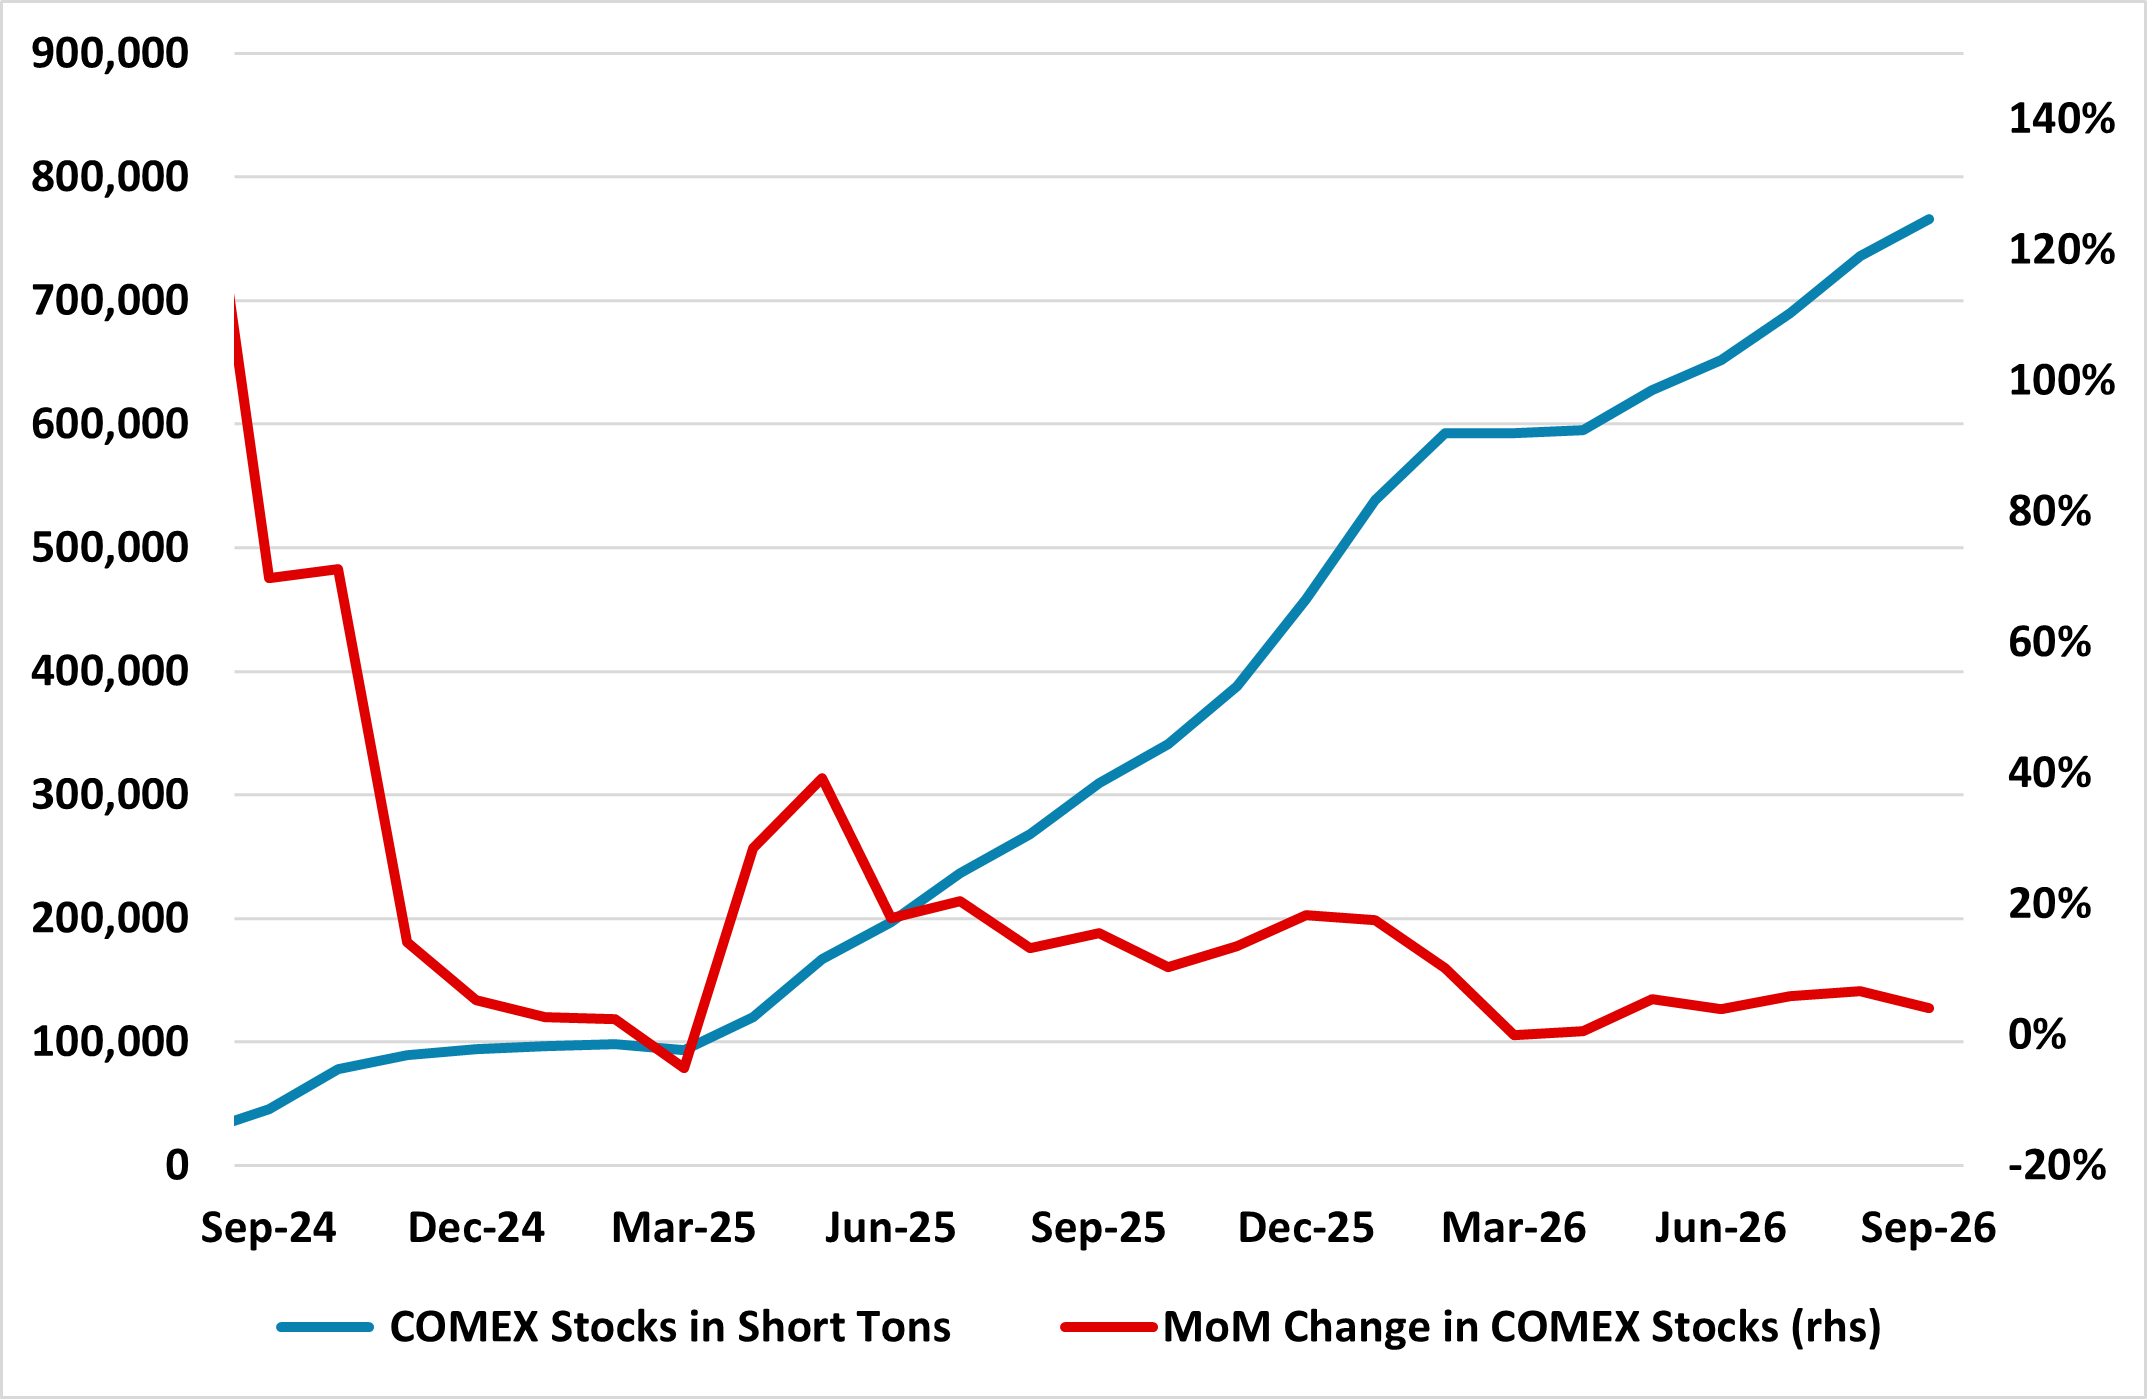
Transit through the Strait of Hormuz remains constrained for the rest of 2026, with a partial reopening most likely in Q1 2027 (60%) and no deal until well into 2027 in the alternative scenario (40%). We see WTI at USD 95 at end-2026 under both scenarios, then USD 70 baseline and USD 85 alternative
September 16, 2026
EM Money Supply: Trends Diverge from Policy Rates

September 16, 2026 11:15 AM UTC
· M2 growth in China remains weak (pre 2015 the trend had been double digit), despite the low level of nominal and real policy rates. This reflects credit demand and supply problems. M2 growth will likely remain restrained by Chinese standards and act as a drag of nominal and real GDP
September 14, 2026
Open AI Delay IPO and Safety Fears
September 14, 2026 6:59 AM UTC
· For financial markets, the Open AI IPO delay risks making the Open AI ecosystem more volatile, despite the huge private financing that it has already done this year. Additionally, the wider safety fears and calls for slowing by leading AI labs increase the risks surrounding the 2027
September 11, 2026
U.S. August CPI - Telephone services, air fares and hotels lift the core rate
September 11, 2026 1:08 PM UTC
August CPI is not a shocker at 0.4% overall, but the core rate of 0.3% ex food and energy is above expectations and where the Fed would like it to be and suggests tightening on September 16 is now likely. Before rounding core CPI rose by 0.29% and overall CPI by 0.396%. Telephone services are the ma

U.S. August CPI - Telephone services, air fares and hotels lift the core rate
September 11, 2026 1:07 PM UTC
August CPI is not a shocker at 0.4% overall, but the core rate of 0.3% ex food and energy is above expectations and where the Fed would like it to be and suggests tightening on September 16 is now likely. Before rounding core CPI rose by 0.29% and overall CPI by 0.396%. Telephone services are the ma
September 10, 2026
Preview: Due September 11 - U.S. August CPI - Firmer on energy and lodging away from home
September 10, 2026 1:15 PM UTC
We expect a slightly stronger US CPI in August, up by 0.4% overall, lifted by energy, and 0.3% ex food and energy, lifted by a correction higher in lodging away from home. Before rounding we expect overall CPI to rise by 0.37% and ex food and energy CPI to rise by 0.26%. Despite a firmer monthly cor
September 09, 2026
U.S. Equity-Treasury Strains and Correction Risk
September 9, 2026 8:00 AM UTC
· Equity investors have taken note of higher U.S. Treasury yields, but the influence of the AI boom and corporate earnings is greater. Nevertheless, the U.S. equity market valuation means that it is stretched currently versus the U.S. Treasury market and could be hurt by moderate bad
September 07, 2026
Strait of Hormuz Scenarios
September 7, 2026 7:32 AM UTC
Our new baseline (60%) is for a new ceasefire deal into Q4 2026 or Q1 2027 that allows more shipping to pass through the Strait of Hormuz. We feel that economic pressure on Iran remains intense and that Iran will want to lift the U.S. blockade on its energy shipments and export revenue. The Trump
September 04, 2026
U.S. August Employment - Bounce due to corrections in two sectors but could matter in a close Fed call
September 4, 2026 1:28 PM UTC
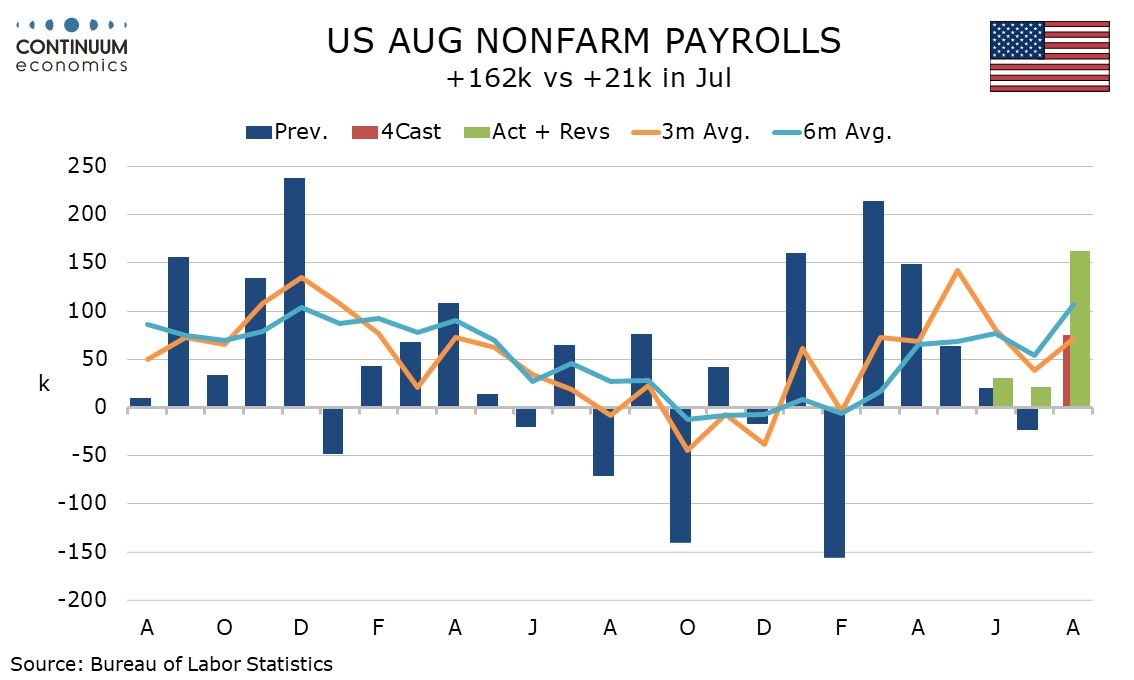
August non-farm payrolls are stronger than expected, 162k overall, 127k private, with upward back month revisions. Unemployment is steady at 4.1% and as expected as are average hourly earnings with a 0.3% rise, but the workweek at 34.4 hours is surprisingly strong. The payroll surprise looks correct
U.S. August Employment - Bounce due to corrections in two sectors but could matter in a close Fed call
September 4, 2026 1:27 PM UTC
August non-farm payrolls are stronger than expected, 162k overall, 127k private, with upward back month revisions. Unemployment is steady at 4.1% and as expected as are average hourly earnings with a 0.3% rise, but the workweek at 34.4 hours is surprisingly strong. The payroll surprise looks correct
September 03, 2026
Preview: Due September 4 - U.S. August Employment (Non-Farm Payrolls) - Corrections from recent payroll weakness and unemployment declines
September 3, 2026 2:31 PM UTC
We expect August’s non-farm payroll to rise by 75k both overall and in the private sector, still moderate but the strongest in both series since April. We however expect unemployment to correct higher to 4.2% after falling to 4.1% in July from 4.2% in June and before that three straight months at
August 31, 2026
Preview: Due September 11 - U.S. August CPI - Firmer on energy and lodging away from home
August 31, 2026 1:57 PM UTC
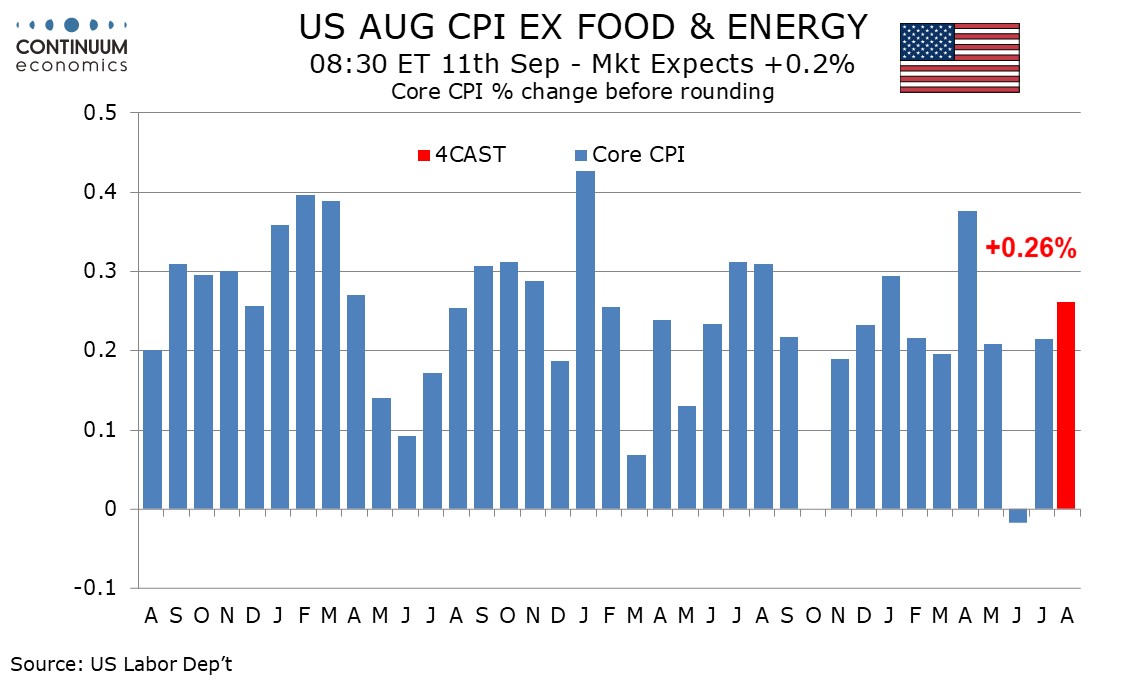
We expect a slightly stronger US CPI in August, up by 0.4% overall, lifted by energy, and 0.3% ex food and energy, lifted by a correction higher in lodging away from home. Before rounding we expect overall CPI to rise by 0.37% and ex food and energy CPI to rise by 0.26%. Despite a firmer monthly cor
Preview: Due September 11 - U.S. August CPI - Firmer on energy and lodging away from home
August 31, 2026 1:55 PM UTC
We expect a slightly stronger US CPI in August, up by 0.4% overall, lifted by energy, and 0.3% ex food and energy, lifted by a correction higher in lodging away from home. Before rounding we expect overall CPI to rise by 0.37% and ex food and energy CPI to rise by 0.26%. Despite a firmer monthly cor
August 20, 2026
Preview: Due September 4 - U.S. August Employment (Non-Farm Payrolls) - Corrections from recent payroll weakness and unemployment declines
August 20, 2026 4:58 PM UTC
We expect August’s non-farm payroll to rise by 75k both overall and in the private sector, still moderate but the strongest in both series since April. We however expect unemployment to correct higher to 4.2% after falling to 4.1% in July from 4.2% in June and before that three straight months at
August 17, 2026

From Hanging Chads to Hanging By a Thread – ‘Alternative’ US Election Risk Scenarios
August 17, 2026 9:22 AM UTC
* Without being alarmist, the market arguably needs to factor in the risk that the elections do not proceed smoothly to a clean conclusion. At the moment, there is no risk premia
* The markets hope that the destination is some degree of gridlock and thus reduction in extreme policy (albeit with mixed
August 12, 2026
U.S. July CPI - On consensus, detail a marginal disappointment
August 12, 2026 1:15 PM UTC
July’s CPI is largely as expected, up 0.1% overall and 0.2% ex food and energy, with the latter at 0.215% before rounding only a marginal disappointment, though possibly a little more so in the detail. This does not provide a compelling case for Fed tightening in September, though by that meeting

Big EM Currencies: No U.S. Yield Pressure
August 12, 2026 7:55 AM UTC
· Our view remains that major EM currencies outlooks are being driven by relative domestic fundamentals versus the U.S. No major tensions are being seen from rising U.S. Treasury yields and Fed tightening fears. H2 2026 will likely see the choppy EM FX conditions continue against the
August 11, 2026
Preview: Due August 12 - U.S. July CPI - Another subdued month, if less so than June
August 11, 2026 12:50 PM UTC
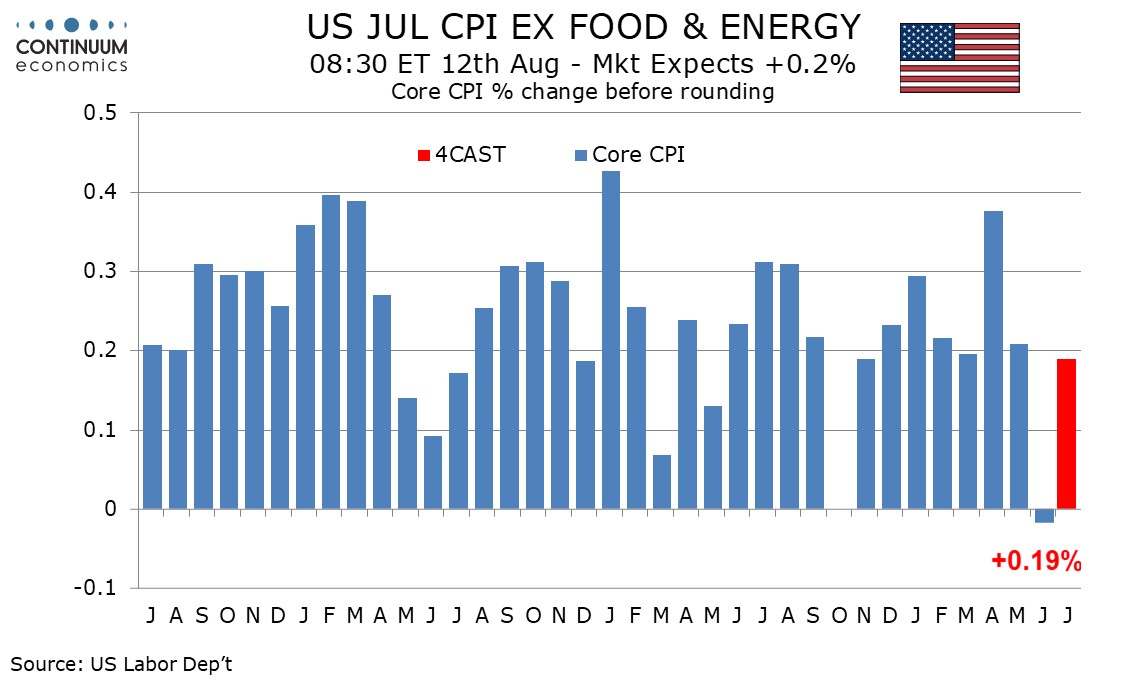
We expect a subdued July CPI, up by 0.1% overall and 0.2% ex food and energy, with the respective gains before rounding being only 0.06% and 0.19%. This will however be less weak than June’s 0.4% decline overall, with the June core rate ex food and energy having been unchanged.
Preview: Due August 12 - U.S. July CPI - Another subdued month, if less so than June
August 11, 2026 12:49 PM UTC
We expect a subdued July CPI, up by 0.1% overall and 0.2% ex food and energy, with the respective gains before rounding being only 0.06% and 0.19%. This will however be less weak than June’s 0.4% decline overall, with the June core rate ex food and energy having been unchanged.
August 07, 2026
U.S. July Employment - Softer payroll and falling unemployment hint at labor shortages, but no lift to earnings
August 7, 2026 1:21 PM UTC
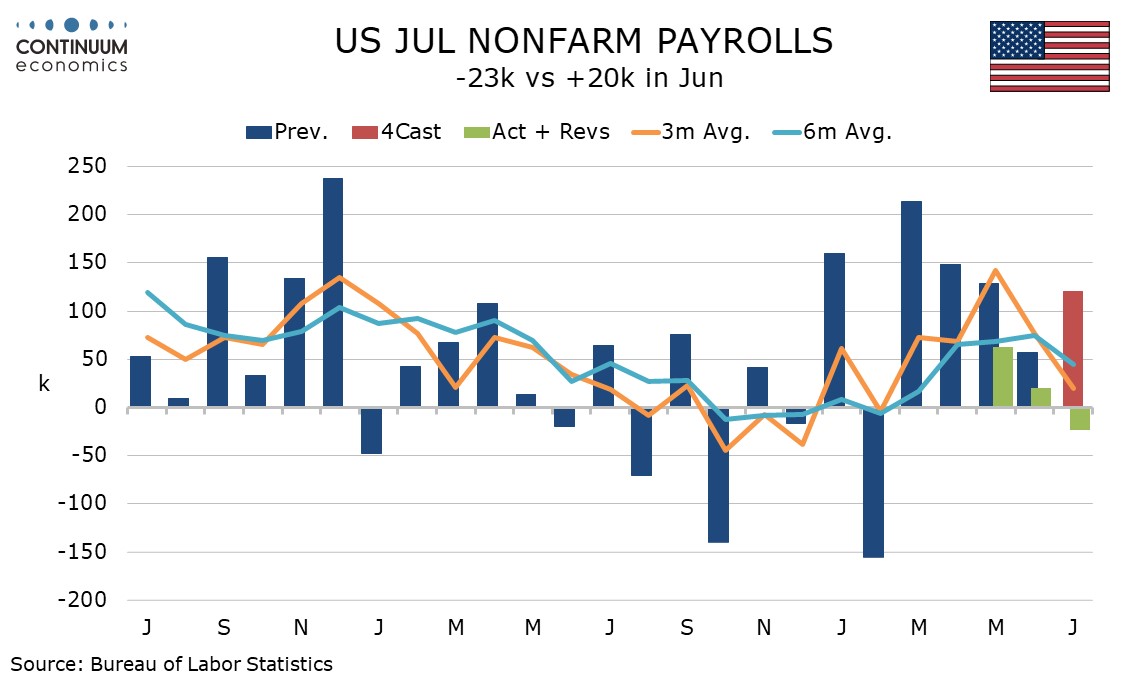
July’s non-farm payroll at -23k with negative back month revisions is weaker than expected but largely because of negatives in government led by local government education and leisure and hospitality, which may reflect labor shortages. A declining labor force saw the unemployment rate fall, to 4.1
U.S. July Employment - Softer payroll and falling unemployment hint at labor shortages, but no lift to earnings
August 7, 2026 1:20 PM UTC
July’s non-farm payroll at -23k with negative back month revisions is weaker than expected but largely because of negatives in government led by local government education and leisure and hospitality, which may reflect labor shortages. A declining labor force saw the unemployment rate fall, to 4.1
August 06, 2026
Preview: Due August 7 - U.S. July Employment (Non-Farm Payrolls) - Stronger than June, but with a rise in unemployment
August 6, 2026 1:27 PM UTC
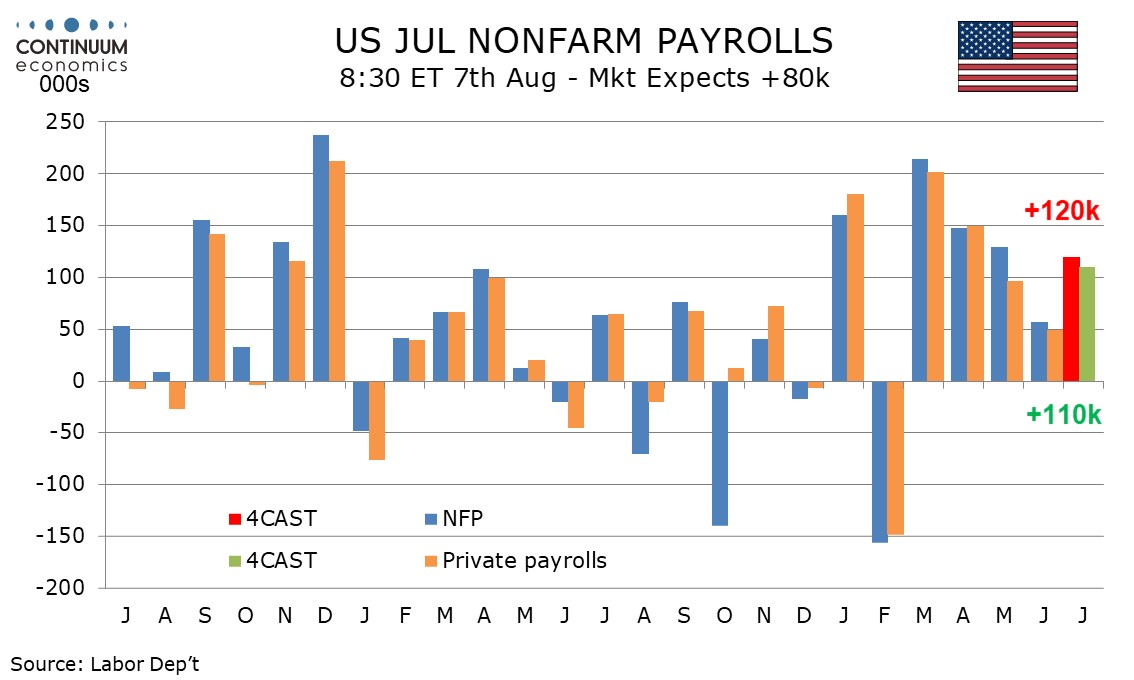
We expect July’s non-farm payroll to rise by 120k overall and by 110k in the private sector, a significant improvement from June’s respective gains of 57k and 49k but largely explained by a recovery in leisure and hospitality. We expect unemployment to rise to 4.3% from 4.2%, reversing a June de
Preview: Due August 7 - U.S. July Employment (Non-Farm Payrolls) - Stronger than June, but with a rise in unemployment
August 6, 2026 1:27 PM UTC
We expect July’s non-farm payroll to rise by 120k overall and by 110k in the private sector, a significant improvement from June’s respective gains of 57k and 49k but largely explained by a recovery in leisure and hospitality. We expect unemployment to rise to 4.3% from 4.2%, reversing a June de
August 05, 2026
AI Equities: Correction/Consolidation?
August 5, 2026 7:40 AM UTC
• Overall, we feel that recent movements have been a correction/consolidation in the AI equity story. AI specific revenue growth still remains healthy and will support multi-year plans over cloud computing growth and in turn semiconductor demand. Even so, slowing free cash flows and ove
July 31, 2026
Preview: Due August 12 - U.S. July CPI - Another subdued month, if less so than June
July 31, 2026 3:52 PM UTC
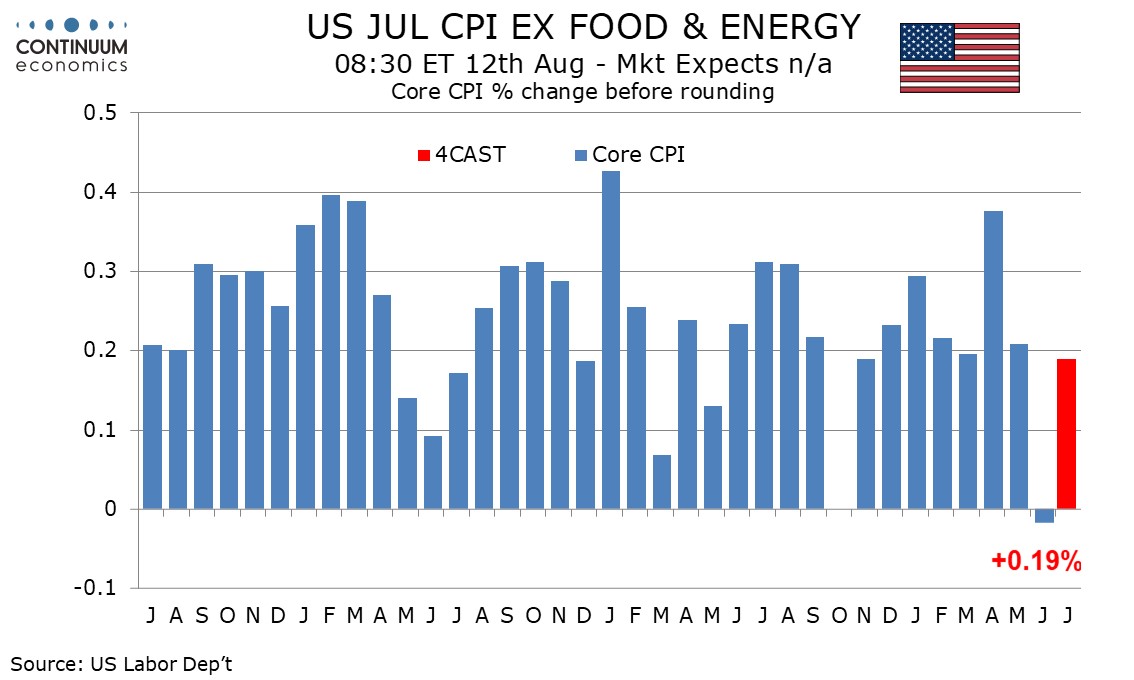
We expect a subdued July CPI, up by 0.1% overall and 0.2% ex food and energy, with the respective gains before rounding being only 0.06% and 0.19%. This will however be less weak than June’s 0.4% decline overall, with the June core rate ex food and energy having been unchanged.
Preview: Due August 12 - U.S. July CPI - Another subdued month, if less so than June
July 31, 2026 3:51 PM UTC
We expect a subdued July CPI, up by 0.1% overall and 0.2% ex food and energy, with the respective gains before rounding being only 0.06% and 0.19%. This will however be less weak than June’s 0.4% decline overall, with the June core rate ex food and energy having been unchanged.
July 30, 2026
U.S. Q2 GDP strong outside net exports, inventories and government
July 30, 2026 1:28 PM UTC
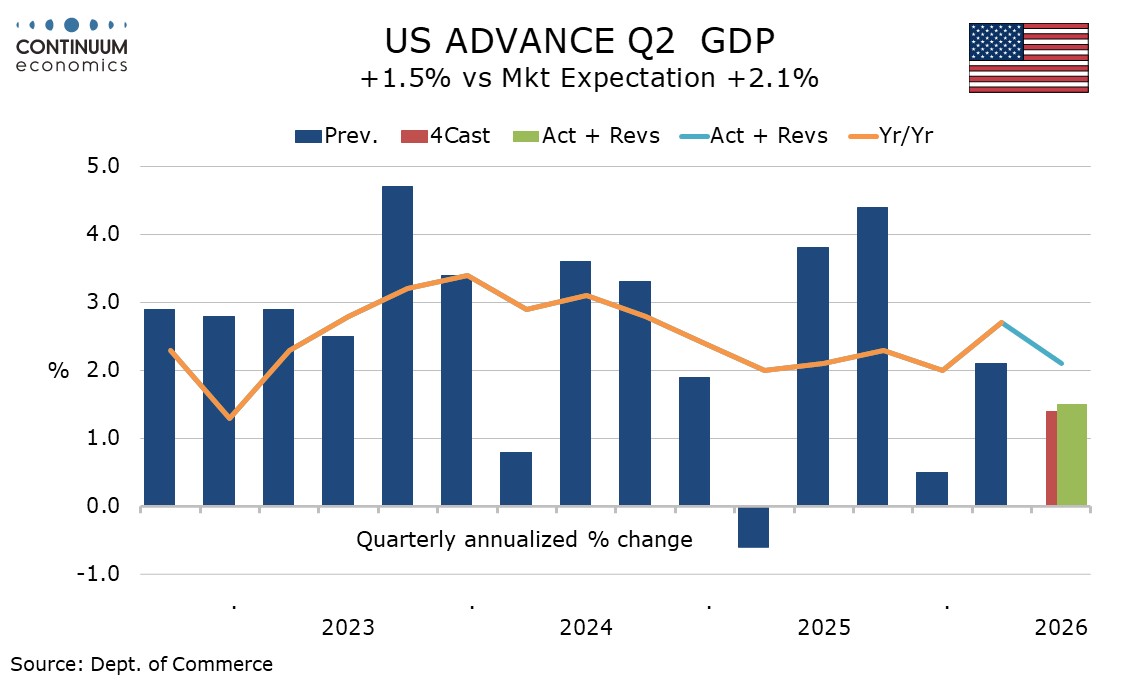
The advance estimate of Q2 GDP at 1.5% annualized is weaker than the market expected but in line with our 1.4% call. The detail is also broadly in line with our expectations, healthy excluding negatives from inventories and net exports, with final sales to domestic buyers (GDP ex inventories and net
U.S. Q2 GDP strong outside net exports, inventories and government
July 30, 2026 1:28 PM UTC
The advance estimate of Q2 GDP at 1.5% annualized is weaker than the market expected but in line with our 1.4% call. The detail is also broadly in line with our expectations, healthy excluding negatives from inventories and net exports, with final sales to domestic buyers (GDP ex inventories and net
July 29, 2026

July 28, 2026

Preview: Due August 7 - U.S. July Employment (Non-Farm Payrolls) - Stronger than June, but with a rise in unemployment
July 28, 2026 3:50 PM UTC
We expect July’s non-farm payroll to rise by 120k overall and by 110k in the private sector, a significant improvement from June’s respective gains of 57k and 49k but largely explained by a recovery in leisure and hospitality. We expect unemployment to rise to 4.3% from 4.2%, reversing a June de
Preview: Due August 7 - U.S. July Employment (Non-Farm Payrolls) - Stronger than June, but with a rise in unemployment
July 28, 2026 3:49 PM UTC
We expect July’s non-farm payroll to rise by 120k overall and by 110k in the private sector, a significant improvement from June’s respective gains of 57k and 49k but largely explained by a recovery in leisure and hospitality. We expect unemployment to rise to 4.3% from 4.2%, reversing a June de