United Kingdom
View:
September 30, 2026
September 29, 2026
The 18yr Housing Cycle: Bent, Broken, or Still on Track

September 29, 2026 2:21 PM UTC
* Housing has reached the end of its classic 18yr cycle. Did Covid bring the peak, and part of the bust, forward? Or merely muddy a cycle that is still running into familiar inflation-rates pressure and financial cycle dangers on cue?
* Performances vary globally. Resilient cash prices disguise a rea
September 24, 2026
September 23, 2026
Outlook Overview: Navigation Into 2027
September 23, 2026 2:30 PM UTC
· The hot phase of the Iran war is over, but the intermittent conflict between the U.S. and Iran is stopping shipping via the Straits of Hormuz from fully recovering and keeping energy prices elevated. Some DM and EM central banks are guarding against 2nd round effects with modest tig
DM Rates Outlook: Long-term challenges, but selective short-term value
September 23, 2026 6:15 AM UTC
*Overweight gilts for 2027, focusing on intermediates. Large ‘policy uncertainty’ premium offers value on any less adverse Middle East scenario.
* Treasuries may offer tactical opportunity into weakness over Q4 2026-Q1 2027, with US10s projected back towards 4½% in respite. Longer term issues re
September 22, 2026
DM ex U.S.: Weathering Higher Energy Prices

September 22, 2026 1:22 PM UTC
· EZ. We expect the Eurozone economy to remain resilient in coming quarters despite the ongoing energy shock. Household consumption growth should strengthen into 2027, supported by a recovery in real wage growth and by favourable employment increases. Increased defence and infrastructur
September 17, 2026
BOE Keeps Rates Unchanged but November Meeting a Close Call
September 17, 2026 12:29 PM UTC
As expected, the BOE kept rates unchanged with the committee voting 6-3 in favour of staying at 3.75%. MPC members Green, Mann and Pill voted to increase rates by 25bp, as they did in July. Today’s monetary policy statement is essentially unchanged from the July statement, with the focus still on
BOE Keeps Rates Unchanged but November Meeting a Close Call
September 17, 2026 12:26 PM UTC
As expected, the BOE kept rates unchanged with the committee voting 6-3 in favour of staying at 3.75%. MPC members Green, Mann and Pill voted to increase rates by 25bp, as they did in July. Today’s monetary policy statement is essentially unchanged from the July statement, with the focus still on
September 16, 2026
UK CPI Higher in August But as Expected
September 16, 2026 7:20 AM UTC
Headline inflation increased to 3.1% in August from 2.9% before and in line with expectations with the largest upward contribution coming from transport and in particularly motor fuels. The figures are not a surprise given that July’s short-lived dip in petrol and diesel prices were reversed in
UK CPI Higher in August But as Expected
September 16, 2026 7:20 AM UTC
Headline inflation increased to 3.1% in August from 2.9% before and in line with expectations with the largest upward contribution coming from transport and in particularly motor fuels. The figures are not a surprise given that July’s short-lived dip in petrol and diesel prices were reversed in
September 14, 2026
UK CPI Preview: Headline Inflation to Increase on Higher Energy Costs but no Second Round Effects
September 14, 2026 9:24 AM UTC
· Inflation figures will come ahead of BoE meeting on September 17 in which the Bank is expected to keep rates on hold. Headline annual inflation rose to 2.9% in July and is forecast to increase to 3.1% in August with core also ticking up to 2.7% from 2.6% previously. The numbers are un
UK CPI Preview: Headline Inflation to Increase on Higher Energy Costs but no Second Round Effects
September 14, 2026 9:22 AM UTC
· Inflation figures will come ahead of BoE meeting on September 17 in which the Bank is expected to keep rates on hold. Headline annual inflation rose to 2.9% in July and is forecast to increase to 3.1% in August with core also ticking up to 2.7% from 2.6% previously. The numbers are un
September 11, 2026

QT: BOE Slowdown But Not BOJ/ECB Yet
September 11, 2026 11:50 AM UTC
· The BOE will likely slow the pace of QT to GBP50bln pa at the September 17 MPC meeting, but the BOJ/ECB have no current plans to slow QT. The BOJ QT at 6% of GDP is huge and pushing up JGB yields and the BOJ could slow the pace over the winter into the spring once the next 25bps pol

UK GDP Growth defies expectations in July but expected to slow ahead
September 11, 2026 7:53 AM UTC
Contrary to expectations, the UK economy grew by 0.4% in July (on a month-on-month basis) against a forecast of zero growth. Activity during the month was driven by services (0.4%), production (0.2%) and construction (0.1%). The sector breakdown shows that growth in the services sector was driven pa
September 07, 2026
Strait of Hormuz Scenarios
September 7, 2026 7:32 AM UTC
Our new baseline (60%) is for a new ceasefire deal into Q4 2026 or Q1 2027 that allows more shipping to pass through the Strait of Hormuz. We feel that economic pressure on Iran remains intense and that Iran will want to lift the U.S. blockade on its energy shipments and export revenue. The Trump
September 02, 2026
BOE September Preview: No 2026 Hike
September 2, 2026 10:31 AM UTC
· BOE Bailey at Jackson hole highlighted the quite subdued 2nd round effects from the Iran war surge in energy prices, which suggests that the bulk of the MPC will likely not vote for a hike at the September 17 MPC meeting. A risk does exist of a Q4 hike, though our central view is fo
BOE September Preview: No 2026 Hike
September 2, 2026 10:30 AM UTC
· BOE Bailey at Jackson hole highlighted the quite subdued 2nd round effects from the Iran war surge in energy prices, which suggests that the bulk of the MPC will likely not vote for a hike at the September 17 MPC meeting. A risk does exist of a Q4 hike, though our central view is fo
August 31, 2026
UK External Account: The Ugly and the Good
August 31, 2026 11:02 AM UTC
· The UK has seen a ugly persistent worsening of the EU goods trade deficit since leaving the EU in 2020, but two current account trends are good. The UK is helped by a surging services surplus and also a pick-up in investment income from UK portfolios invested overseas. Nevertheless, G
August 28, 2026
August 25, 2026
UK inflation momentum, persistence and 2nd round: BoE in ‘wait and see’
August 25, 2026 8:36 AM UTC
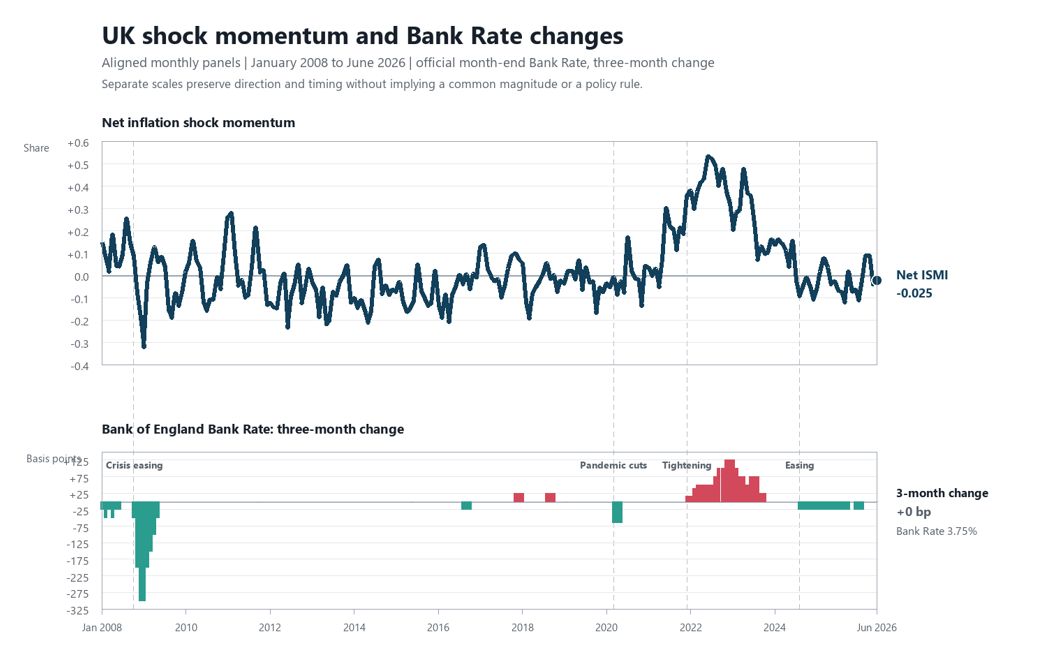
* Constructing alternative measures of inflation from the perspective of momentum, persistence, and second round expectations is useful when considering the BoE’s reaction function
* The message is partly reassuring but not fully and gives a nuanced picture
* Recent signals give time to wait and see
August 20, 2026

DM Central Banks Watching Stablecoins
August 20, 2026 10:55 AM UTC
· Overall, DM central banks have a watching brief for stablecoins and the scale of growth in the next 5 years. This is largely a USD centric issue, with stablecoins dominated by USD issuance. Central banks are watchful on whether it impacts access to low cost deposit for banks; guardi
August 19, 2026
UK CPI: Energy Prices and Weak Labour Market
August 19, 2026 6:29 AM UTC
· July UK CPI was broadly as expected and the new few months will be volatile and dependent on whether more shipping can go through the Straits of Hormuz and reduce energy prices (our baseline with a 60% probability). Underlying inflation trends in the UK are lower, as labour market d

UK CPI: Energy Prices and Weak Labour Market
August 19, 2026 6:28 AM UTC
· July UK CPI was broadly as expected and the new few months will be volatile and dependent on whether more shipping can go through the Straits of Hormuz and reduce energy prices (our baseline with a 60% probability). Underlying inflation trends in the UK are lower, as labour market d
August 14, 2026
August 07, 2026
July 31, 2026
July 30, 2026
BOE: Split Does Not Mean September Hike
July 30, 2026 12:45 PM UTC
. · Overall, the July MPC minutes and monetary policy report/press conference suggest that the MPC is not convinced of a September hike and a worsening of energy price rises and/or 2nd round effects would be required to shift the voting to a 25bps hike. While the MPC has a hawkish
BOE: Split Does Not Mean September Hike
July 30, 2026 12:44 PM UTC
· Overall, the July MPC minutes and monetary policy report/press conference suggest that the MPC is not convinced of a September hike and a worsening of energy price rises and/or 2nd round effects would be required to shift the voting to a 25bps hike. While the MPC has a hawkish bias
July 24, 2026
July 22, 2026
BOE Preview: Hawkish Noises
July 22, 2026 6:12 AM UTC
• The BOE will likely maintain a hawkish bias on July 30, but are unlikely to signal a September hike. The June CPI did not really change this picture, with the core unchanged at 2.6%. Though BOE Bailey recently noted the unstable process (in the Straits of Hormuz and for energy prices), he
BOE Preview After CPI: Hawkish Noises
July 22, 2026 6:11 AM UTC
• The BOE will likely maintain a hawkish bias on July 30, but are unlikely to signal a September hike. The June CPI did not really change this picture, with the core unchanged at 2.6%. Though BOE Bailey recently noted the unstable process (in the Straits of Hormuz and for energy prices), he
July 21, 2026
UK Fiscal Policy and the New Chancellor
July 21, 2026 6:18 AM UTC
· Apprehension will exist until the Autumn budget, despite a repeated commitment by PM Burnham to stick to the fiscal rules. Spending commitments are clearer than tax raises measures, while new Chancellor Healey may not be strong enough to curtail spending pressures. This could mean
July 17, 2026
Economic Data and Events Week Ahead July 20-24
July 17, 2026 3:00 PM UTC
The highlight of the week comes from the ECB meeting and press conference, although we do not expect it to provide much guidance regarding September, sticking to the non-pre-commit language, to keep options open depending on data and geopolitical developments.
The UK has its busy week, but data is
July 16, 2026
UK GDP and BOE Question
July 16, 2026 6:23 AM UTC
· UK GDP rose 0.1% in May as expected, helped by services but with softness remaining in other areas. H2 will depend on businesses and consumers, where a BOE rate hike would dent sentiment and spending – we look for no change in policy rates in 2026 however, followed by 2027 cuts. A
July 14, 2026
Iran/U.S.: A New War or Escalating to Deescalate?
July 14, 2026 10:40 AM UTC
· Our baseline remains that the MOU will hold and that the Strait of Hormuz will reopen. Iran can be pressured economically by the U.S. naval blockade being re-established. Additionally, President Trump loves to escalate to de-escalate to get a deal. This is a 60% probability scenar
July 10, 2026

Economic Data and Events Week Ahead July 13-17
July 10, 2026 3:06 PM UTC
The most significant release of the week is likely to be June’s CPI on Tuesday, which we expect to be unchanged overall, but with a slightly firmer 0.3% rise ex food and energy, 0.26% before rounding. The CPI could however be overshadowed by testimony from Fed Chair Kevin Warsh to the House Financ
June 30, 2026
UK GDP Outlook Update – Still Fragile With Surveys Negative
June 30, 2026 4:13 PM UTC
It is the relative norm for an economy to be offering disparate signals at any one juncture, if not actual conflicting ones. This is certainly the case in the UK currently, where upbeat Q1 GDP data of 0.6% q/q have been, confirmed and notably by a perkier consumer. Such shots of real growth ar
June 26, 2026
Economic Data and Events Week Ahead Jun 29 - Jul 3
June 26, 2026 2:45 PM UTC
The week ahead has plenty of notable events, spanning Eurozone inflation on one side, to US payrolls on the other, and with central bank speakers all round - the ECB Sintra conference at the start of the week hears from Lagarde and then a panel that includes Warsh and Bailey.
June 25, 2026
June 24, 2026
Outlook Overview: Cyclical and Structural Forces
June 24, 2026 7:00 AM UTC
· The difference between 2nd round inflation effects from higher energy prices and 1st round effects that central banks can look through swings on whether the Straits of Hormuz will remain open in the coming months after the U.S./Iran interim agreement (here). Despite some tensions, we
June 23, 2026
DM Rates Outlook: Tightening or Easing?
June 23, 2026 8:15 AM UTC
· With the U.S./Iran interim agreement likely to hold and energy prices softening, our projected consumer slowdown will likely tilt the Fed not to hike in H2 2026 and to actually ease by 50bps in 2027, with 25bps moves in both Q2 and Q3. With 2yr yields consistent with a hike, the tra
DM and EM FX Outlook: Cross-Currents for H2 and 2027
June 23, 2026 8:00 AM UTC
· Our baseline for the coming quarters is that global FX is moving through a period of dollar bounce and cross-current positioning adjustment, rather than a clean return to the dollar downtrend. The near-term driver is the market's (over) hawkish reading of the June FOMC/Summary of Econ
DM ex U.S. EZ Outlook (Japan and Western Europe): Navigating the Post Iran War Period?
June 23, 2026 7:43 AM UTC
· We have revised 2026 Japan GDP only slightly lower to 0.8% as wage growth is solidly above 3%, which will support consumption for the rest of 2026/27. The extension of energy stimulus will cap headline inflation for Q2/Q3 2026. For the BOJ, despite hawkish forward guidance, the 1% r
June 22, 2026
Equities Outlook: AI Optimism, But Caution Elsewhere in DM economies
June 22, 2026 7:05 AM UTC
· In terms of the S&P500, we remain less concerned about high valuations in the tech sector provided AI labs growth remains fast. 12mth fwd information technology are mid-range in the 2020-26 experience rather than at the highs. Even so, heavy equity issuance by tech companies and a s
June 18, 2026
BOE: Gang of 6 and Steady 2026 Rates
June 18, 2026 11:27 AM UTC
Though Megan Greene joined Huw Pill in calling for a one off 25bps risk management hike, 6 MPC members feel that disinflation is showing through and a soft economy and labor market warrants waiting to see energy prices and potential 2nd round effects. This gang of 6 also feels that markets have ti
June 17, 2026
UK CPI Review: Inflation Peaking?
June 17, 2026 7:40 AM UTC
What have been energy induced price rises are starting to ease and may do so further In June before the OFGEM induced price rise hits July numbers. But a less worrying picture emerges in the latest (ie May) CPI and even PPI data. Indeed, once again, actual CPI have offered a more benign picture
June 15, 2026
U.S./Iran Interim Deal and Reopening Strait of Hormuz
June 15, 2026 12:32 PM UTC
· Our baseline (80%) is that the Strait of Hormuz will reopen in H2 2026 and remains open through 2027. However, logistics dislocation plus a switch from commercial inventory rundown to rebuilding will likely slow the decline in oil prices back towards normal levels (Figure 1). O
June 12, 2026
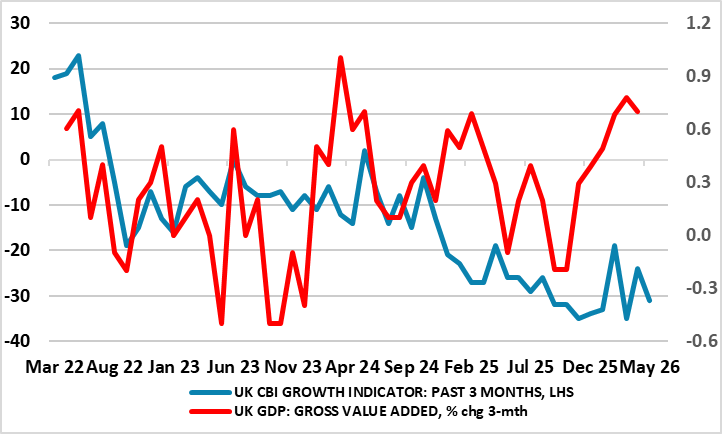
UK GDP Review: GDP Upside Surprises Persist?
June 12, 2026 6:56 AM UTC
Perhaps it is a supreme irony that just as business surveys suggest clear weakness, if not fresh contraction, the actual real economy has surprised on the upside, even now into the second month after the Middle East conflict started. Indeed, and in perspective, official GDP data suggest that since