Germany
View:
October 02, 2026
EZ Inflation Jumps - Still Energy Driven

October 2, 2026 10:34 AM UTC
Although headline inflation for September was higher than expected at 3.8%, when consensus forecast 3.2%, the narrative does not change. This is still an energy driven increase in inflation. The breakdown of overall inflation into major components showed that energy was the largest contributor to th
EZ Inflation Jumps - Still Energy Driven
October 2, 2026 10:33 AM UTC
Although headline inflation for September was higher than expected at 3.8%, when consensus forecast 3.2%, the narrative does not change. This is still an energy driven increase in inflation. The breakdown of overall inflation into major components showed that energy was the largest contributor to th
September 30, 2026
September 29, 2026
EZ HICP Review: Higher Inflation Ahead. How Will the ECB Respond?
September 29, 2026 4:27 PM UTC
Headline annual inflation is likely to increase again in September given the push from higher oil and gas prices. CPI numbers from member countries such as Spain already point to a likely strong jump in the EZ September while the increase in the European Commission Selling Prices indicator also back
EZ HICP Review: Higher Inflation Ahead. How Will the ECB Respond?

September 29, 2026 4:26 PM UTC
Headline annual inflation is likely to increase again in September given the push from higher oil and gas prices. CPI numbers from member countries such as Spain already point to a likely strong jump in the EZ September while the increase in the European Commission Selling Prices indicator also back
September 24, 2026
September 23, 2026
Outlook Overview: Navigation Into 2027
September 23, 2026 2:30 PM UTC
· The hot phase of the Iran war is over, but the intermittent conflict between the U.S. and Iran is stopping shipping via the Straits of Hormuz from fully recovering and keeping energy prices elevated. Some DM and EM central banks are guarding against 2nd round effects with modest tig
EZ PMIs Show Ongoing Growth Momentum in Q3
September 23, 2026 8:42 AM UTC
The S&P flash Eurozone PMI signalled a quickening in the pace of activity during September with the composite index rising to 53.1 from 52 before and boosted by rapid gains in the service sector and ongoing growth in the manufacturing sector. With September’s number now in hand the PMIs point to E
EZ PMIs Show Ongoing Growth Momentum in Q3
September 23, 2026 8:42 AM UTC
The S&P flash Eurozone PMI signalled a quickening in the pace of activity during September with the composite index rising to 53.1 from 52 before and boosted by rapid gains in the service sector and ongoing growth in the manufacturing sector. With September’s number now in hand the PMIs point to E
DM Rates Outlook: Long-term challenges, but selective short-term value
September 23, 2026 6:15 AM UTC
*Overweight gilts for 2027, focusing on intermediates. Large ‘policy uncertainty’ premium offers value on any less adverse Middle East scenario.
* Treasuries may offer tactical opportunity into weakness over Q4 2026-Q1 2027, with US10s projected back towards 4½% in respite. Longer term issues re
September 22, 2026
DM ex U.S.: Weathering Higher Energy Prices
September 22, 2026 1:22 PM UTC
· EZ. We expect the Eurozone economy to remain resilient in coming quarters despite the ongoing energy shock. Household consumption growth should strengthen into 2027, supported by a recovery in real wage growth and by favourable employment increases. Increased defence and infrastructur
September 11, 2026

QT: BOE Slowdown But Not BOJ/ECB Yet
September 11, 2026 11:50 AM UTC
· The BOE will likely slow the pace of QT to GBP50bln pa at the September 17 MPC meeting, but the BOJ/ECB have no current plans to slow QT. The BOJ QT at 6% of GDP is huge and pushing up JGB yields and the BOJ could slow the pace over the winter into the spring once the next 25bps pol
September 10, 2026
ECB Hikes by 25bp to 2.5%, leaves the door open – but no great urgency
September 10, 2026 3:16 PM UTC
Today’s decision to increase the deposit rate by 25bp to 2.5% came as no surprise given the uptick in headline euro area inflation, the energy market backdrop and recent comments from ECB members. President Lagarde in the press confidence said that today’s increase was a “no brainer” and a ?
ECB Hikes by 25bp to 2.5%, leaves the door open – but no great urgency
September 10, 2026 3:07 PM UTC
Today’s decision to increase the deposit rate by 25bp to 2.5% came as no surprise given the uptick in headline euro area inflation, the energy market backdrop and recent comments from ECB members. President Lagarde in the press confidence said that today’s increase was a “no brainer” and a ?
September 01, 2026
ECB Preview after EZ CPI: A 25bps Hike
September 1, 2026 9:14 AM UTC
· We feel that recent data or the continued hostilities between Iran and the U.S. do not argue for a U turn in the rate hike bias. Thus we now confirm a forecast of a 25bps hike at the September 10 ECB meeting. Nevertheless, we would also expect the ECB to then cool market expectation
ECB Preview after EZ CPI: A 25bps Hike
September 1, 2026 9:12 AM UTC
· We feel that recent data or the continued hostilities between Iran and the U.S. do not argue for a U turn in the rate hike bias. Thus we now confirm a forecast of a 25bps hike at the September 10 ECB meeting. Nevertheless, we would also expect the ECB to then cool market expectation
August 28, 2026
August 27, 2026
ECB Account: Hard Not to Read Between the Lines on Sep
August 27, 2026 1:01 PM UTC
* Some members would not have opposed raising rates at the last meeting
* While decisions remained data-dependent, another rate hike would likely be necessary unless the inflation outlook improved significantly
* Market participants appeared to have a good understanding of the ECB’s reaction functio
August 21, 2026
EZ PMI: Help From Manufacturing
August 21, 2026 9:23 AM UTC
· The headlines look reasonable, with the highlight being the August EZ Manufacturing PMI at 52.8 versus consensus of 51.8 (a general pick-up; help in Germany from defence spending and also some AI related output as well). This should keep reasonable expectations for Q3 GDP. However
August 20, 2026

DM Central Banks Watching Stablecoins
August 20, 2026 10:55 AM UTC
· Overall, DM central banks have a watching brief for stablecoins and the scale of growth in the next 5 years. This is largely a USD centric issue, with stablecoins dominated by USD issuance. Central banks are watchful on whether it impacts access to low cost deposit for banks; guardi
August 19, 2026

Running on Empty - Low Rivers could add to Europe’s Supply Squeeze
August 19, 2026 9:30 AM UTC
* Drought is not only directly impacting water-dependent activity, fire damage, and food crops. It is also seeing extreme low river levels across the major Rhine–Danube/Central-European industrial corridor
* That can significantly impact freight flow, adding to costs and disrupting industrial produ
August 14, 2026
August 07, 2026
July 31, 2026
EZ CPI: Boosted by Energy Prices
July 31, 2026 9:19 AM UTC
• The July provisional CPI provided no major surprise with the headline 2.9% Yr/Yr figure boosted by energy prices, but core at 2.5% and CPI ex energy unchanged at 2.2% Yr/Yr. Combined with the latest negotiated wage settlement data, we see no signs of 2nd round effects. For the ECB the dat
EZ CPI and ECB Rate Prospects
July 31, 2026 9:16 AM UTC
• The July provisional CPI provided no major surprise with the headline 2.9% Yr/Yr figure boosted by energy prices, but core at 2.5% and CPI ex energy unchanged at 2.2% Yr/Yr. Combined with the latest negotiated wage settlement data, we see no signs of 2nd round effects. For the ECB the dat
July 29, 2026
July 24, 2026
July 23, 2026
September 25bps ECB Hike: 50% Probability?
July 23, 2026 1:42 PM UTC
· Lagarde disclosed that some ECB board members considered a hike at today’s meeting and she noted that the consensus was to wait for incoming data before the September 10 meeting and then reassess. This clearly signals that the September meeting will seriously consider a 25bps hike,
ECB: September Hike 50% Probability?
July 23, 2026 1:41 PM UTC
· Lagarde disclosed that some ECB board members considered a hike at today’s meeting and she noted that the consensus was to wait for incoming data before the September 10 meeting and then reassess. This clearly signals that the September meeting will seriously consider a 25bps hike,
July 17, 2026
Economic Data and Events Week Ahead July 20-24
July 17, 2026 3:00 PM UTC
The highlight of the week comes from the ECB meeting and press conference, although we do not expect it to provide much guidance regarding September, sticking to the non-pre-commit language, to keep options open depending on data and geopolitical developments.
The UK has its busy week, but data is
ECB: Bark No Bite
July 17, 2026 7:05 AM UTC
· The vigilance mantra means that the ECB will still have a broad caution against 2nd round effects and the risks that energy prices could push higher. We feel that the June inflation data, plus the prospect that Iran/U.S. could call a new truce (here) will be enough to make most on t
July 14, 2026
Iran/U.S.: A New War or Escalating to Deescalate?
July 14, 2026 10:40 AM UTC
· Our baseline remains that the MOU will hold and that the Strait of Hormuz will reopen. Iran can be pressured economically by the U.S. naval blockade being re-established. Additionally, President Trump loves to escalate to de-escalate to get a deal. This is a 60% probability scenar
July 10, 2026

Economic Data and Events Week Ahead July 13-17
July 10, 2026 3:06 PM UTC
The most significant release of the week is likely to be June’s CPI on Tuesday, which we expect to be unchanged overall, but with a slightly firmer 0.3% rise ex food and energy, 0.26% before rounding. The CPI could however be overshadowed by testimony from Fed Chair Kevin Warsh to the House Financ
July 01, 2026
EZ HICP Review: Absence Second-Round Effects Continues
July 1, 2026 1:42 PM UTC
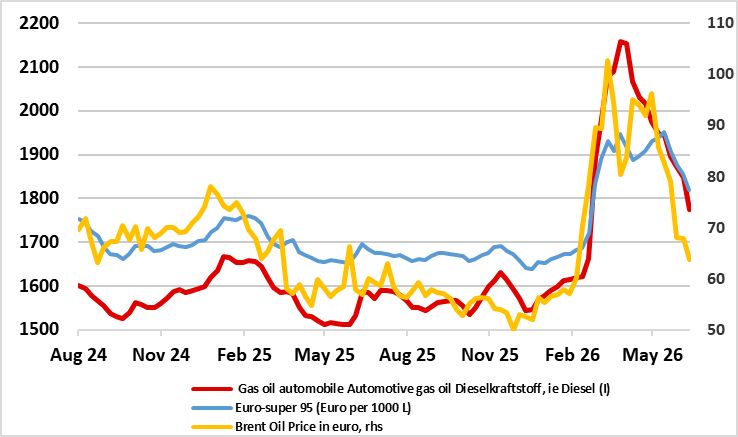
Contrary to some thinking, EZ HICP inflation continues to behave, both absolutely and relatively – ie to what looks ever excessive ECB price thinking. The question must be if and when the ECB chooses to note friendlier price and costs signals, rather than pander to the upside prices risks that o
EZ HICP Review: Absence Second-Round Effects Continues
July 1, 2026 10:41 AM UTC
Contrary to some thinking, EZ HICP inflation continues to behave, both absolutely and relatively – ie to what looks ever excessive ECB price thinking. The question must be if and when the ECB chooses to note friendlier price and costs signals, rather than pander to the upside prices risks that o
June 30, 2026
June 26, 2026
Economic Data and Events Week Ahead Jun 29 - Jul 3
June 26, 2026 2:45 PM UTC
The week ahead has plenty of notable events, spanning Eurozone inflation on one side, to US payrolls on the other, and with central bank speakers all round - the ECB Sintra conference at the start of the week hears from Lagarde and then a panel that includes Warsh and Bailey.
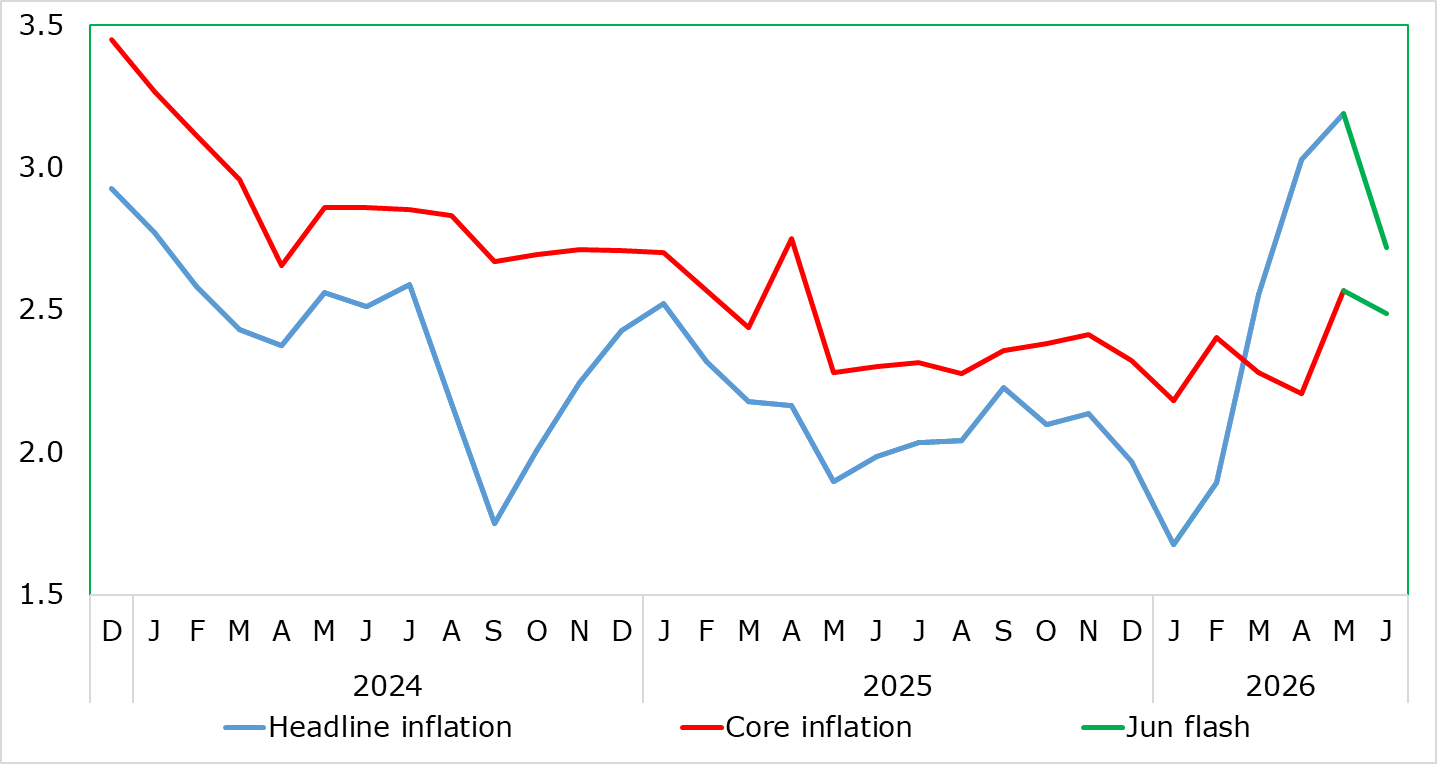
ECB Sin(a)tra Preview: Should the ECB Only Consider My Way?
June 26, 2026 1:29 PM UTC
The speed and manner in which the ECB adopted a hawkish stance is response to the Middle East conflict was no surprise; it has many precedents, some of which have led to policy errors which we think may be being repeated at this juncture. Indeed, despite friendlier price and costs signals, the ECB
June 25, 2026
June 24, 2026
Outlook Overview: Cyclical and Structural Forces
June 24, 2026 7:00 AM UTC
· The difference between 2nd round inflation effects from higher energy prices and 1st round effects that central banks can look through swings on whether the Straits of Hormuz will remain open in the coming months after the U.S./Iran interim agreement (here). Despite some tensions, we
June 23, 2026
DM Rates Outlook: Tightening or Easing?
June 23, 2026 8:15 AM UTC
· With the U.S./Iran interim agreement likely to hold and energy prices softening, our projected consumer slowdown will likely tilt the Fed not to hike in H2 2026 and to actually ease by 50bps in 2027, with 25bps moves in both Q2 and Q3. With 2yr yields consistent with a hike, the tra
DM and EM FX Outlook: Cross-Currents for H2 and 2027
June 23, 2026 8:00 AM UTC
· Our baseline for the coming quarters is that global FX is moving through a period of dollar bounce and cross-current positioning adjustment, rather than a clean return to the dollar downtrend. The near-term driver is the market's (over) hawkish reading of the June FOMC/Summary of Econ
June 22, 2026
Eurozone Outlook: Has Inflation Peaked Already?
June 22, 2026 11:35 AM UTC
· Under our only slightly updated view of no further fighting in the Middle East, we see oil and gas prices largely consolidating recent falls before falling afresh from mid-2027.The current situation is very different from that of 2022 and the Ukraine War in which the EZ lost access to
Germany/France/Italy and Spain: Growth and Inflation Outlooks
June 22, 2026 10:25 AM UTC
· We have retained our 2026 GDP picture of 0.3% (Our Forecasts below) and actually pared back that for next year, with more and more signs that China is continuing to ship cheap products to Germany (lower energy prices post Iran war still help 2027). For France, we have made a 0.3% do
Equities Outlook: AI Optimism, But Caution Elsewhere in DM economies
June 22, 2026 7:05 AM UTC
· In terms of the S&P500, we remain less concerned about high valuations in the tech sector provided AI labs growth remains fast. 12mth fwd information technology are mid-range in the 2020-26 experience rather than at the highs. Even so, heavy equity issuance by tech companies and a s
June 15, 2026
U.S./Iran Interim Deal and Reopening Strait of Hormuz
June 15, 2026 12:32 PM UTC
· Our baseline (80%) is that the Strait of Hormuz will reopen in H2 2026 and remains open through 2027. However, logistics dislocation plus a switch from commercial inventory rundown to rebuilding will likely slow the decline in oil prices back towards normal levels (Figure 1). O
June 11, 2026
ECB Review: If Not Insurance, Why the Hike?
June 11, 2026 2:27 PM UTC
The 25 bp official rate hike unveiled today was so well-flagged it is hard to suggest that it is consistent with a decision process on a meeting-by-meeting basis. Similarly, the dominance of inflation upside risks, alongside another dose of optimistic real economy projections, is hardly proper dat