Japan
View:
September 30, 2026
September 24, 2026
September 23, 2026
Outlook Overview: Navigation Into 2027

September 23, 2026 2:30 PM UTC
· The hot phase of the Iran war is over, but the intermittent conflict between the U.S. and Iran is stopping shipping via the Straits of Hormuz from fully recovering and keeping energy prices elevated. Some DM and EM central banks are guarding against 2nd round effects with modest tig
DM Rates Outlook: Long-term challenges, but selective short-term value
September 23, 2026 6:15 AM UTC
*Overweight gilts for 2027, focusing on intermediates. Large ‘policy uncertainty’ premium offers value on any less adverse Middle East scenario.
* Treasuries may offer tactical opportunity into weakness over Q4 2026-Q1 2027, with US10s projected back towards 4½% in respite. Longer term issues re
September 22, 2026
DM ex U.S.: Weathering Higher Energy Prices

September 22, 2026 1:22 PM UTC
· EZ. We expect the Eurozone economy to remain resilient in coming quarters despite the ongoing energy shock. Household consumption growth should strengthen into 2027, supported by a recovery in real wage growth and by favourable employment increases. Increased defence and infrastructur
September 18, 2026
BOJ: Future Policy Rate Hikes
September 18, 2026 7:16 AM UTC
· BOJ voted 7-2 for a 25bps hike to 1.25%, but neither the statement or Ueda press conference suggest a pick-up in the tightening pace. The economy and inflation remain more important than the JPY in BOJ decisions. The lagged feedthrough of the Iran war energy price shocks points to f
BOJ: Future Policy Rate Hikes
September 18, 2026 7:15 AM UTC
· BOJ voted 7-2 for a 25bps hike to 1.25%, but neither the statement or Ueda press conference suggest a pick-up in the tightening pace. The economy and inflation remain more important than the JPY in BOJ decisions. The lagged feedthrough of the Iran war energy price shocks points to f
September 11, 2026

QT: BOE Slowdown But Not BOJ/ECB Yet
September 11, 2026 11:50 AM UTC
· The BOE will likely slow the pace of QT to GBP50bln pa at the September 17 MPC meeting, but the BOJ/ECB have no current plans to slow QT. The BOJ QT at 6% of GDP is huge and pushing up JGB yields and the BOJ could slow the pace over the winter into the spring once the next 25bps pol
September 08, 2026
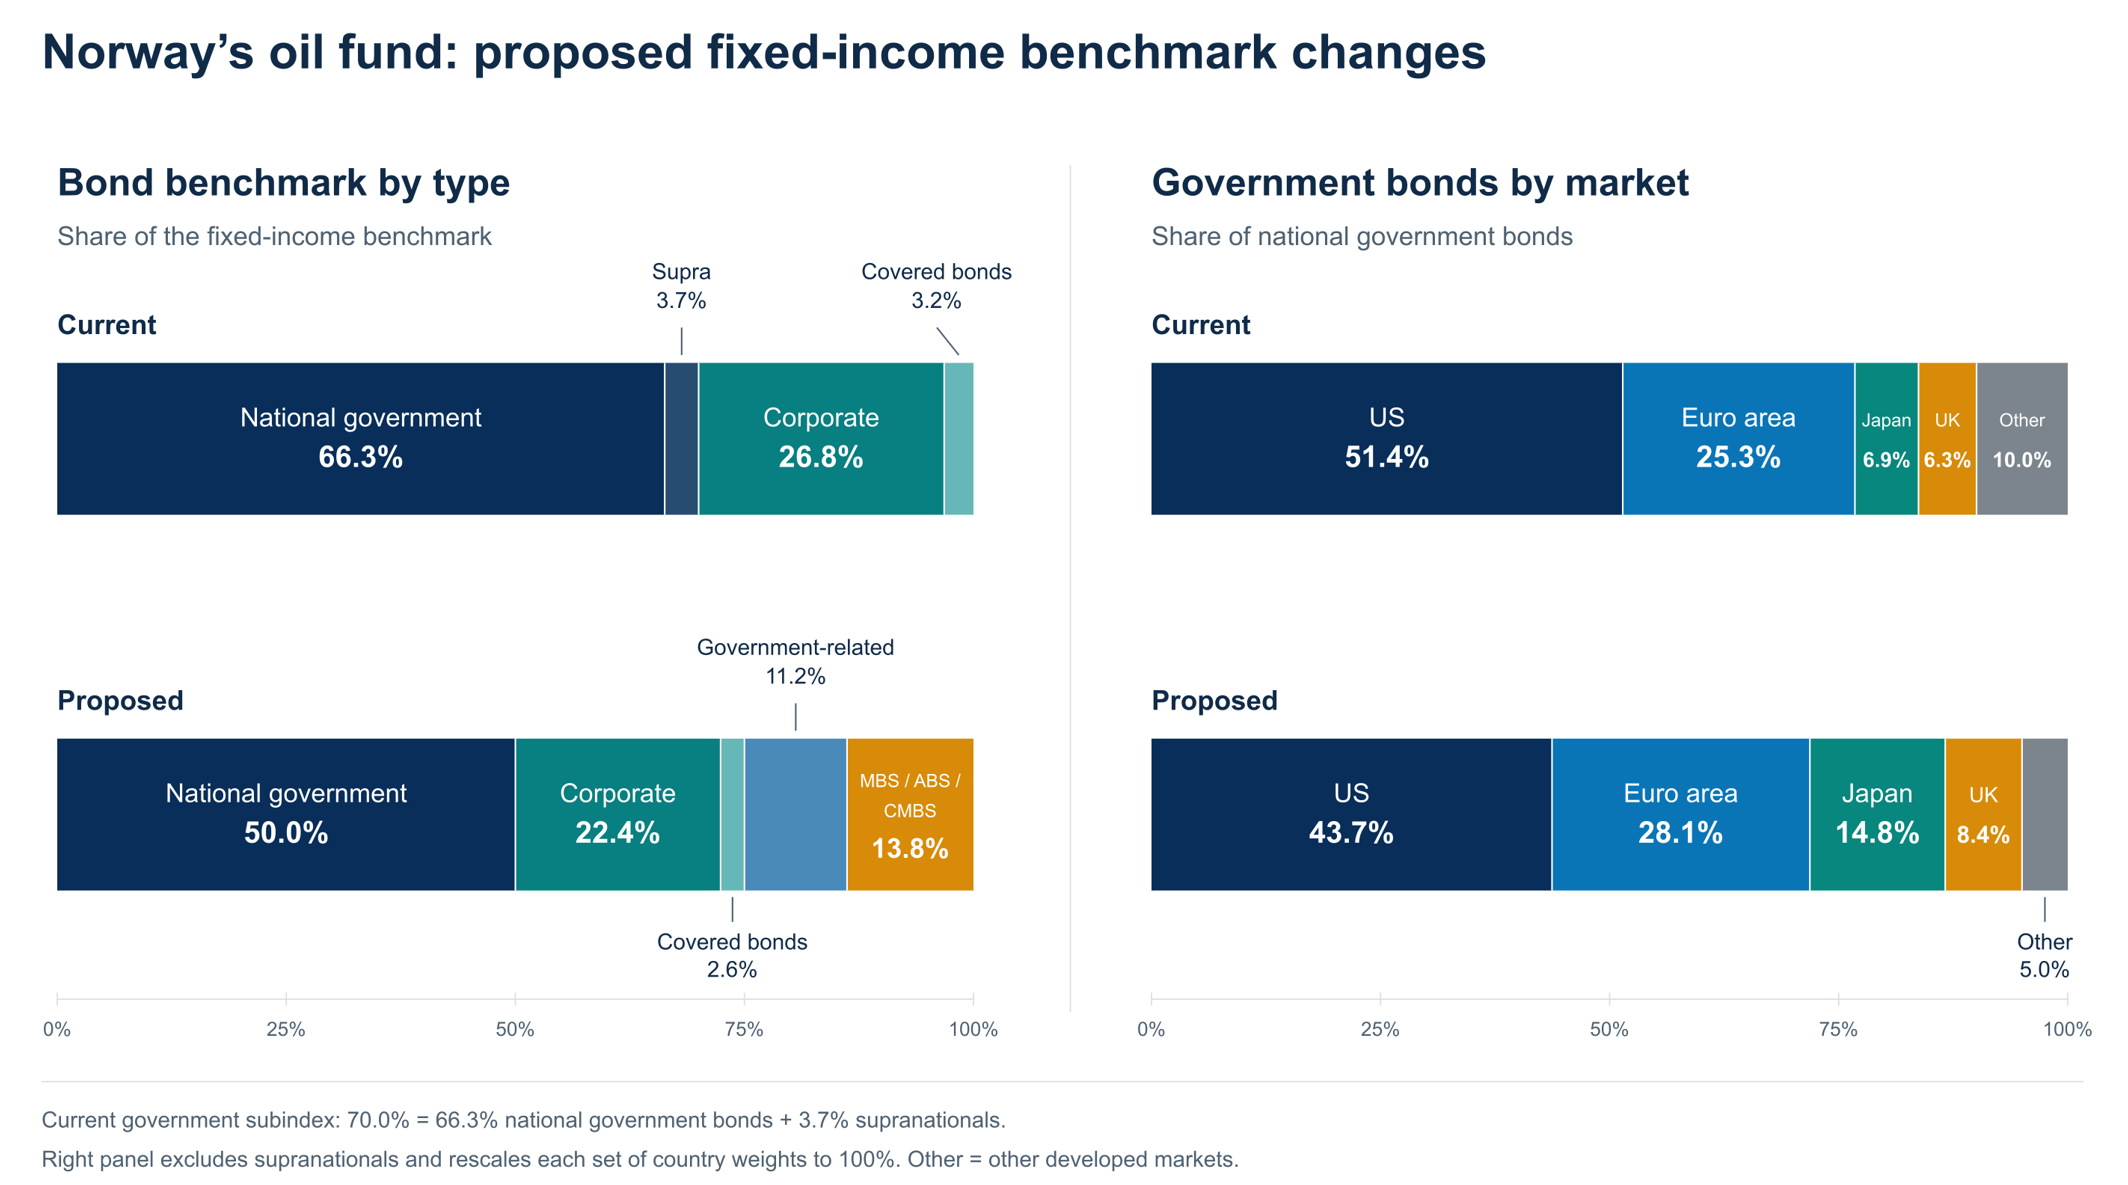
NBIM’s bond allocation rethink
September 8, 2026 7:30 AM UTC
* Proposal would imply $80bn~ Treasury sell, although little net USD change
* JGBs see marked pick up, presented as method change more than value, but…
* Several peers already follow broader bond mix. Is NBIM just ‘catch up’ or does to speak to wider concerns and incentives?
September 01, 2026
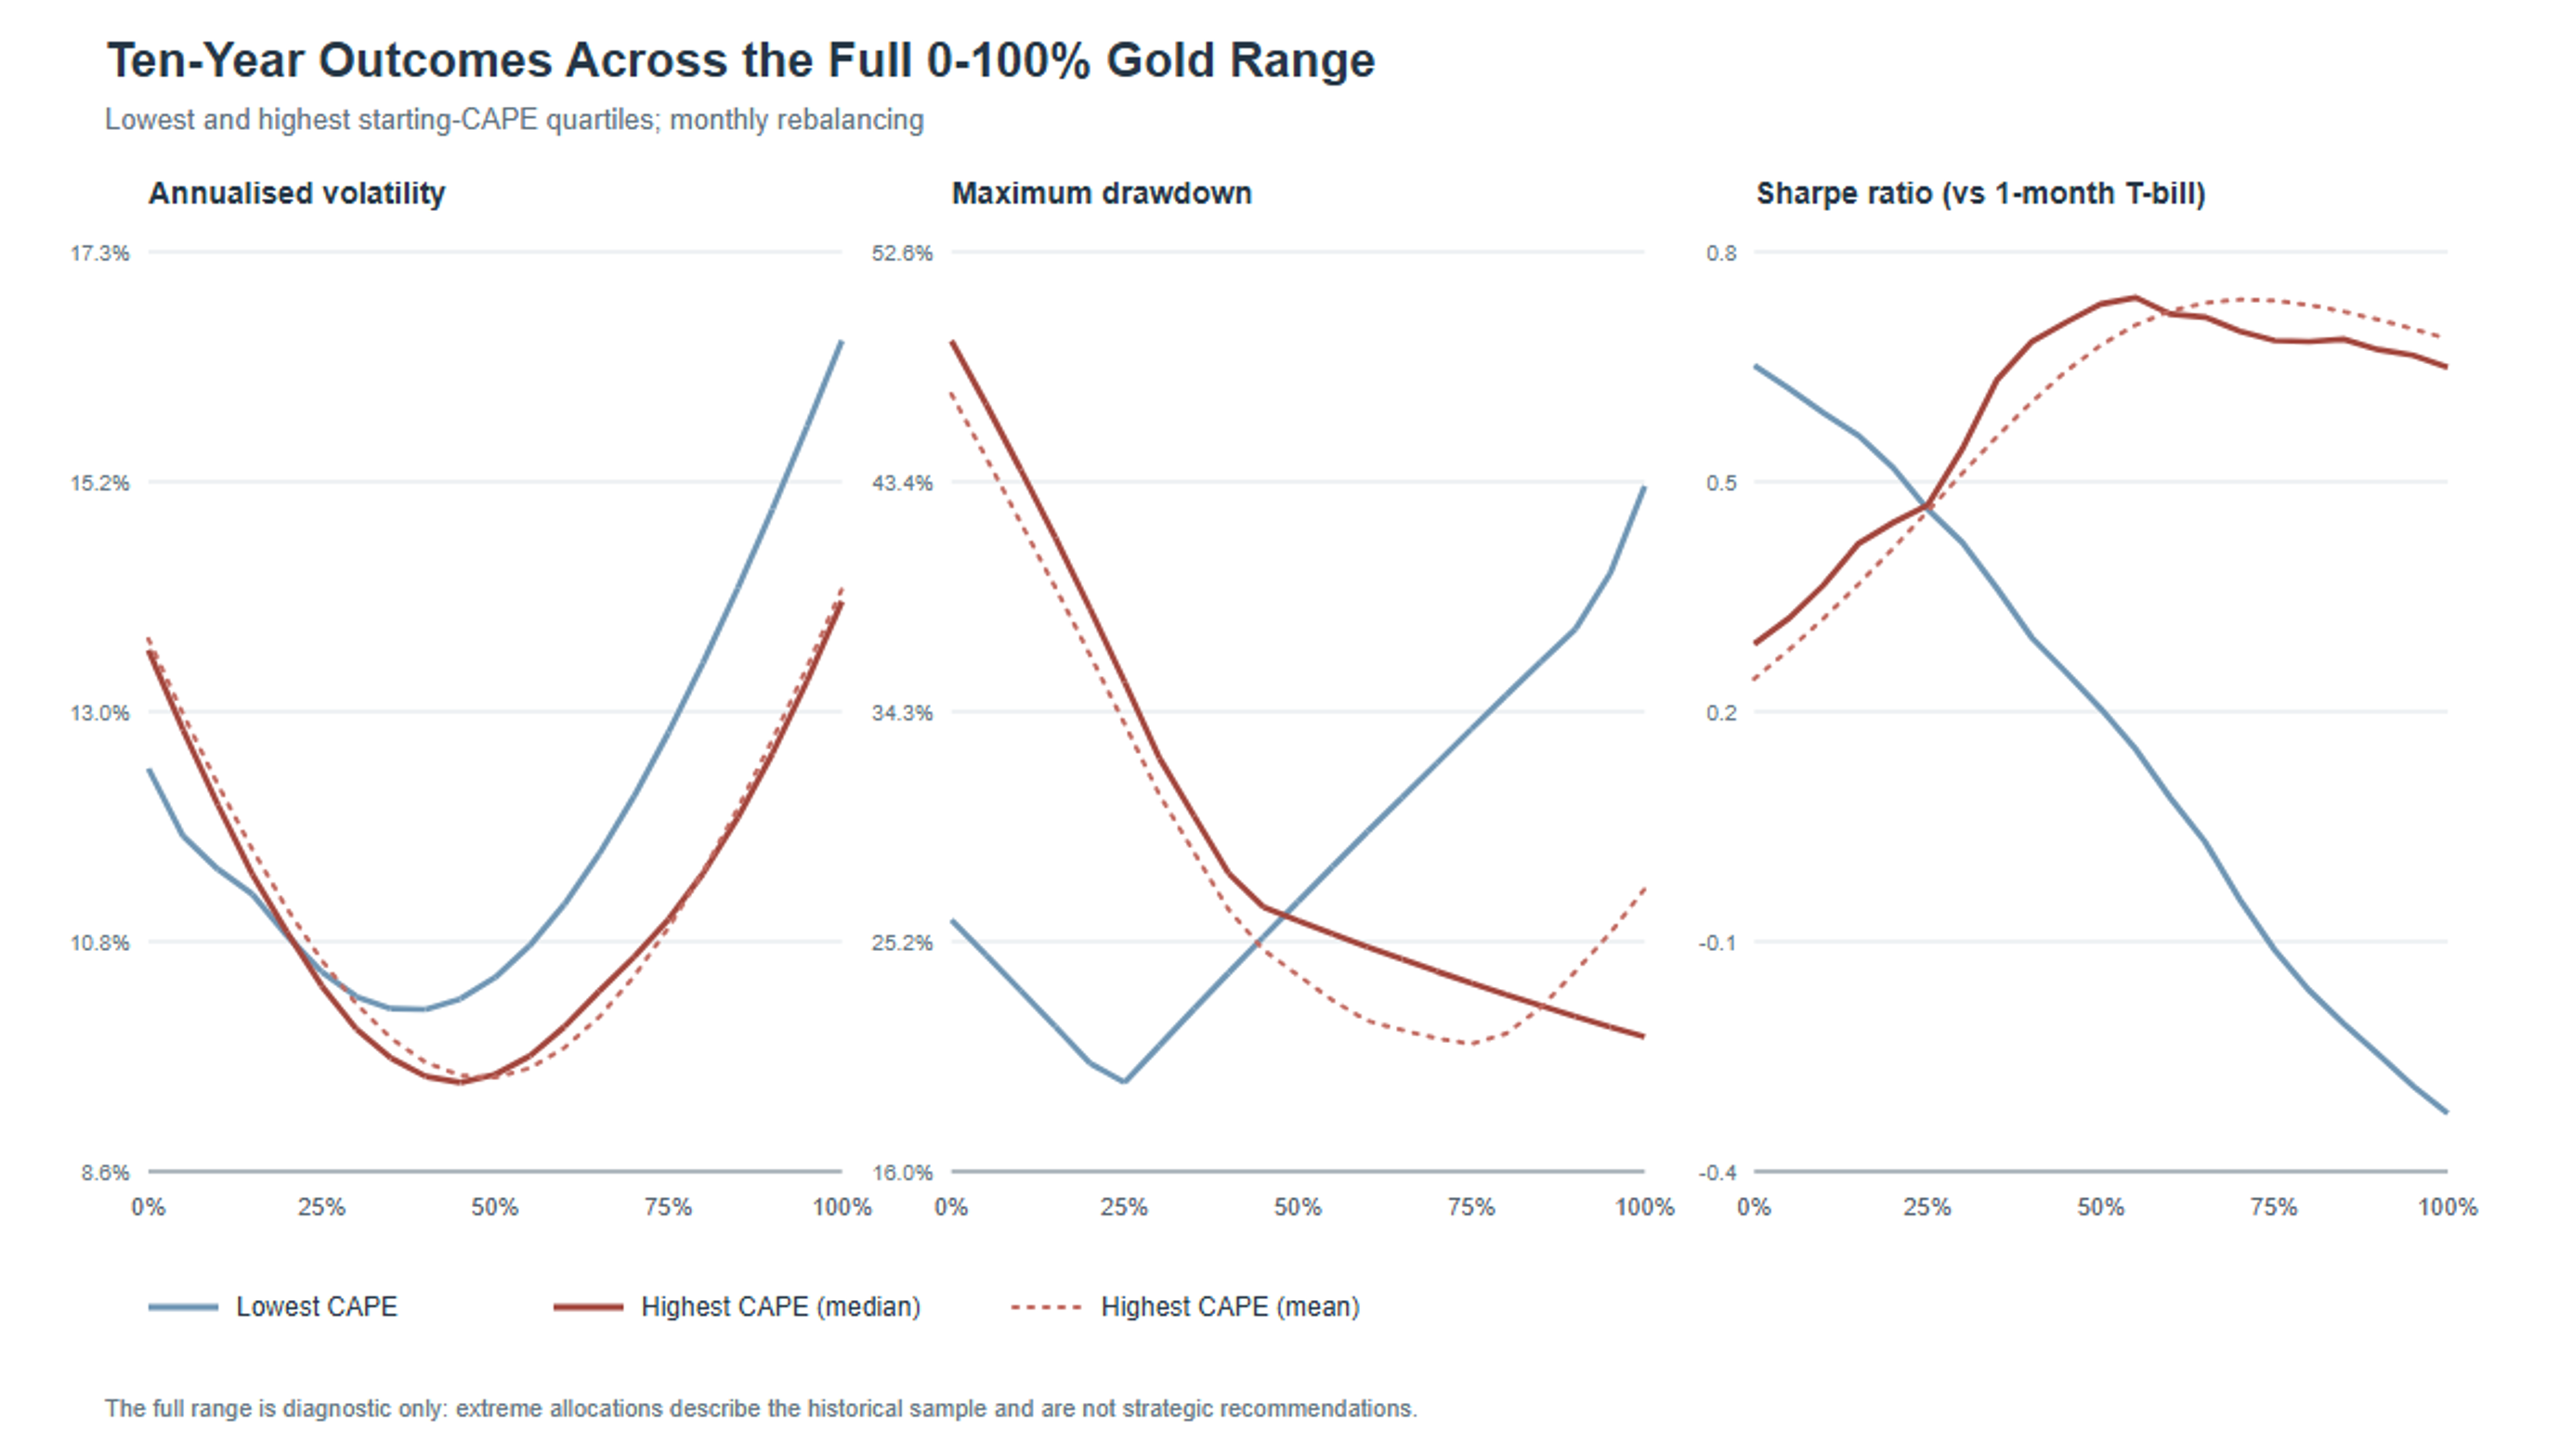
Barbarous Relic or Strategic Hedge - Gold in a late-cycle portfolio
September 1, 2026 7:00 AM UTC
* Gold worked off early year retail excess, moving into a more constructive technical and seasonal period
* The strategic case for gold is much wider: rich risk asset valuations can neither be sat out nor left unhedged
* History (no guarantee of future performance…) supports increased gold hedges in
August 28, 2026
August 20, 2026

DM Central Banks Watching Stablecoins
August 20, 2026 10:55 AM UTC
· Overall, DM central banks have a watching brief for stablecoins and the scale of growth in the next 5 years. This is largely a USD centric issue, with stablecoins dominated by USD issuance. Central banks are watchful on whether it impacts access to low cost deposit for banks; guardi
August 14, 2026
August 10, 2026
Taiwan: China Coastguard Quarantine Risks Grow
August 10, 2026 7:55 AM UTC
· Given China’s coastguard recent actions, we now raise the probability of a full quarantine of Taiwan shipping to 20% versus 10-15% in 2027/28 (Figure 2), with the probability of some further measures beyond radio requests now above 50% in 2027/28 and in our baseline. Quarantine meas
August 07, 2026
August 05, 2026
AI Equities: Correction/Consolidation?
August 5, 2026 7:40 AM UTC
• Overall, we feel that recent movements have been a correction/consolidation in the AI equity story. AI specific revenue growth still remains healthy and will support multi-year plans over cloud computing growth and in turn semiconductor demand. Even so, slowing free cash flows and ove
July 31, 2026
July 29, 2026


July 24, 2026
July 20, 2026
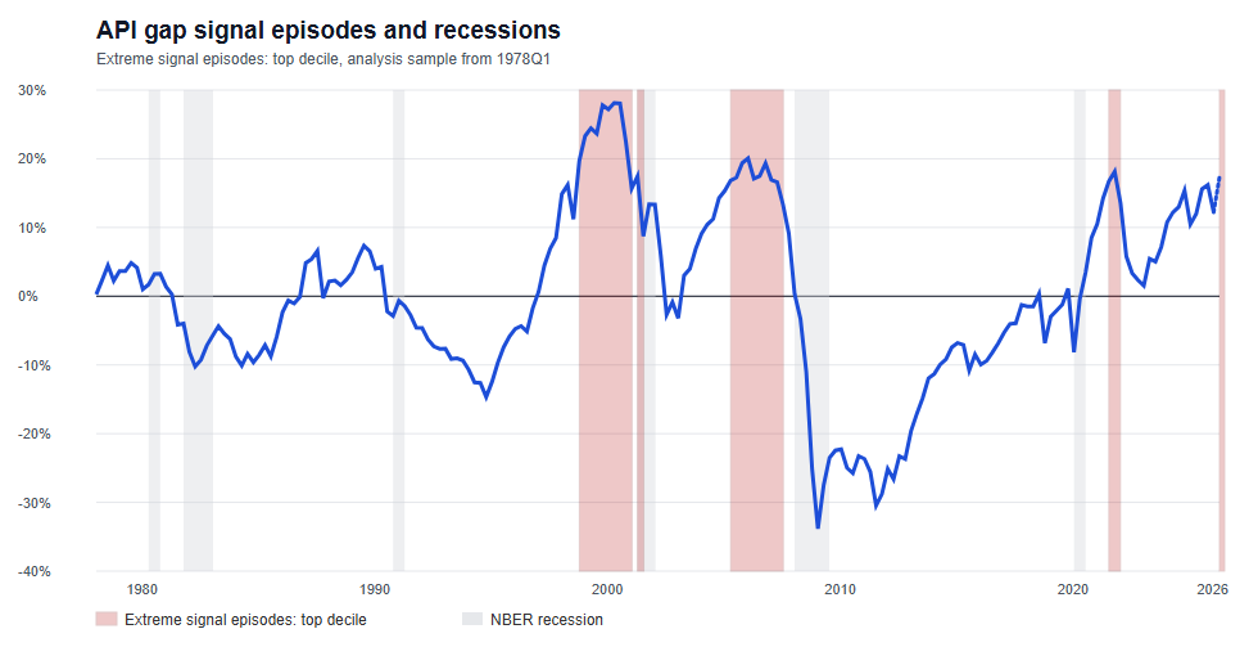
The Endpoint Problem: US Asset Prices, Investment and the Current Cycle
July 20, 2026 8:00 AM UTC
· Asset Price Index (API) framework suggests the US gap is elevated and, on some constructs, has moved into top-decile territory.
· The question is whether prices, capex and financing conditions are beginning to reinforce the same cyclical risk-accumulation dynamics.
·
July 17, 2026
Economic Data and Events Week Ahead July 20-24
July 17, 2026 3:00 PM UTC
The highlight of the week comes from the ECB meeting and press conference, although we do not expect it to provide much guidance regarding September, sticking to the non-pre-commit language, to keep options open depending on data and geopolitical developments.
The UK has its busy week, but data is
July 15, 2026
AI Optimism and Credit Markets?
July 15, 2026 8:05 AM UTC
· The AI trade in financial markets is also a question of credit markets, given the scale of financing needs is using up hyperscalers free cash flow at a rapid rate and the AI labs heavy financing requirements. Credit markets could become more sensitive, if the AI labs revenue growth sl
July 14, 2026
Iran/U.S.: A New War or Escalating to Deescalate?
July 14, 2026 10:40 AM UTC
· Our baseline remains that the MOU will hold and that the Strait of Hormuz will reopen. Iran can be pressured economically by the U.S. naval blockade being re-established. Additionally, President Trump loves to escalate to de-escalate to get a deal. This is a 60% probability scenar
July 13, 2026
Japan’s GPIF: Can it turn back the clock on the yen?
July 13, 2026 11:45 AM UTC
· The GPIF story is not that one public fund can singlehandedly ‘rescue the yen’. The question is more whether Japan can use one of the central institutions that helped drive the Abenomics flow-of-funds regime revolution to change the narrative, re-influence domestic allocation and
July 10, 2026

Economic Data and Events Week Ahead July 13-17
July 10, 2026 3:06 PM UTC
The most significant release of the week is likely to be June’s CPI on Tuesday, which we expect to be unchanged overall, but with a slightly firmer 0.3% rise ex food and energy, 0.26% before rounding. The CPI could however be overshadowed by testimony from Fed Chair Kevin Warsh to the House Financ
June 30, 2026
AI Boom and Bust?
June 30, 2026 10:45 AM UTC
• While some are becoming wary that AI bust could arrive in coming quarters, AI labs revenue growth has been explosive and this sustains the vertical chain of datacenter demand and commitments for the hyperscalers and also buoyant semiconductor demand. For 2027 and 2028 capital markets re
June 26, 2026
Economic Data and Events Week Ahead Jun 29 - Jul 3
June 26, 2026 2:45 PM UTC
The week ahead has plenty of notable events, spanning Eurozone inflation on one side, to US payrolls on the other, and with central bank speakers all round - the ECB Sintra conference at the start of the week hears from Lagarde and then a panel that includes Warsh and Bailey.
June 25, 2026
June 24, 2026
Outlook Overview: Cyclical and Structural Forces
June 24, 2026 7:00 AM UTC
· The difference between 2nd round inflation effects from higher energy prices and 1st round effects that central banks can look through swings on whether the Straits of Hormuz will remain open in the coming months after the U.S./Iran interim agreement (here). Despite some tensions, we
June 23, 2026
DM Rates Outlook: Tightening or Easing?
June 23, 2026 8:15 AM UTC
· With the U.S./Iran interim agreement likely to hold and energy prices softening, our projected consumer slowdown will likely tilt the Fed not to hike in H2 2026 and to actually ease by 50bps in 2027, with 25bps moves in both Q2 and Q3. With 2yr yields consistent with a hike, the tra
DM ex U.S. EZ Outlook (Japan and Western Europe): Navigating the Post Iran War Period?
June 23, 2026 7:43 AM UTC
· We have revised 2026 Japan GDP only slightly lower to 0.8% as wage growth is solidly above 3%, which will support consumption for the rest of 2026/27. The extension of energy stimulus will cap headline inflation for Q2/Q3 2026. For the BOJ, despite hawkish forward guidance, the 1% r
June 22, 2026
Equities Outlook: AI Optimism, But Caution Elsewhere in DM economies
June 22, 2026 7:05 AM UTC
· In terms of the S&P500, we remain less concerned about high valuations in the tech sector provided AI labs growth remains fast. 12mth fwd information technology are mid-range in the 2020-26 experience rather than at the highs. Even so, heavy equity issuance by tech companies and a s
June 17, 2026
BOJ: QT still 5-6% of GDP until 2030 at least!
June 17, 2026 6:25 AM UTC
· Though the BOJ will maintain bond buying at Yen2trn pm from April 2027, huge redemptions means that net QT will be Yen45trn April 27-March 28 i.e. around 6.5% of GDP after QT at 6% of GDP in 2026. Then JGB net reduction of Yen40trn (6% of GDP) FY 29 and Yen35trn (5.5% of GDP). Wit
June 16, 2026
June 15, 2026
U.S./Iran Interim Deal and Reopening Strait of Hormuz
June 15, 2026 12:32 PM UTC
· Our baseline (80%) is that the Strait of Hormuz will reopen in H2 2026 and remains open through 2027. However, logistics dislocation plus a switch from commercial inventory rundown to rebuilding will likely slow the decline in oil prices back towards normal levels (Figure 1). O
June 10, 2026
Financial Markets/Policymakers and the Strait of Hormuz Question
June 10, 2026 8:05 AM UTC
· Though the U.S. and Iran have attacked each other June 10, talks to reopen the straits of hormuz still continue. An Iran/U.S. agreement to reopen the Straits of Hormuz could cure the risk of a demand/supply oil market imbalance and produce some psychological relief that could knock USD
June 08, 2026
DM Government Bonds: Risks of Higher Long End Premia?
June 8, 2026 2:10 PM UTC
· Our baseline is for DM government bond yields ex Japan to remain elevated, but controlled. Japan extra risk premium is driven by BOJ QT at 6% of GDP, more than long-term debt fears. Major catalysts could drive a regime change to higher risk premia and steeper yield curves, but non
May 29, 2026
Taiwan: Low Invasion Risk Post Trump Visit
May 29, 2026 11:05 AM UTC
· The most likely option for China is to continue the air and naval grey zone warfare around Taiwan, combined with support for pro-China factions in Taiwan’s parliament to build pressure for reunification at some stage. This stick and carrot approach is our baseline (Figure 1). Wi
May 27, 2026
DM Government Bond Markets in Limbo
May 27, 2026 12:22 PM UTC
· DM central bank meetings in June will be crucial, with a high risk of a 25bps ECB hike to warn against 2nd round effects from higher oil prices and a BOJ 25bps hike as part of the ongoing normalisation. However, the tone that the Fed’s Warsh will set will also be key. The bigges
May 07, 2026
Straits of Hormuz Scenarios
May 7, 2026 6:25 AM UTC
· Our new baseline (70% probability) is for the Straits of Hormuz to start to partially reopen by June/July based on a framework deal between Iran and the U.S. This means more elevated oil prices in Q2, but then a gradual reduction in WTI to USD85 end-2026 and USD75 end 2027. The al
April 29, 2026
April 28, 2026
April 27, 2026
Straits of Hormuz Standoff and Mixed Markets
April 27, 2026 9:02 AM UTC
• Equities longer time horizon means that they are hoping for a reopening of the Straits of Hormuz (though also being helped by renewed AI optimism), whereas government bond markets actually want to see tangible progress and an associated tempering of DM central banks posturing. This dive