United States
View:
October 12, 2026
October 09, 2026
AI and The U.S. Economy
October 9, 2026 8:15 AM UTC
· The AI boom is boosting the U.S. economy through three channels (semiconductor and other product enablers for AI; the data center construction boom and wealth effects boosting consumption for rich households). If AI labs revenue growth remains fast then the boom can continue through
October 08, 2026
October 07, 2026
FOMC Minutes: Hawkish but no clear signal on October

October 7, 2026 6:41 PM UTC
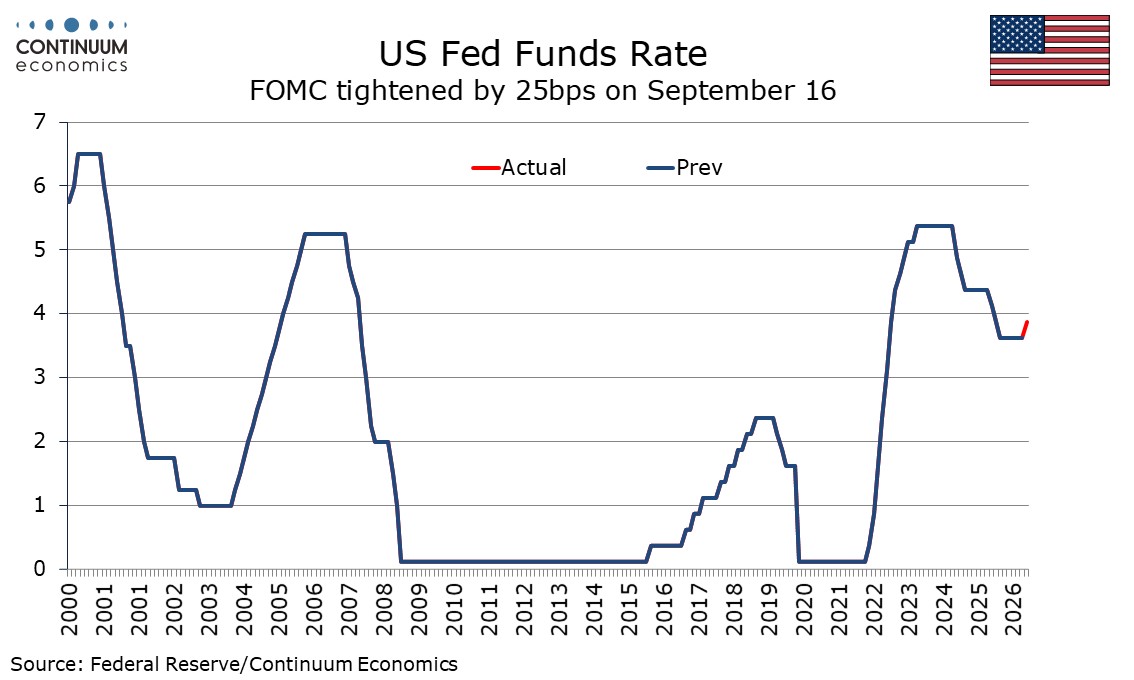
FOMC minutes from the September 15-16 meeting show unanimous support for the 25bps tightening that was delivered with increased upside risks to inflation and balanced risk to employment seen. Most participants stressed that another tightening would be likely be appropriate before year end but they e
FOMC Minutes: Hawkish but no clear signal on October
October 7, 2026 6:40 PM UTC
FOMC minutes from the September 15-16 meeting show unanimous support for the 25bps tightening that was delivered with increased upside risks to inflation and balanced risk to employment seen. Most participants stressed that another tightening would be likely be appropriate before year end but they e
New York Fed survey shows near term U.S. inflation expectations higher in September, but stable on a 5-year view
October 7, 2026 3:24 PM UTC
The New York Fed’s inflation expectations survey still shows the 5-year view stable at 3.0%, despite the 1-year view accelerating to 3.9% from 3.6%, reaching its highest since June 2023.
DM Yield Curves and 2yr to Policy Rate Spreads
October 7, 2026 9:45 AM UTC
· The scale of the September yield rise was driven mainly policy rate tightening ideas and an extra real yield premium. However, the rise in bond volatility, plus the role of speculative funds appears to have amplified the move. Moderate or major bond positive news could see a parti
October 06, 2026
Despite tariffs, US trade deficits increasing and Canadian trade surpluses increasing
October 6, 2026 1:16 PM UTC
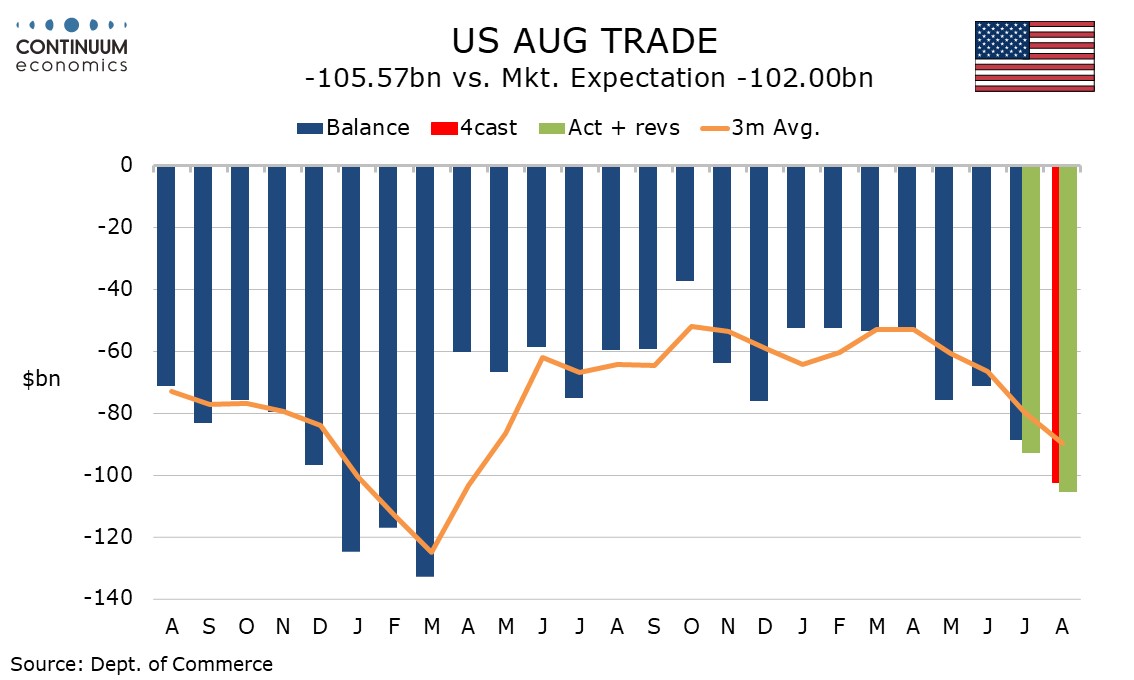
A wider than expected August US trade deficit of $105.6bn from $92.8bn contrasts with a wider than expected August Canadian trade surplus of C$4.2bn versus C$0.79bn in July. The US deficit is the largest since the pre-tariff record of $133.0bn in March 2025. Canada’s August surplus is the widest s
Despite tariffs, US trade deficits increasing and Canadian trade surpluses increasing
October 6, 2026 1:15 PM UTC
A wider than expected August US trade deficit of $105.6bn from $92.8bn contrasts with a wider than expected August Canadian trade surplus of C$4.2bn versus C$0.79bn in July. The US deficit is the largest since the pre-tariff record of $133.0bn in March 2025. Canada’s August surplus is the widest s
Preview: Due October 15 - U.S. September Retail Sales - Subdued end to a respectable Q3
October 6, 2026 11:43 AM UTC
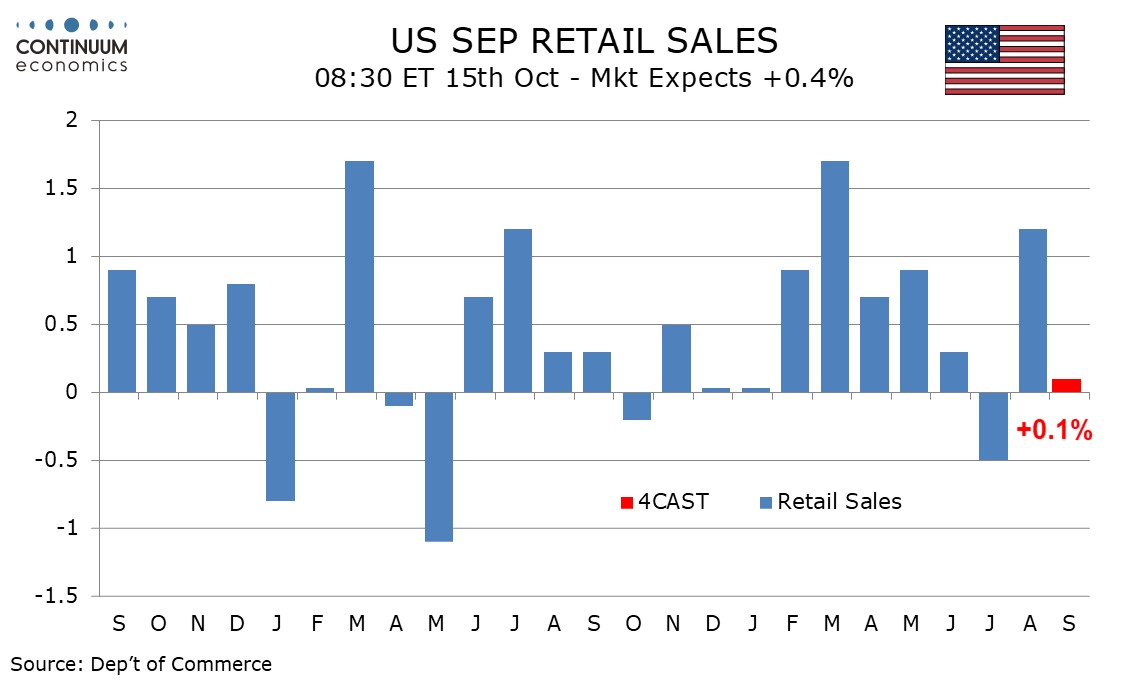
We expect September sales to rise by 0.1% overall and by 0.4% ex autos. However the gains will come fully from price-induced gains in gasoline. We expect sales to fall by 0.1% ex autos and gasoline and by 0.3% ex gasoline.
Preview: Due October 15 - U.S. September Retail Sales - Subdued end to a respectable Q3
October 6, 2026 11:41 AM UTC
We expect September sales to rise by 0.1% overall and by 0.4% ex autos. However the gains will come fully from price-induced gains in gasoline. We expect sales to fall by 0.1% ex autos and gasoline and by 0.3% ex gasoline.
October 02, 2026
U.S. September Employment - Trend looking subdued again
October 2, 2026 1:12 PM UTC
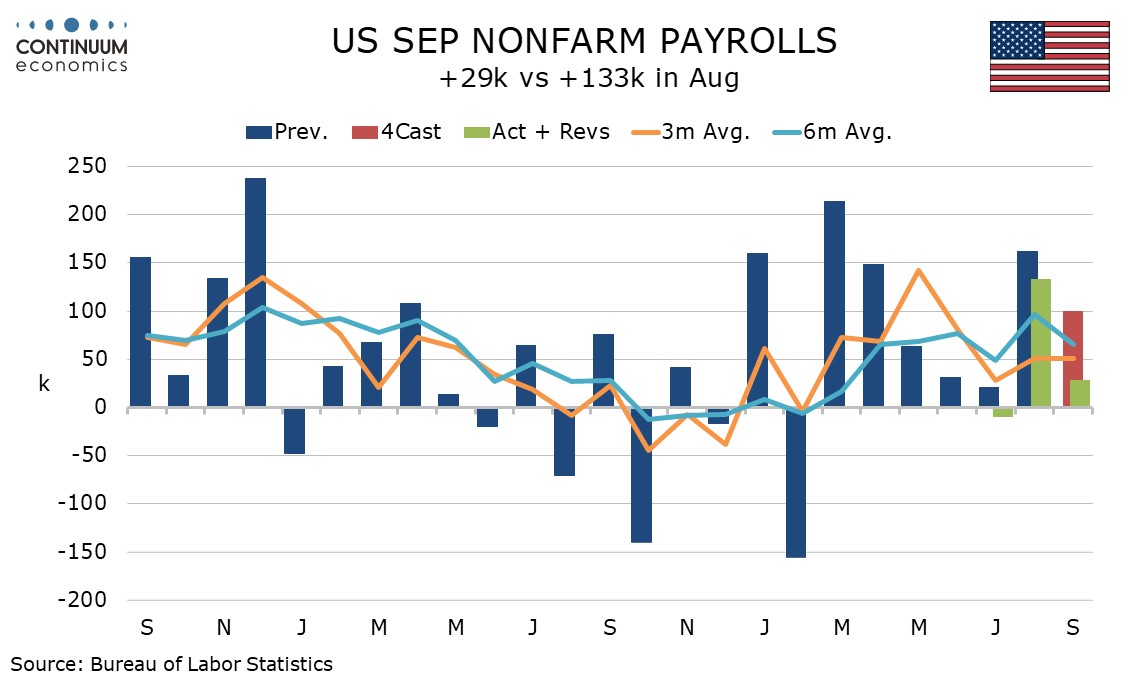
September’s non-farm payroll at 23k, 46k private, with negative back revisions, is weaker than expected and returns the picture to near flat after the stronger August. Average hourly earnings are slowing, up only 0.1%, though the rise in unemployment to 4.2% from 4.1% is on a rise in the labor for
U.S. September Employment - Trend looking subdued again
October 2, 2026 1:12 PM UTC
September’s non-farm payroll at 23k, 46k private, with negative back revisions, is weaker than expected and returns the picture to near flat after the stronger August. Average hourly earnings are slowing, up only 0.1%, though the rise in unemployment to 4.2% from 4.1% is on a rise in the labor for
October 01, 2026
Preview: Due October 15 - U.S. September PPI - Inflationary pressure still significant
October 1, 2026 4:52 PM UTC
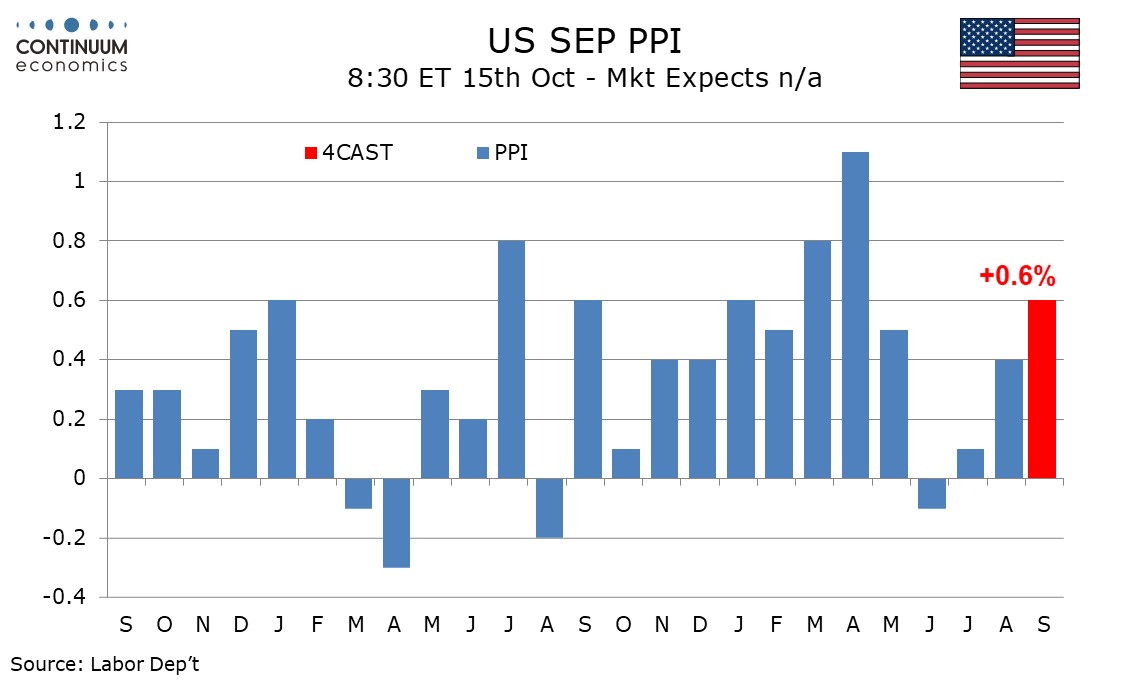
We expect September PPI to increase by 0.6% overall led by energy with 0.3% gains in both core rates, ex food and energy and ex food, energy and trade. This will suggest inflationary pressures remain elevated, with little sign of slowing at the producer level.
Preview: Due October 15 - U.S. September PPI - Inflationary pressure still significant
October 1, 2026 4:52 PM UTC
We expect September PPI to increase by 0.6% overall led by energy with 0.3% gains in both core rates, ex food and energy and ex food, energy and trade. This will suggest inflationary pressures remain elevated, with little sign of slowing at the producer level.
Preview: Due October 2 - U.S. September Employment (Non-Farm Payrolls) - Healthy if less strong than August
October 1, 2026 1:06 PM UTC
We expect September’s non-farm payroll to rise by 100k both overall and in the private sector, slower than in August but still implying a healthy trend. We expect a 4.1% unemployment rate for a third straight month but a slightly slower 0.2% rise in average hourly earnings and a stable workweek. O
September 30, 2026
Preview: Due October 12 - U.S. September Existing Home Sales - Marginal correction higher, but trend is falling
September 30, 2026 7:27 PM UTC
We see scope for a marginal upward correction in September existing home sales, by 0.5% to 4.00m after three straight declines. However rising mortgage rates and Fed tightening are likely to bring renewed slippage in Q4.
U.S. Trimmed Mean and Median PCE Price Indices slower in August
September 30, 2026 5:22 PM UTC
The Dallas Fed’s Trimmed Mean PCE price index at 1.92% annualized in August is similar to July’s and the third straight month below 2.0%. Yr/yr growth of 2.19% is down from 2.28% in both June and July and the slowest since August 2021.
U.S. GDP, Income, Spending and PCE Price revisions mostly encouraging, but Trade Deficit is rising
September 30, 2026 1:51 PM UTC
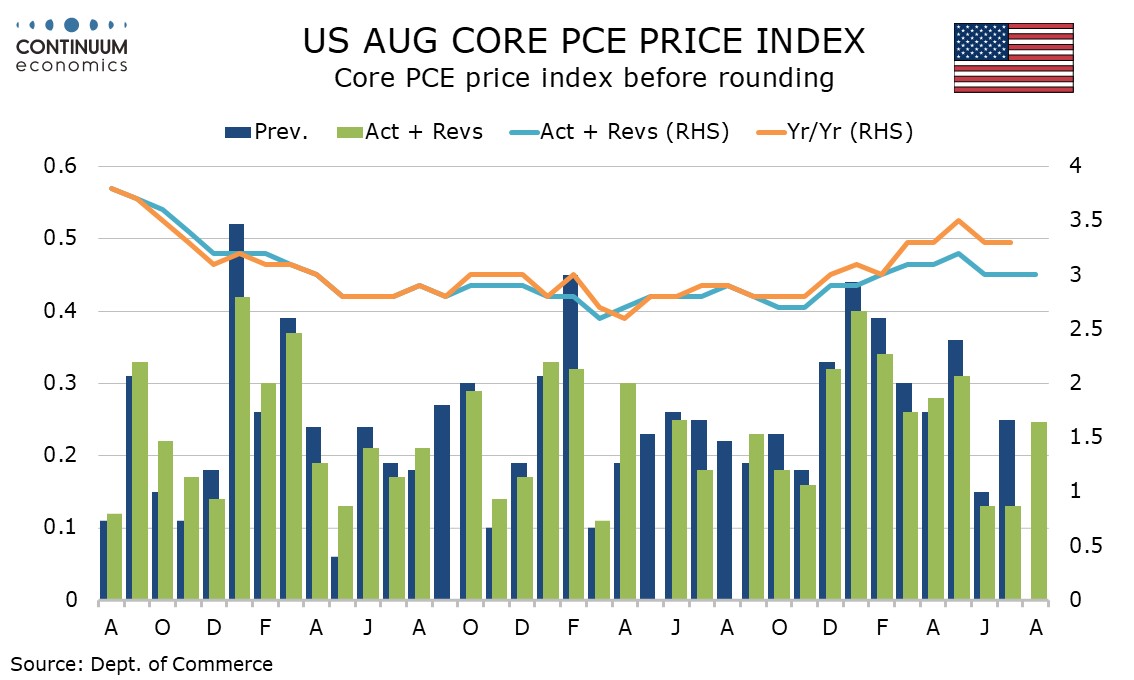
The final Q2 GDP report and August’s personal income and spending data are notable for historical revisions going back to 2021. The news in the revisions is generally encouraging, with upward revisions to GDP and real disposable income but downward revisions to PCE prices, led by non-market prices
U.S. GDP, Income, Spending and PCE Price revisions mostly encouraging, but Trade Deficit is rising
September 30, 2026 1:51 PM UTC
The final Q2 GDP report and August’s personal income and spending data are notable for historical revisions going back to 2021. The news in the revisions is generally encouraging, with upward revisions to GDP and real disposable income but downward revisions to PCE prices, led by non-market prices
September 29, 2026
Preview: Due October 14 - U.S. September CPI - Stronger, but with a slower core rate
September 29, 2026 6:03 PM UTC
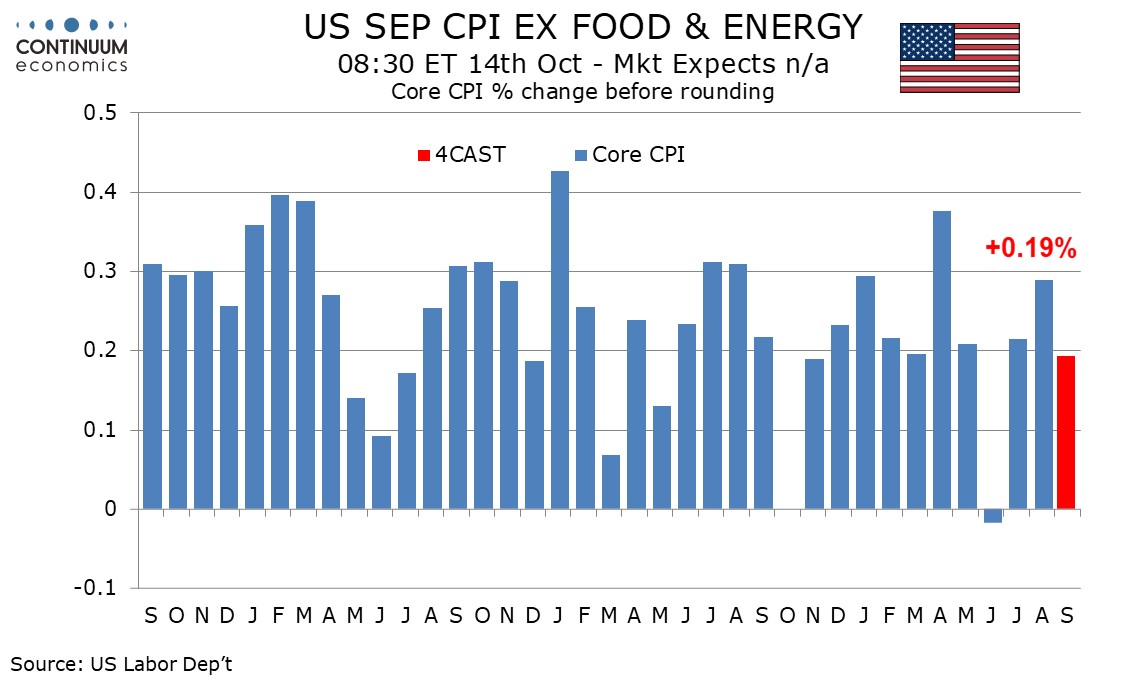
We expect a stronger rise of 0.6% in overall CPI in September, but a moderate 0.2% increase ex food and energy. Before rounding we expect the respective gains to be 0.57% and 0.19%. The latter would be a significant slowing from August’s 0.29%, but the former would be the strongest since April.
Preview: Due October 14 - U.S. September CPI - Stronger, but with a slower core rate
September 29, 2026 6:02 PM UTC
We expect a stronger rise of 0.6% in overall CPI in September, but a moderate 0.2% increase ex food and energy. Before rounding we expect the respective gains to be 0.57% and 0.19%. The latter would be a significant slowing from August’s 0.29%, but the former would be the strongest since April.
The 18yr Housing Cycle: Bent, Broken, or Still on Track
September 29, 2026 2:21 PM UTC
* Housing has reached the end of its classic 18yr cycle. Did Covid bring the peak, and part of the bust, forward? Or merely muddy a cycle that is still running into familiar inflation-rates pressure and financial cycle dangers on cue?
* Performances vary globally. Resilient cash prices disguise a rea
Preview: Due September 30 - U.S. August Personal Income and Spending - PCE prices to match CPI, watch for revisions
September 29, 2026 12:20 PM UTC
We expect August PCE price data to match the July CPI, rising by 0.4% overall and 0.3% ex food and energy. We expect a 0.5% increase in personal income, and a strong 0.9% increase in personal spending. The data should be watched not only for August changes, but also for historical revisions going ba
September 28, 2026
FOMC Minutes Preview: Likely to be hawkish, but October decision still data-dependent
September 28, 2026 4:37 PM UTC
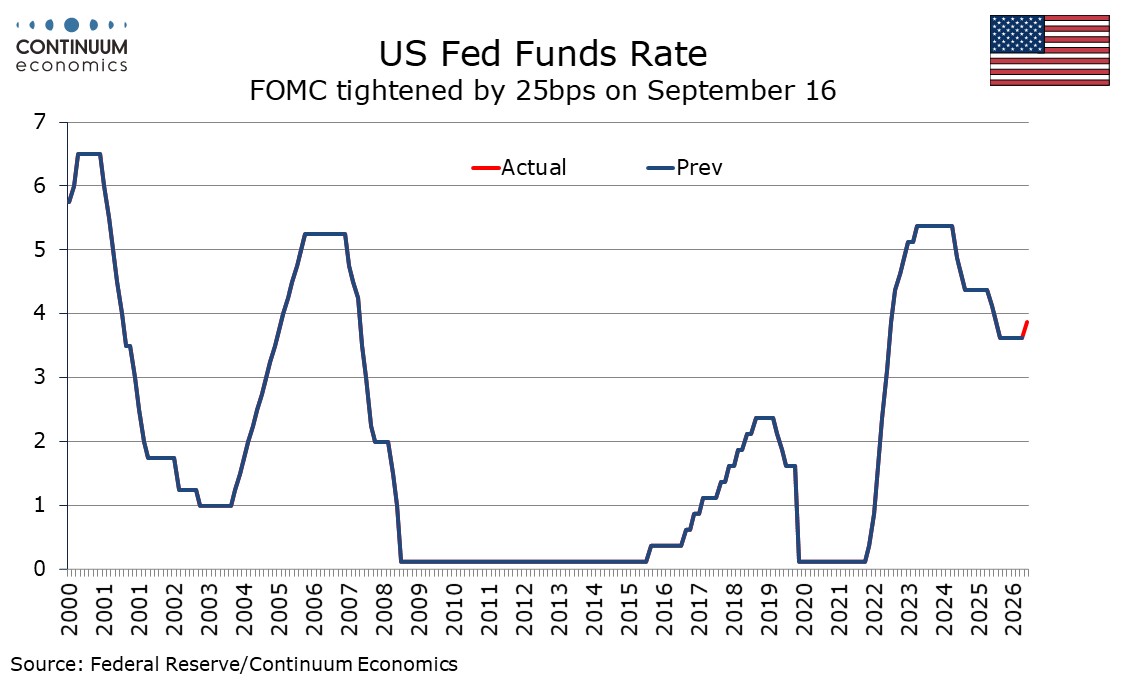
The public comments of Fed speakers since the September 16 meeting delivered a unanimous vote to tighten suggest that the minutes of that meeting, due on October 7, will have a hawkish tone. Recent hawkish Fed talk reduces the risk that the proximity of the midterm elections will prevent a tightenin
FOMC Minutes Preview: Likely to be hawkish, but October decision still data-dependent
September 28, 2026 4:36 PM UTC
The public comments of Fed speakers since the September 16 meeting delivered a unanimous vote to tighten suggest that the minutes of that meeting, due on October 7, will have a hawkish tone. Recent hawkish Fed talk reduces the risk that the proximity of the midterm elections will prevent a tightenin
September 25, 2026
U.S. July Durable Goods Orders - Some loss of momentum in Q3 to date
September 25, 2026 12:53 PM UTC
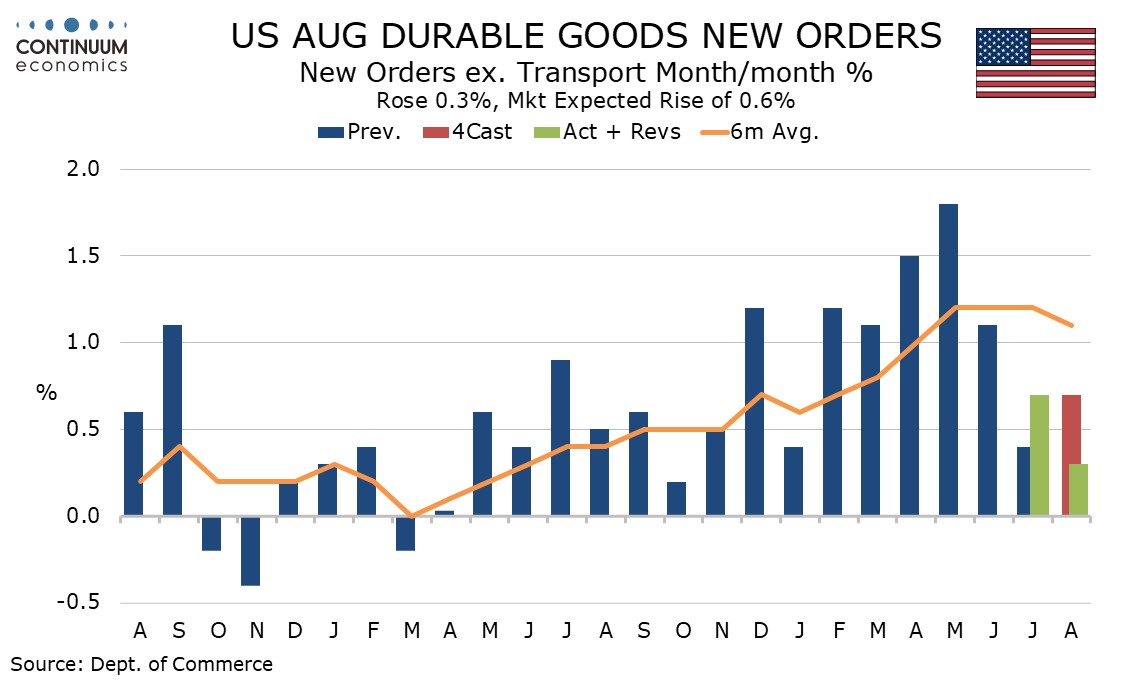
August durable goods orders are unchanged, a little stronger than expected overall, but the ex transport gain of 0.3% is weaker than expected and even with July revised up to 0.7% from 0.4% Q3 data to data has been slower than Q2’s.
September 24, 2026
September 23, 2026
Outlook Overview: Navigation Into 2027
September 23, 2026 2:30 PM UTC
· The hot phase of the Iran war is over, but the intermittent conflict between the U.S. and Iran is stopping shipping via the Straits of Hormuz from fully recovering and keeping energy prices elevated. Some DM and EM central banks are guarding against 2nd round effects with modest tig
DM Rates Outlook: Long-term challenges, but selective short-term value
September 23, 2026 6:15 AM UTC
*Overweight gilts for 2027, focusing on intermediates. Large ‘policy uncertainty’ premium offers value on any less adverse Middle East scenario.
* Treasuries may offer tactical opportunity into weakness over Q4 2026-Q1 2027, with US10s projected back towards 4½% in respite. Longer term issues re
September 22, 2026
U.S. Outlook: Growth Overly Dependent on AI
September 22, 2026 1:34 PM UTC
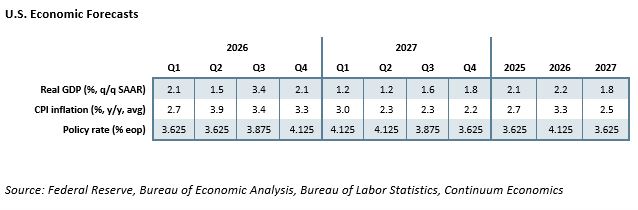
• The US economy is currently showing signs of acceleration with business investment strong led by AI and consumer spending outperforming real disposable income, in part because of AI-assisted strength in equities. We expect continued strength in business investment though a modest slowing
September 21, 2026
Preview: Due October 2 - U.S. September Employment (Non-Farm Payrolls) - Healthy if less strong than August
September 21, 2026 6:29 PM UTC
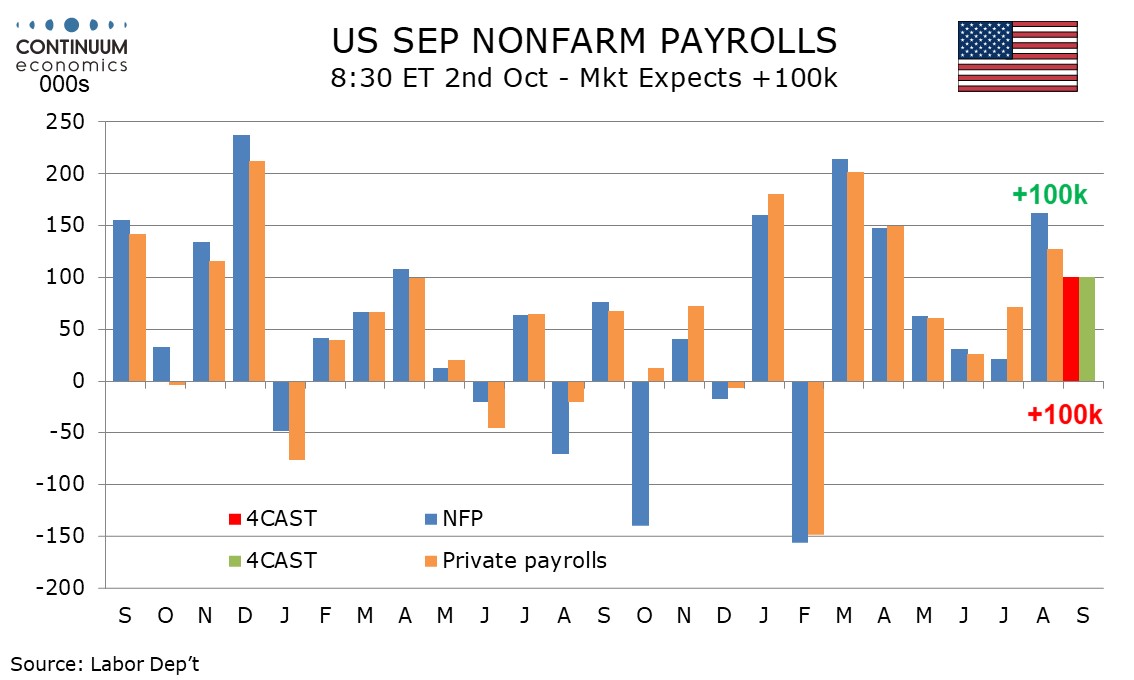
We expect September’s non-farm payroll to rise by 100k both overall and in the private sector, slower than in August but still maintaining a healthy trend. We expect a 4.1% unemployment rate for a third straight month but a slightly slower 0.2% rise in average hourly earnings and a stable workweek
Preview: Due October 2 - U.S. September Employment (Non-Farm Payrolls) - Healthy if less strong than August
September 21, 2026 6:28 PM UTC
We expect September’s non-farm payroll to rise by 100k both overall and in the private sector, slower than in August but still maintaining a healthy trend. We expect a 4.1% unemployment rate for a third straight month but a slightly slower 0.2% rise in average hourly earnings and a stable workweek
September 18, 2026
Preview: Due September 30 - U.S. August Personal Income and Spending - PCE prices to match CPI, watch for revisions
September 18, 2026 5:26 PM UTC
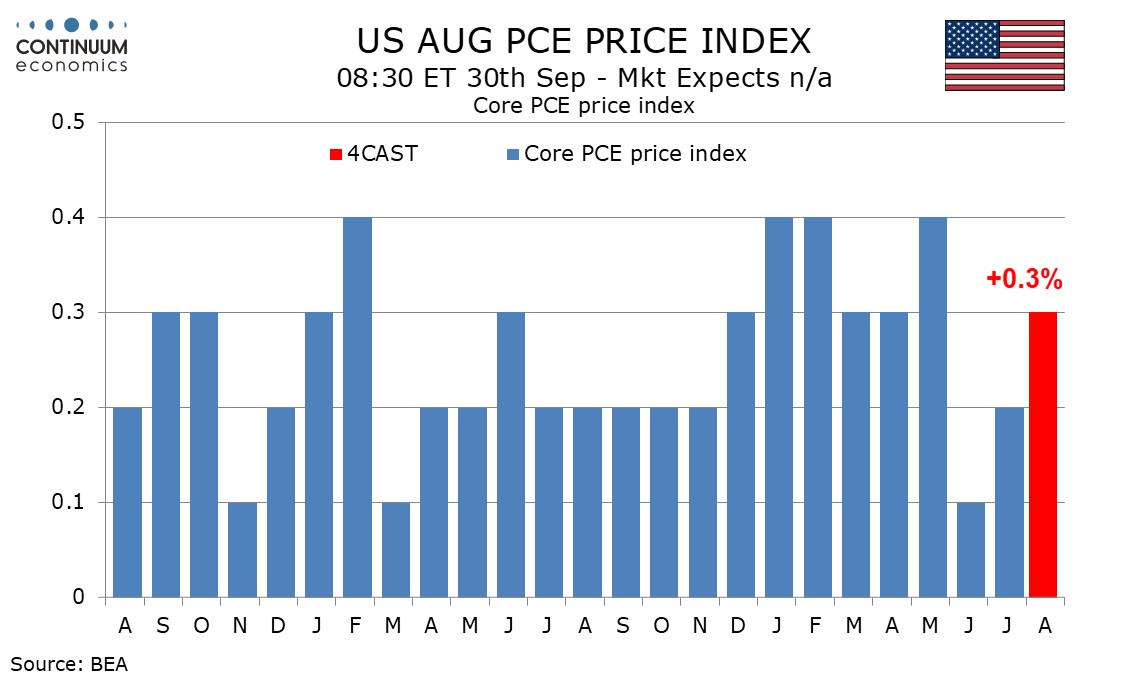
We expect August PCE price data to match the July CPI, rising by 0.4% overall and 0.3% ex food and energy. We expect a 0.5% increase in personal income, and a strong 0.9% increase in personal spending. The data should be watched not only for August changes, but also for historical revisions going ba
Preview: Due September 30 - U.S. August Personal Income and Spending - PCE prices to match CPI, watch for revisions
September 18, 2026 5:25 PM UTC
We expect August PCE price data to match the July CPI, rising by 0.4% overall and 0.3% ex food and energy. We expect a 0.5% increase in personal income, and a strong 0.9% increase in personal spending. The data should be watched not only for August changes, but also for historical revisions going ba
U.S. August Industrial Production - Surprising dip in manufacturing
September 18, 2026 1:46 PM UTC
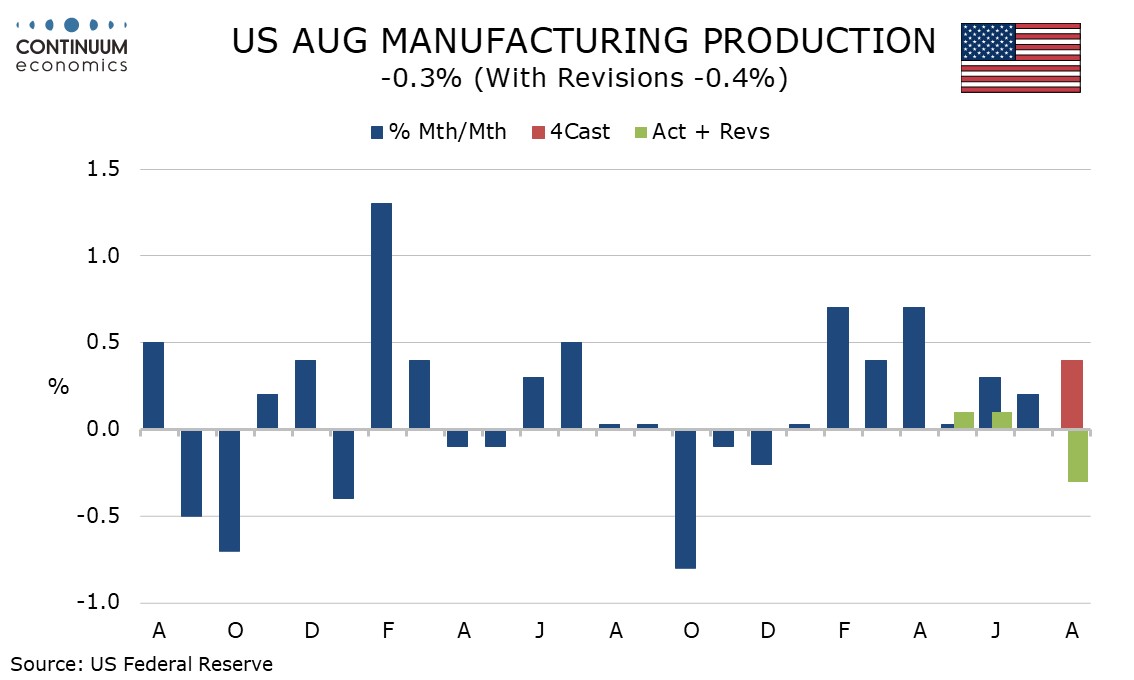
August industrial production was unchanged with a very surprising 0.3% decline in manufacturing, its first decline since three straight declines were seen in Q4 of 2025. While one month does not make a trend the manufacturing losses were broad based and thus not easy to dismiss.