Federal Reserve
View:
October 02, 2026
U.S. September Employment - Trend looking subdued again

October 2, 2026 1:12 PM UTC
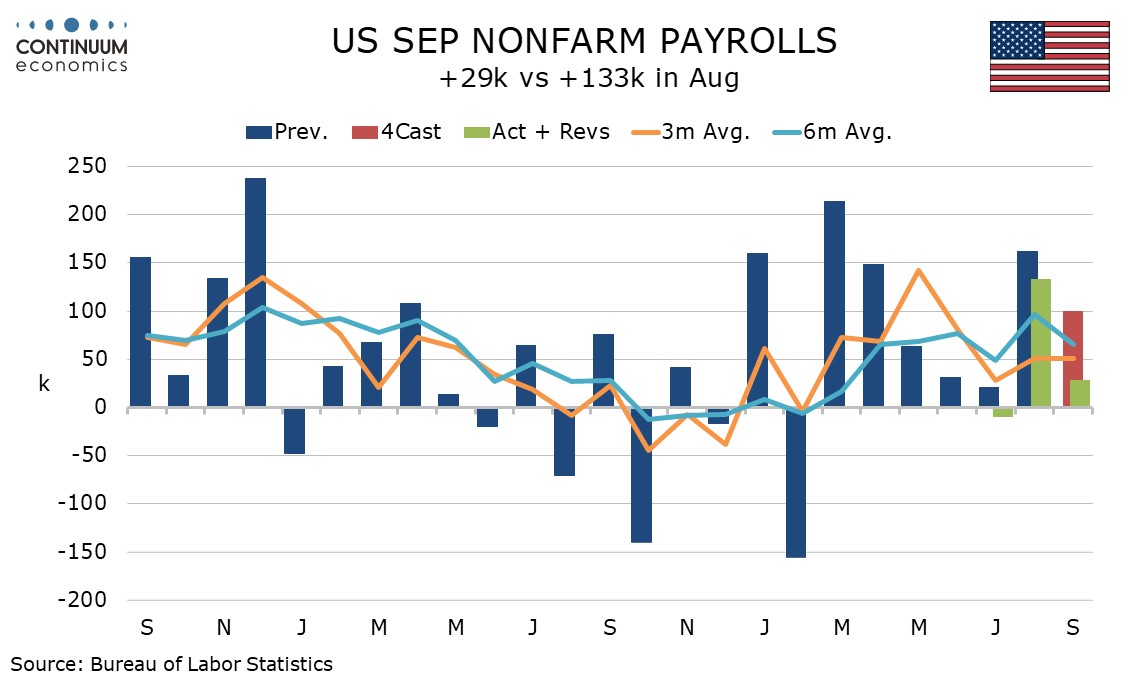
September’s non-farm payroll at 23k, 46k private, with negative back revisions, is weaker than expected and returns the picture to near flat after the stronger August. Average hourly earnings are slowing, up only 0.1%, though the rise in unemployment to 4.2% from 4.1% is on a rise in the labor for
U.S. September Employment - Trend looking subdued again
October 2, 2026 1:12 PM UTC
September’s non-farm payroll at 23k, 46k private, with negative back revisions, is weaker than expected and returns the picture to near flat after the stronger August. Average hourly earnings are slowing, up only 0.1%, though the rise in unemployment to 4.2% from 4.1% is on a rise in the labor for
October 01, 2026
September 30, 2026
U.S. Trimmed Mean and Median PCE Price Indices slower in August
September 30, 2026 5:22 PM UTC
The Dallas Fed’s Trimmed Mean PCE price index at 1.92% annualized in August is similar to July’s and the third straight month below 2.0%. Yr/yr growth of 2.19% is down from 2.28% in both June and July and the slowest since August 2021.
September 29, 2026
September 28, 2026
FOMC Minutes Preview: Likely to be hawkish, but October decision still data-dependent
September 28, 2026 4:37 PM UTC
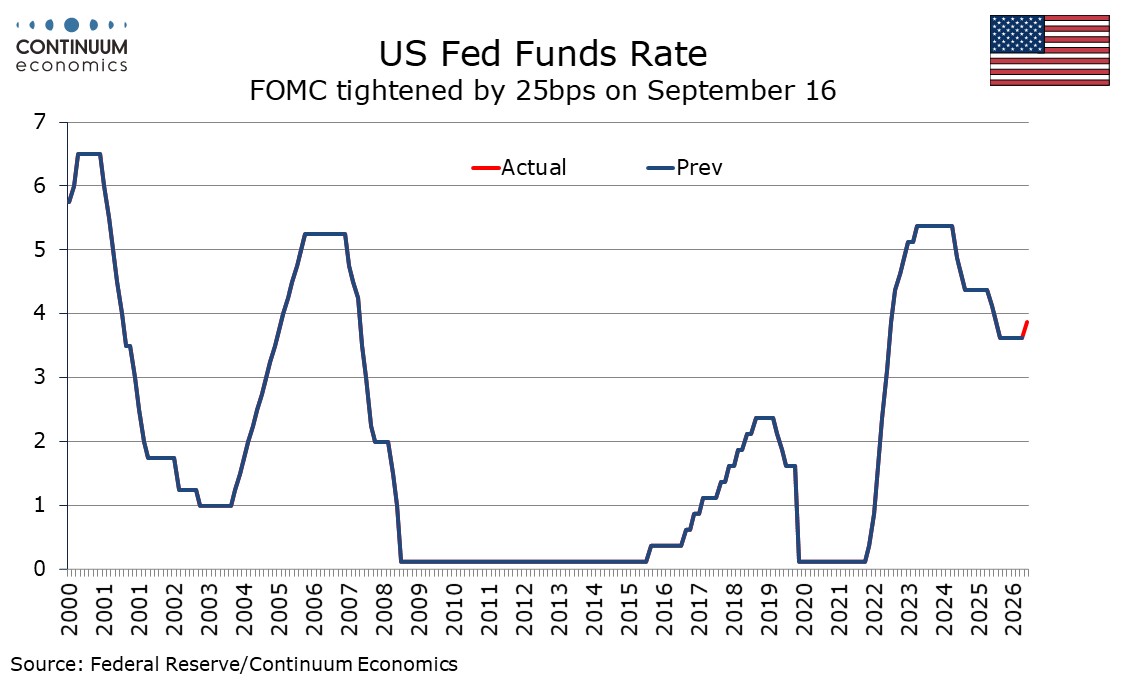
The public comments of Fed speakers since the September 16 meeting delivered a unanimous vote to tighten suggest that the minutes of that meeting, due on October 7, will have a hawkish tone. Recent hawkish Fed talk reduces the risk that the proximity of the midterm elections will prevent a tightenin
FOMC Minutes Preview: Likely to be hawkish, but October decision still data-dependent
September 28, 2026 4:36 PM UTC
The public comments of Fed speakers since the September 16 meeting delivered a unanimous vote to tighten suggest that the minutes of that meeting, due on October 7, will have a hawkish tone. Recent hawkish Fed talk reduces the risk that the proximity of the midterm elections will prevent a tightenin
September 24, 2026
September 23, 2026
DM Rates Outlook: Long-term challenges, but selective short-term value
September 23, 2026 6:15 AM UTC
*Overweight gilts for 2027, focusing on intermediates. Large ‘policy uncertainty’ premium offers value on any less adverse Middle East scenario.
* Treasuries may offer tactical opportunity into weakness over Q4 2026-Q1 2027, with US10s projected back towards 4½% in respite. Longer term issues re
September 22, 2026
U.S. Outlook: Growth Overly Dependent on AI
September 22, 2026 1:34 PM UTC
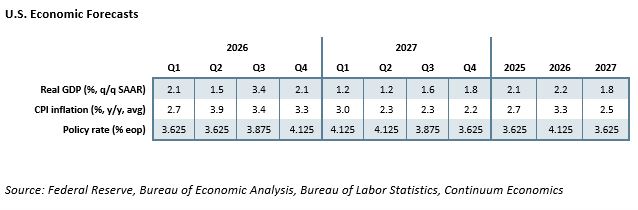
• The US economy is currently showing signs of acceleration with business investment strong led by AI and consumer spending outperforming real disposable income, in part because of AI-assisted strength in equities. We expect continued strength in business investment though a modest slowing
September 16, 2026
FOMC - Further tightening likely if data holds up
September 16, 2026 7:48 PM UTC
The Fed’s 25bps tightening was as we expected but a lack of any dovish dissenting votes was not. The Fed’s dots were more hawkish than we expected. While we have a somewhat more dovish view of the economy that the Fed, we have updated our Fed forecast, now expecting one more move this year, in D
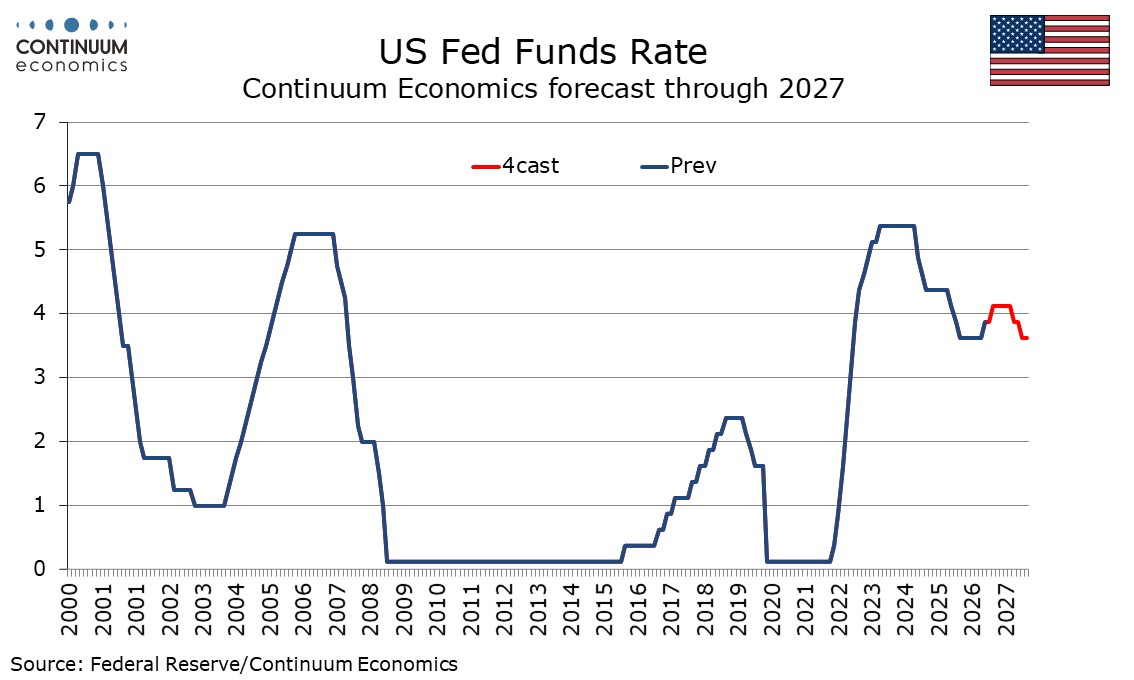
FOMC - Further tightening likely if data holds up
September 16, 2026 7:47 PM UTC
The Fed’s 25bps tightening was as we expected but a lack of any dovish dissenting votes was not. The Fed’s dots were more hawkish than we expected. While we have a somewhat more dovish view of the economy that the Fed, we have updated our Fed forecast, now expecting one more move this year, in D
EM Money Supply: Trends Diverge from Policy Rates

September 16, 2026 11:15 AM UTC
· M2 growth in China remains weak (pre 2015 the trend had been double digit), despite the low level of nominal and real policy rates. This reflects credit demand and supply problems. M2 growth will likely remain restrained by Chinese standards and act as a drag of nominal and real GDP
September 15, 2026
Back at 5%: Unpacking the US Treasury selloff
September 15, 2026 2:55 PM UTC
* USTs revisit the big psychological level after big selloff
* Sep move has been mainly policy led, with the curve responding
* Longer term trend has been a real risk premium story – with real rates backup led by additional risk/compensation/reduced scarcity effects. Breakeven inflation expectatio
September 11, 2026
FOMC Preview for September 16: Recent data back Warsh tightening hints
September 11, 2026 2:36 PM UTC
The FOMC meets on September 16 and after some recent firm data, particularly August’s core CPI, a 25bps tightening to a 3.75% - 4.0% Fed Funds target range now looks likely. However, the CPI upside surprise came in only a few components and some dovish dissents are still possible, though Chairman
U.S. August CPI - Telephone services, air fares and hotels lift the core rate
September 11, 2026 1:08 PM UTC
August CPI is not a shocker at 0.4% overall, but the core rate of 0.3% ex food and energy is above expectations and where the Fed would like it to be and suggests tightening on September 16 is now likely. Before rounding core CPI rose by 0.29% and overall CPI by 0.396%. Telephone services are the ma

U.S. August CPI - Telephone services, air fares and hotels lift the core rate
September 11, 2026 1:07 PM UTC
August CPI is not a shocker at 0.4% overall, but the core rate of 0.3% ex food and energy is above expectations and where the Fed would like it to be and suggests tightening on September 16 is now likely. Before rounding core CPI rose by 0.29% and overall CPI by 0.396%. Telephone services are the ma

QT: BOE Slowdown But Not BOJ/ECB Yet
September 11, 2026 11:50 AM UTC
· The BOE will likely slow the pace of QT to GBP50bln pa at the September 17 MPC meeting, but the BOJ/ECB have no current plans to slow QT. The BOJ QT at 6% of GDP is huge and pushing up JGB yields and the BOJ could slow the pace over the winter into the spring once the next 25bps pol
September 08, 2026
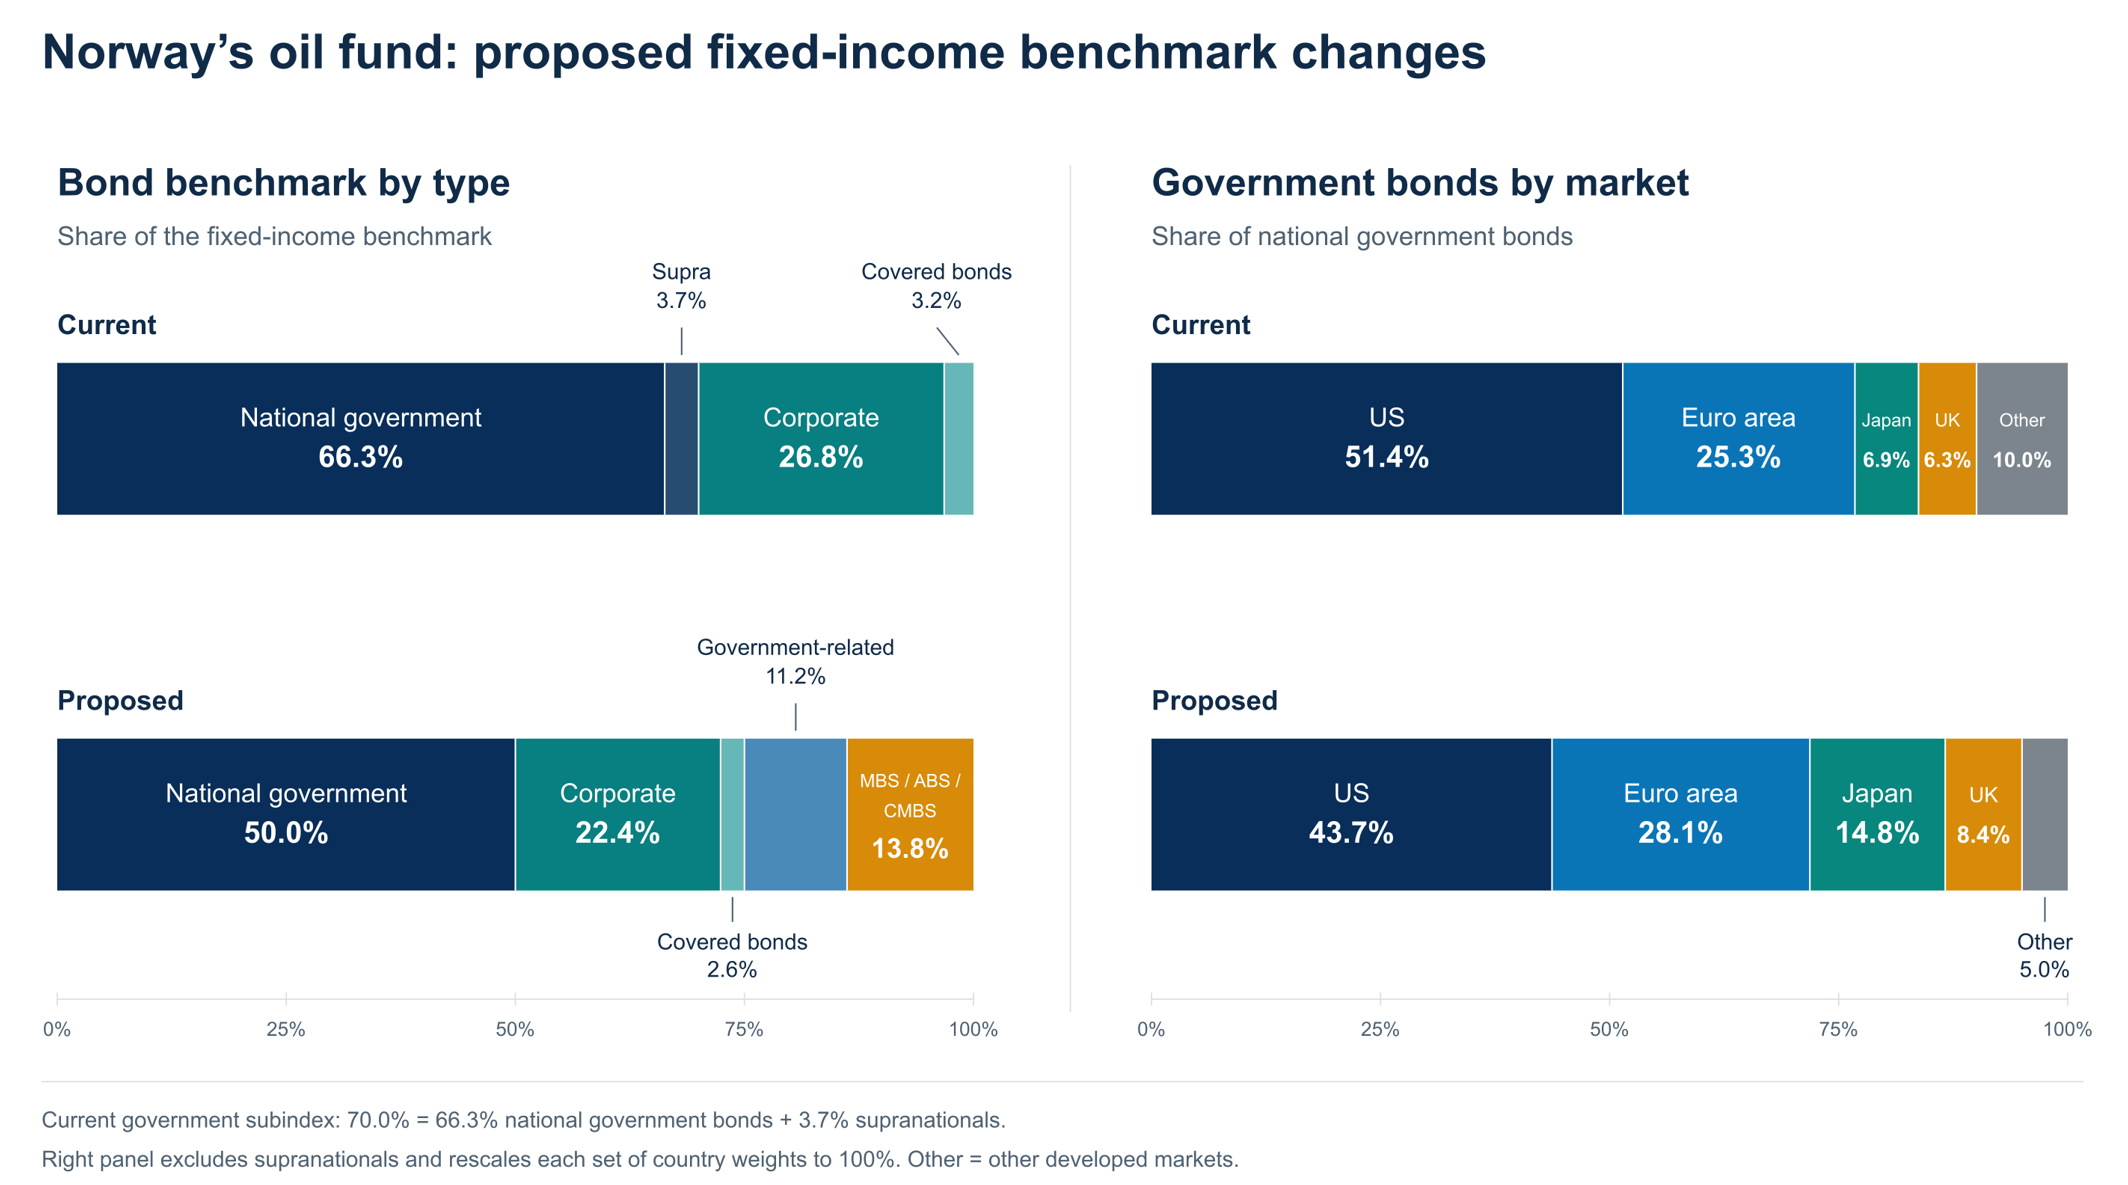
NBIM’s bond allocation rethink
September 8, 2026 7:30 AM UTC
* Proposal would imply $80bn~ Treasury sell, although little net USD change
* JGBs see marked pick up, presented as method change more than value, but…
* Several peers already follow broader bond mix. Is NBIM just ‘catch up’ or does to speak to wider concerns and incentives?
September 04, 2026
U.S. August Employment - Bounce due to corrections in two sectors but could matter in a close Fed call
September 4, 2026 1:28 PM UTC
August non-farm payrolls are stronger than expected, 162k overall, 127k private, with upward back month revisions. Unemployment is steady at 4.1% and as expected as are average hourly earnings with a 0.3% rise, but the workweek at 34.4 hours is surprisingly strong. The payroll surprise looks correct
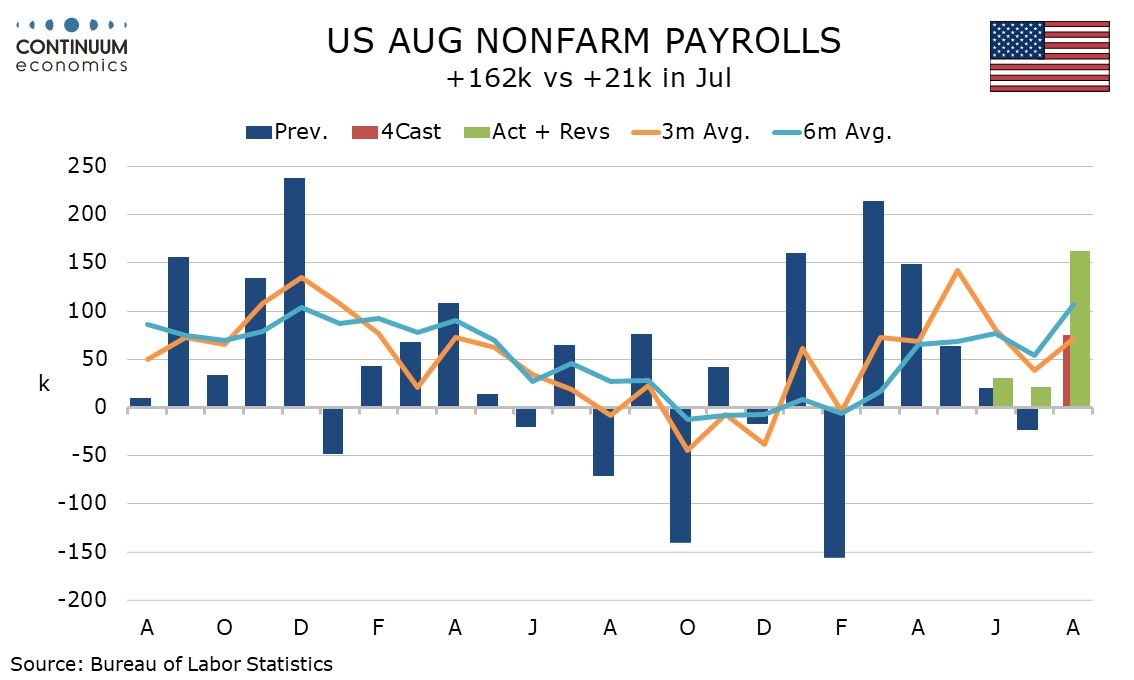
U.S. August Employment - Bounce due to corrections in two sectors but could matter in a close Fed call
September 4, 2026 1:27 PM UTC
August non-farm payrolls are stronger than expected, 162k overall, 127k private, with upward back month revisions. Unemployment is steady at 4.1% and as expected as are average hourly earnings with a 0.3% rise, but the workweek at 34.4 hours is surprisingly strong. The payroll surprise looks correct
September 03, 2026
Money supply - Fed Invites an Awkward Ex Back into its Life
September 3, 2026 10:52 AM UTC
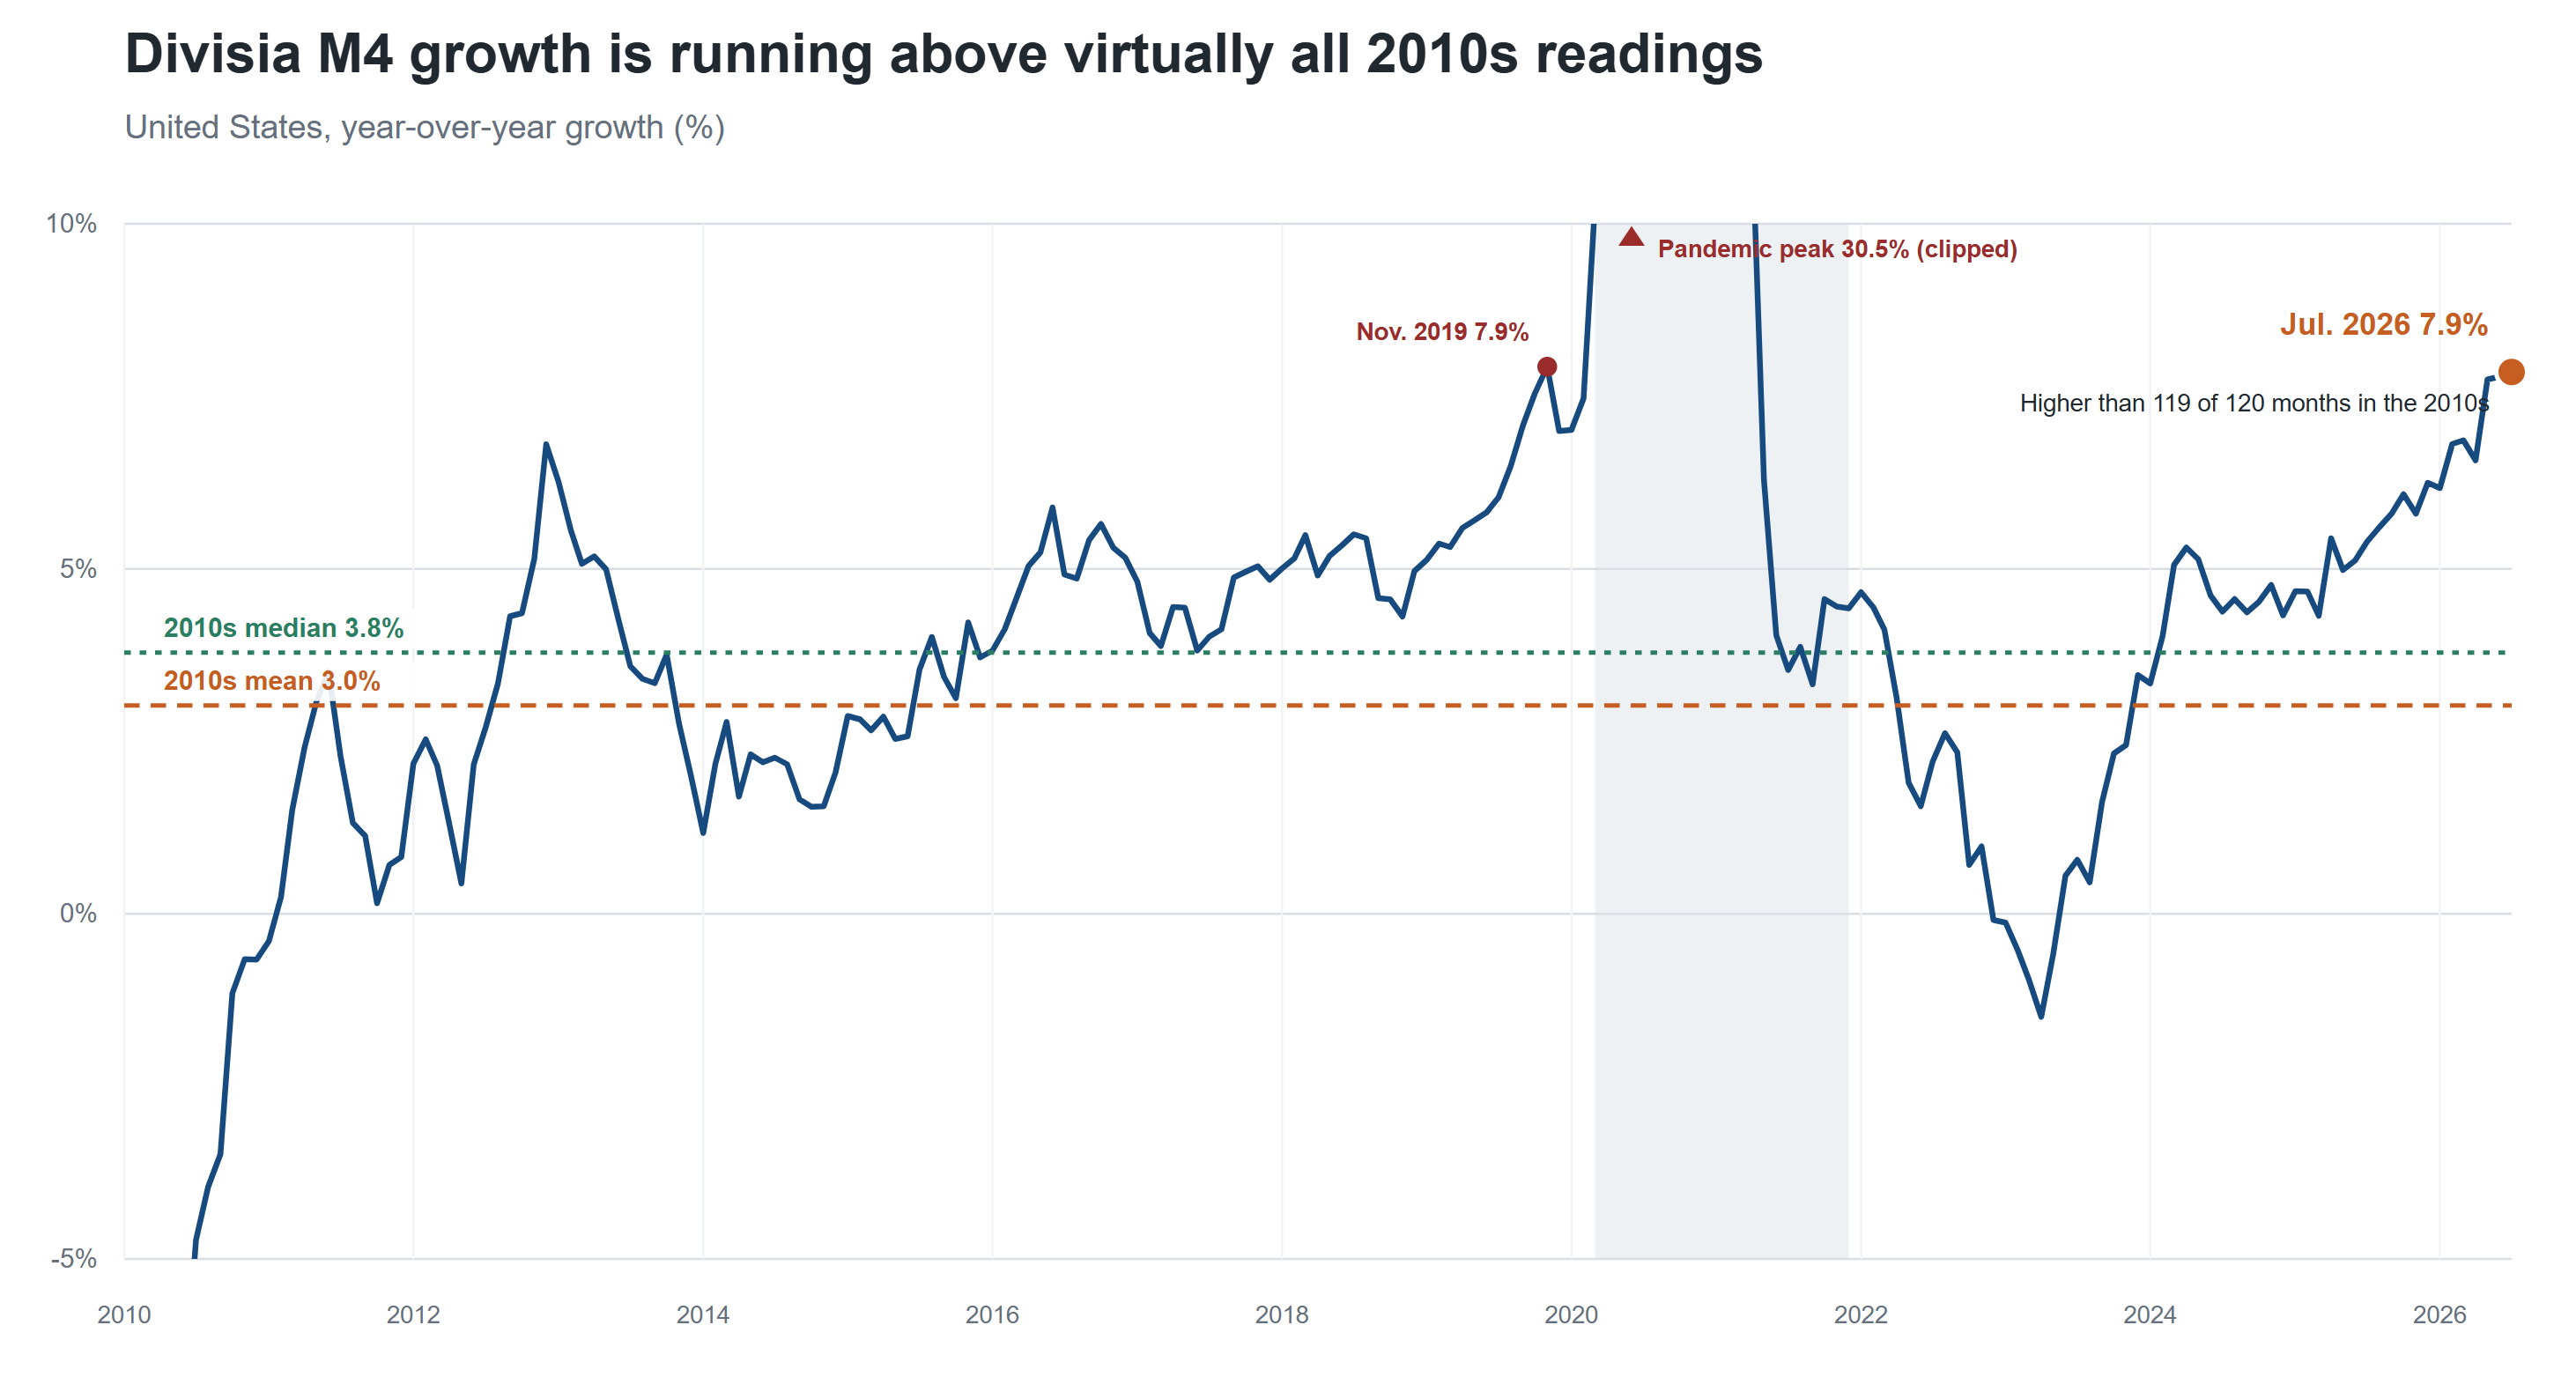
* Following the ‘Easter egg’ M2 reference, Warsh has made clear that ‘money matters’
* But while M2 was name-checked and described as benign, broader measures have been running strongly, well above the referenced 2010 norms
* M4 Divisia gives one of the better currently available measures, con
September 02, 2026
September 01, 2026
August 28, 2026
September FOMC Tightening Looks Likely After Warsh Speech
August 28, 2026 4:19 PM UTC
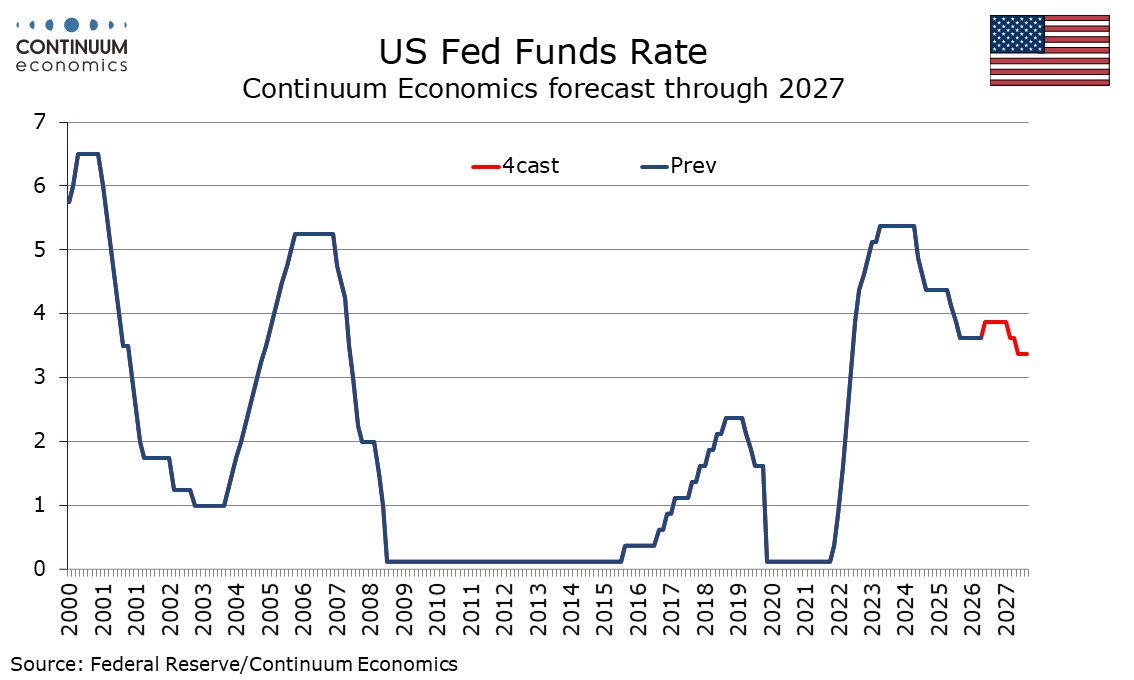
After the speech from Fed Chairman Kevin Warsh, it appears that failing to tighten in September would put Fed credibility at risk, unless we see some very soft data from the August non-farm payroll and CPI. The key sentence came near the end of his speech. “We must be confident that underlying inf
September FOMC Tightening Looks Likely After Warsh Speech
August 28, 2026 4:18 PM UTC
After the speech from Fed Chairman Kevin Warsh, it appears that failing to tighten in September would put Fed credibility at risk, unless we see some very soft data from the August non-farm payroll and CPI. The key sentence came near the end of his speech. “We must be confident that underlying inf
August 27, 2026
August 25, 2026
FOMC Discount Rate minutes show four districts backed a July hike
August 25, 2026 6:44 PM UTC
Minutes from the Fed’s discount rate meetings shortly before the July FOMC meeting show a not very hawkish 4 votes (out of 12) to increase the Discount Rate, from the Cleveland, Dallas, Kansas City and Minneapolis Feds.
Bessent’s Buybacks - bluster, bazooka or brittle bet?
August 25, 2026 3:57 PM UTC
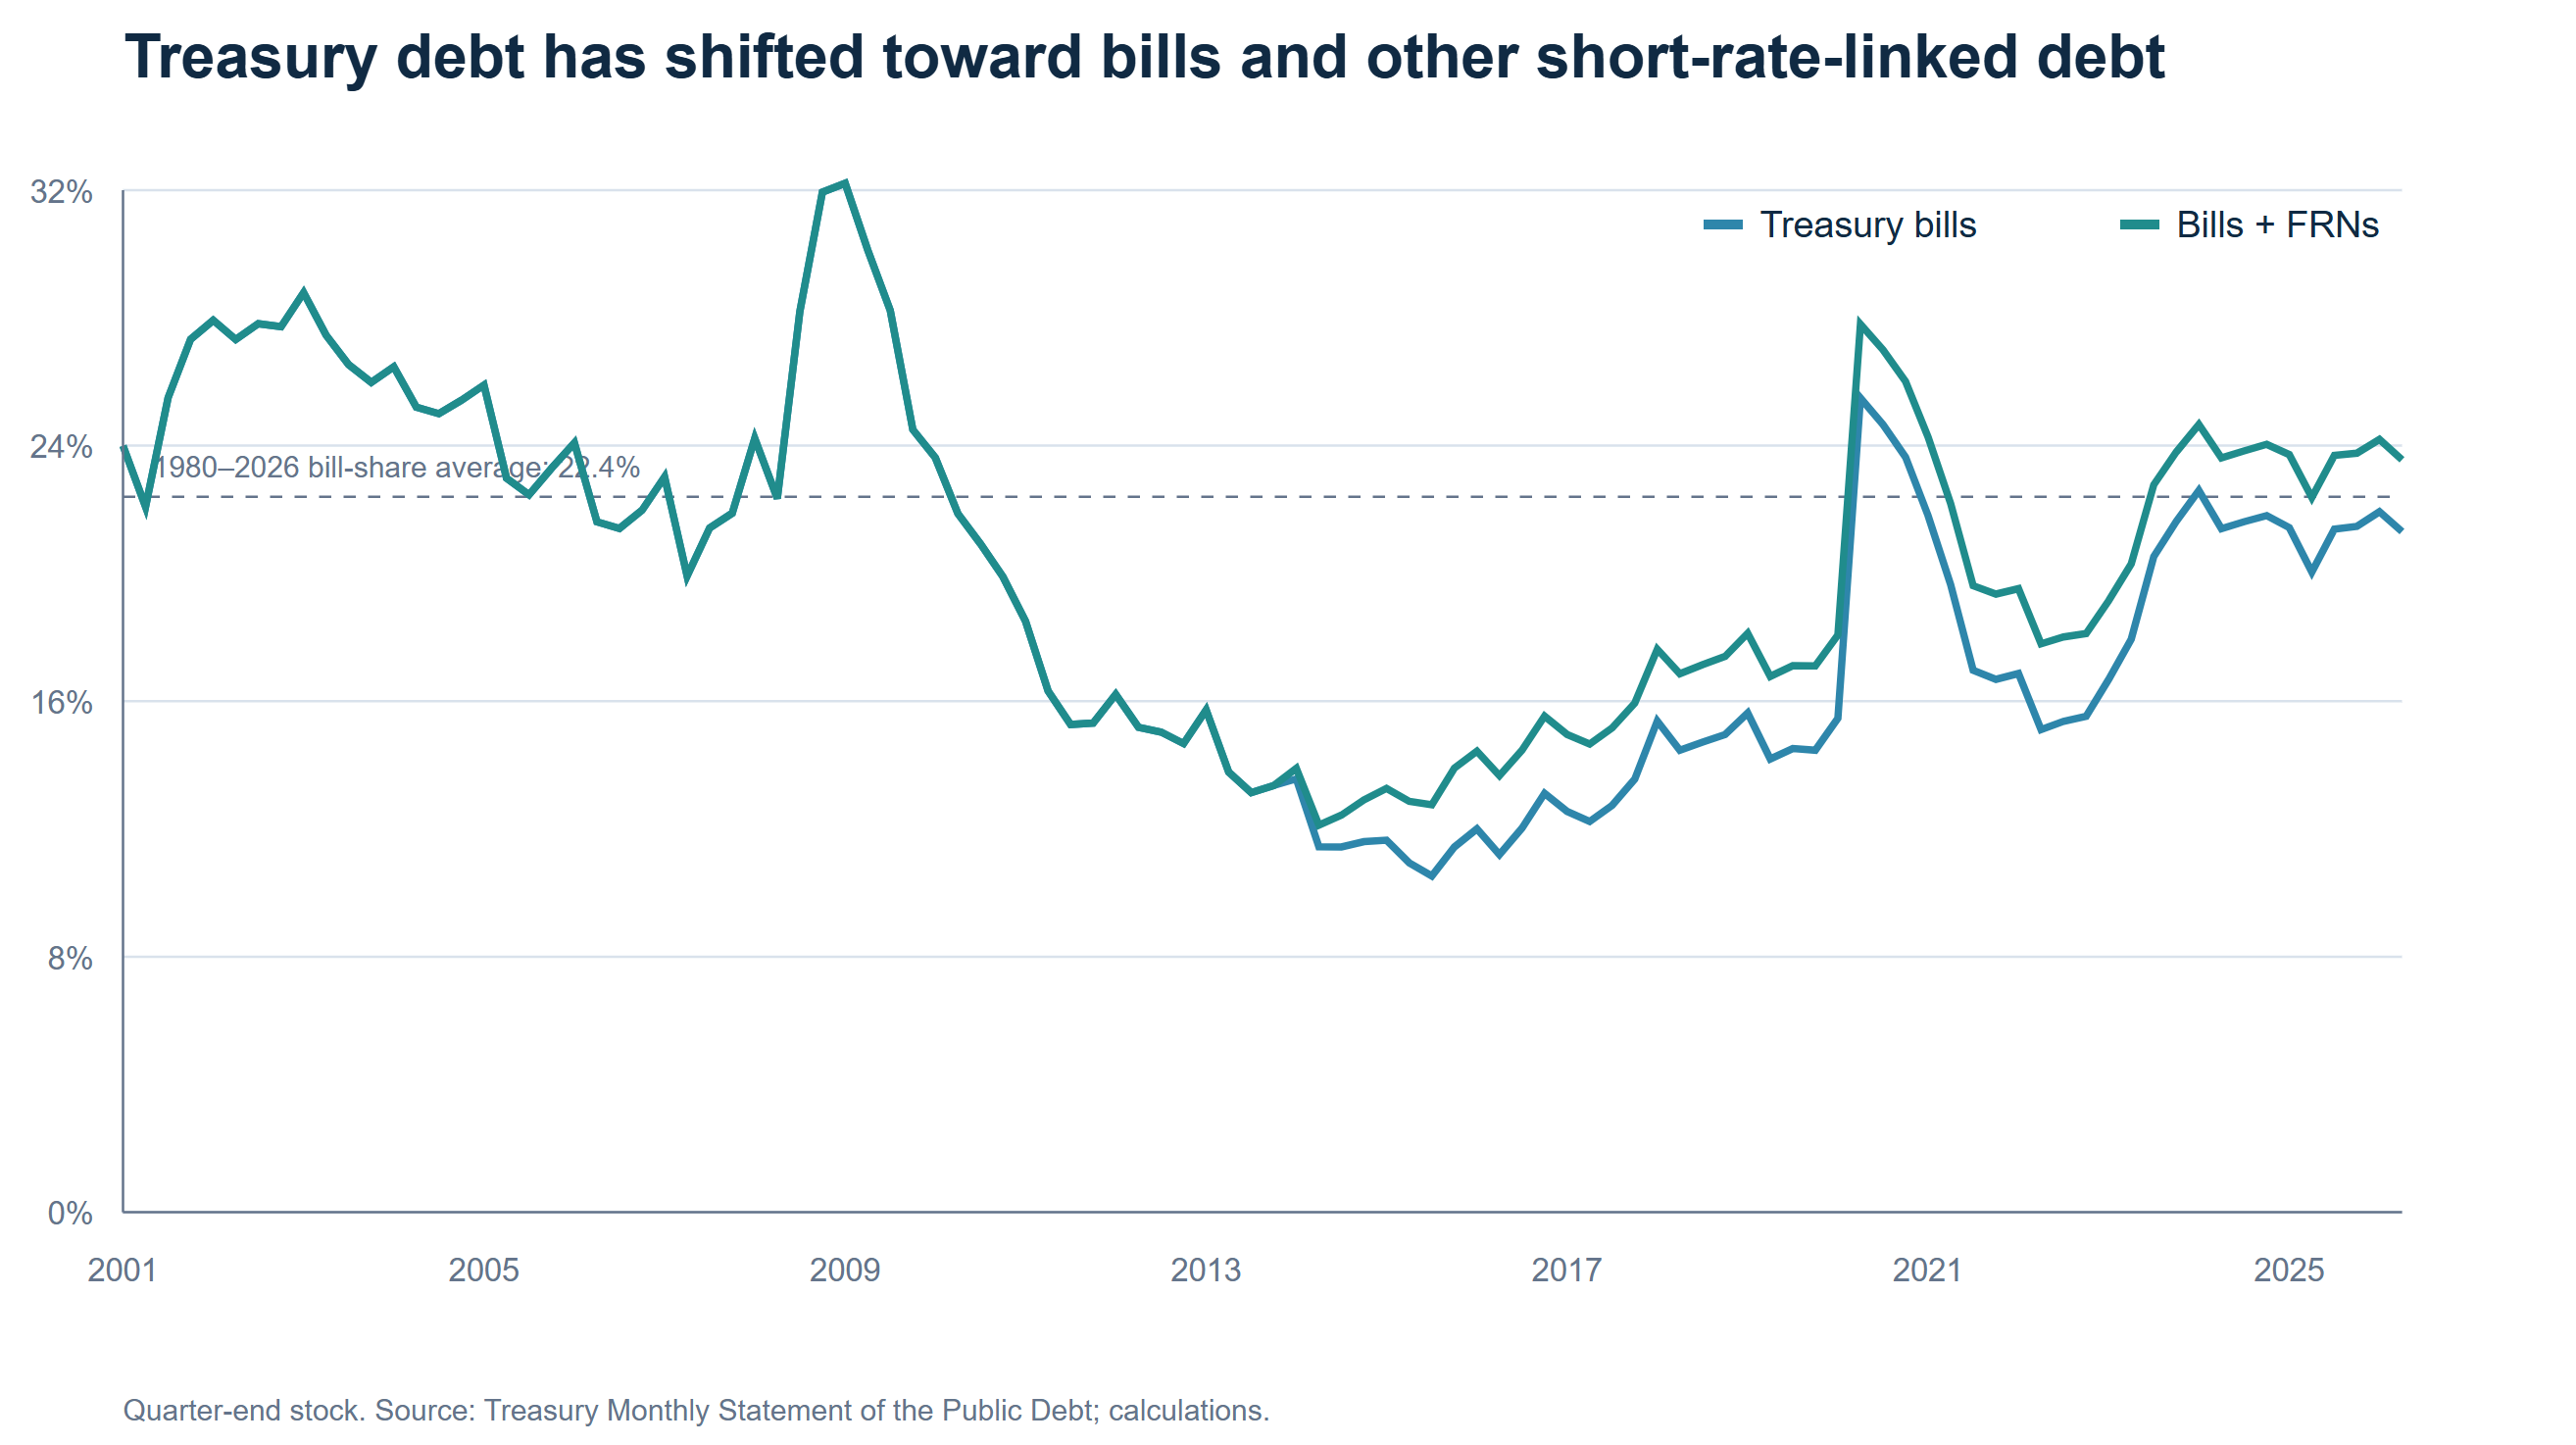
* Bessent’s buybacks – bazooka or peashooter? It depends on whether it’s a slippery slope. On current proposed scale, possibly only absorbs around 10% or so of gross long end Treasury issuance on duration basis
* Mooted TGA use is not a free $1trn money pot, though it could provide some short-t
August 20, 2026

DM Central Banks Watching Stablecoins
August 20, 2026 10:55 AM UTC
· Overall, DM central banks have a watching brief for stablecoins and the scale of growth in the next 5 years. This is largely a USD centric issue, with stablecoins dominated by USD issuance. Central banks are watchful on whether it impacts access to low cost deposit for banks; guardi
August 19, 2026

FOMC Minutes: Inter-meeting data seen as important
August 19, 2026 6:58 PM UTC
FOMC minutes from July 29 confirm that most participants supported leaving rates steady but several favored a 25bps tightening, implying more than the three hawkish dissenters, presumably non-voting district presidents. Many assessed that tightening would be necessary if inflation did not decline, w
FOMC Minutes: Inter-meeting data seen as important
August 19, 2026 6:56 PM UTC
FOMC minutes from July 29 confirm that most participants supported leaving rates steady but several favored a 25bps tightening, implying more than the three hawkish dissenters, presumably non-voting district presidents. Many assessed that tightening would be necessary if inflation did not decline, w
August 13, 2026
August 12, 2026
U.S. July CPI - On consensus, detail a marginal disappointment
August 12, 2026 1:15 PM UTC
July’s CPI is largely as expected, up 0.1% overall and 0.2% ex food and energy, with the latter at 0.215% before rounding only a marginal disappointment, though possibly a little more so in the detail. This does not provide a compelling case for Fed tightening in September, though by that meeting

Big EM Currencies: No U.S. Yield Pressure
August 12, 2026 7:55 AM UTC
· Our view remains that major EM currencies outlooks are being driven by relative domestic fundamentals versus the U.S. No major tensions are being seen from rising U.S. Treasury yields and Fed tightening fears. H2 2026 will likely see the choppy EM FX conditions continue against the
August 11, 2026

Taylor Rules for Uncertain Times
August 11, 2026 2:44 PM UTC
* The Fed’s rate puzzle has three awkward-shaped pieces: which inflation measure to trust, how much slack remains, and where r* now sits.
* Taylor rules may be deeply unfashionable, but they force those hidden assumptions into the open.
* Change only the inflation measure and the same rule can make
August 10, 2026
FOMC Minutes Preview: Hawks, Doves and Data-Dependents
August 10, 2026 2:50 PM UTC
FOMC minutes from July 29 are due on August 19 and will get extra attention with Chairman Warsh not having given a clear explanation of the decision to leave rates unchanged, after a meeting which saw three dissenting votes for tightening. The minutes may suggest that several in the majority could b

FOMC Minutes Preview: Hawks, Doves and Data-Dependents
August 10, 2026 2:49 PM UTC
FOMC minutes from July 29 are due on August 19 and will get extra attention with Chairman Warsh not having given a clear explanation of the decision to leave rates unchanged, after a meeting which saw three dissenting votes for tightening. The minutes may suggest that several in the majority could b