View:
October 21, 2026
Preview: Due October 29 - U.S. Q3 GDP - Stronger growth, slower inflation

October 21, 2026 4:03 PM UTC
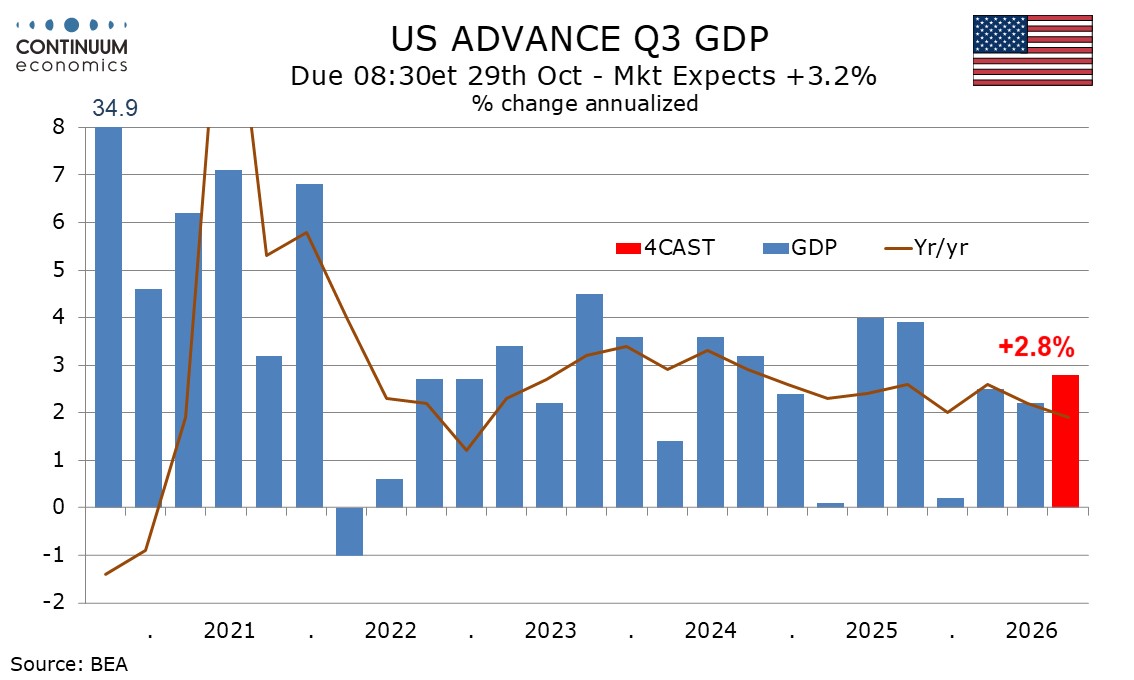
We expect a Q3 GDP increase of 2.8% annualized, a modest acceleration from the two preceding quarters to a 4-quarter high. We expect a 2.4% increase in core PCE prices, still above target but the slowest since a matching Q3 2024.
Preview: Due October 29 - U.S. Q3 GDP - Stronger growth, slower inflation
October 21, 2026 4:03 PM UTC
We expect a Q3 GDP increase of 2.8% annualized, a modest acceleration from the two preceding quarters to a 4-quarter high. We expect a 2.4% increase in core PCE prices, still above target but the slowest since a matching Q3 2024.
FX Daily Strategy: Asia, Oct 22
October 21, 2026 2:35 PM UTC
Positioning and oversold conditions obstructing euro follow through traction; downside focus switching to options protection
AUD lifted by short-covering and momentum swing towards a Nov hike pricing
Focus remains news driven rather than calendar-centric
Bank of Canada Preview for October 28: Steady, December tightening not a done deal
October 21, 2026 2:04 PM UTC
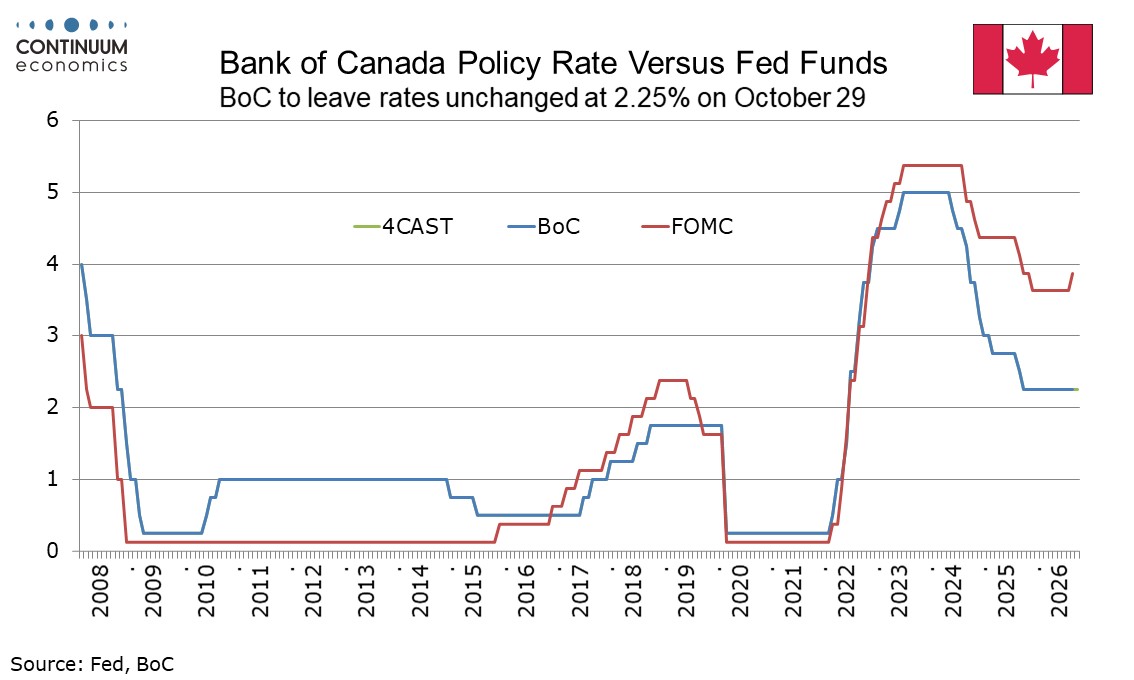
The Bank of Canada meets on October 28 and recent soft employment and core inflation data suggest rates will be left unchanged at 2.25%. The BoC is still likely to express more concern about upside than downside risks, but may sound a little more balanced than was the case at the last meeting on Sep
Bank of Canada Preview for October 28: Steady, December tightening not a done deal

October 21, 2026 2:04 PM UTC
The Bank of Canada meets on October 28 and recent soft employment and core inflation data suggest rates will be left unchanged at 2.25%. The BoC is still likely to express more concern about upside than downside risks, but may sound a little more balanced than was the case at the last meeting on Sep
Strains bring financial conditions into the eurozone mix
October 21, 2026 9:06 AM UTC
* French stress and ECB Lagarde comments switch focus to the tightening in financial conditions
*Past studies show material impact from significant episodes...
* ...with possible implications for core bond demand, ECB pricing and the wider appetite for risk across FX and markets.
China September Activity Data Review: Dichotomy between Supply and Demand
October 21, 2026 1:32 AM UTC
China’s dichotomy between supply and demand continued to deepen in September, as sluggish retail sales and fixed-asset investment slump highlighted persistent weakness in domestic demand, with analysts expecting more policy stimulus from Beijing to stave off downside risks. Export and Industrial n
October 20, 2026
FOMC Preview for October 28: Tightening to be debated but delayed
October 20, 2026 2:59 PM UTC
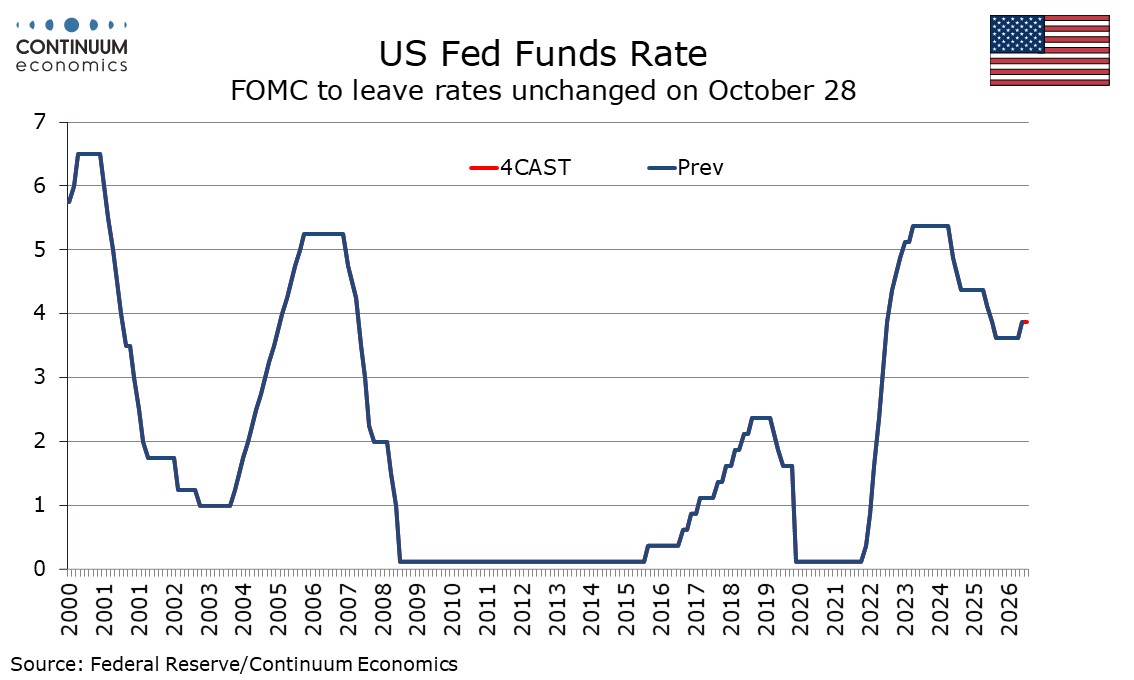
The FOMC meets on October 28 and a strong case for a second straight tightening can be made and will certainly be debated at the meeting. However to appears more likely that the Fed will leave rates unchanged at 3.75-4.0%. It is likely that December’s meeting will see a tightening, but Chairman Wa
FOMC Preview for October 28: Tightening to be debated but delayed
October 20, 2026 2:58 PM UTC
The FOMC meets on October 28 and a strong case for a second straight tightening can be made and will certainly be debated at the meeting. However to appears more likely that the Fed will leave rates unchanged at 3.75-4.0%. It is likely that December’s meeting will see a tightening, but Chairman Wa
U.S. September Pending Home Sales - More signs of housing sector weakness
October 20, 2026 2:17 PM UTC
September’s 7.3% decline in pending home sales is the sharpest decline since December with the level a record low. This adds to growing evidence that rising mortgage rates are undermining housing demand.
U.S. September Housing Starts and Permits - Signs of weakness building
October 20, 2026 12:50 PM UTC
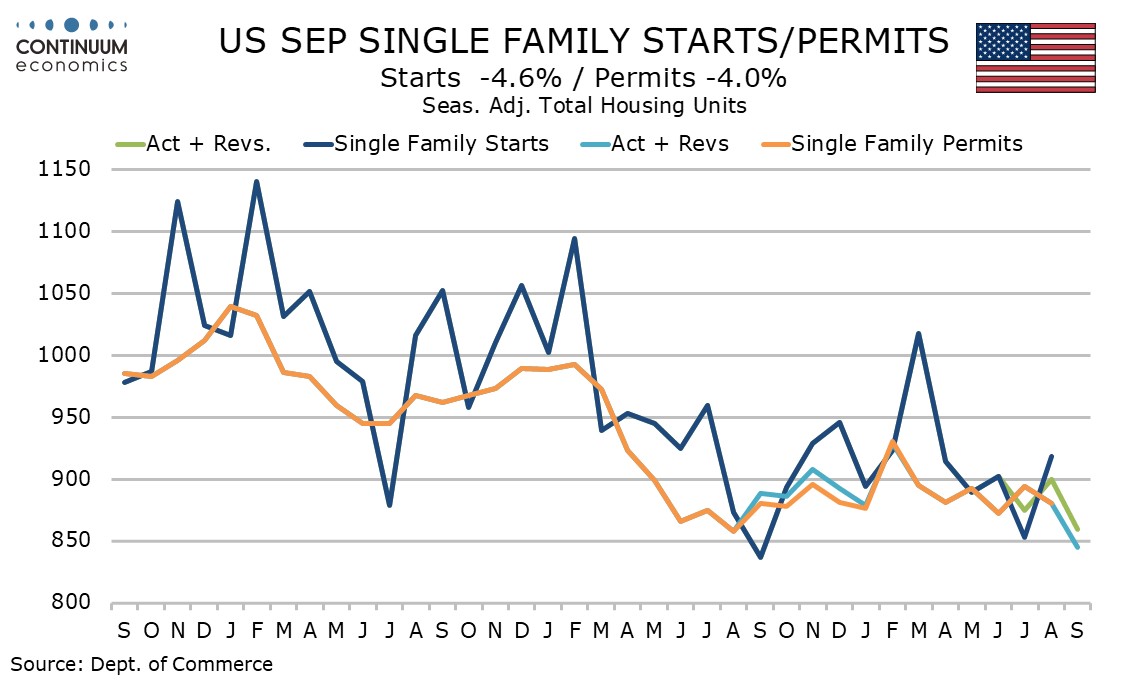
September housing starts are clearly weaker than expected, -5.2% to 1221k, with both singles and multiples lower. Permits held up better, -0.2% to 1400k, but with multiples up and singles down the net message is for a slowing housing sector, restrained by rising mortgage rates.
U.S. September Housing Starts and Permits - Signs of weakness building
October 20, 2026 12:50 PM UTC
September housing starts are clearly weaker than expected, -5.2% to 1221k, with both singles and multiples lower. Permits held up better, -0.2% to 1400k, but with multiples up and singles down the net message is for a slowing housing sector, restrained by rising mortgage rates.