Foreign Exchange
View:
November 18, 2026
FX Daily Strategy: Asia, Nov 19

November 18, 2026 4:22 PM UTC
AUD current more influenced by commodity pressure than data, while also very 'short and right'
Watching Nov book close for potential influences on positioning; has already amplified the tech pullback
NOK also around key levels amid the oil retreat
U.S. October Housing Starts and Permits - Mixed but on balance negative
November 18, 2026 1:46 PM UTC
October housing starts are con the firm side of expectations, +9.9% to 1.309, but permits, -7.4% to 1.295m are well below expectations. On balance the picture is of a weakening housing market given upward pressure on mortgage rates.
November 17, 2026
Preview: Due November 25 - U.S. October Personal Income and Spending - 5-month high for yr/yr core PCE prices
November 17, 2026 5:36 PM UTC
We expect October to see gains of 0.4% in personal income and personal spending, while PCE prices rise by 0.3% both overall and ex food and energy, meaning only marginal gains for income and spending in real terms.
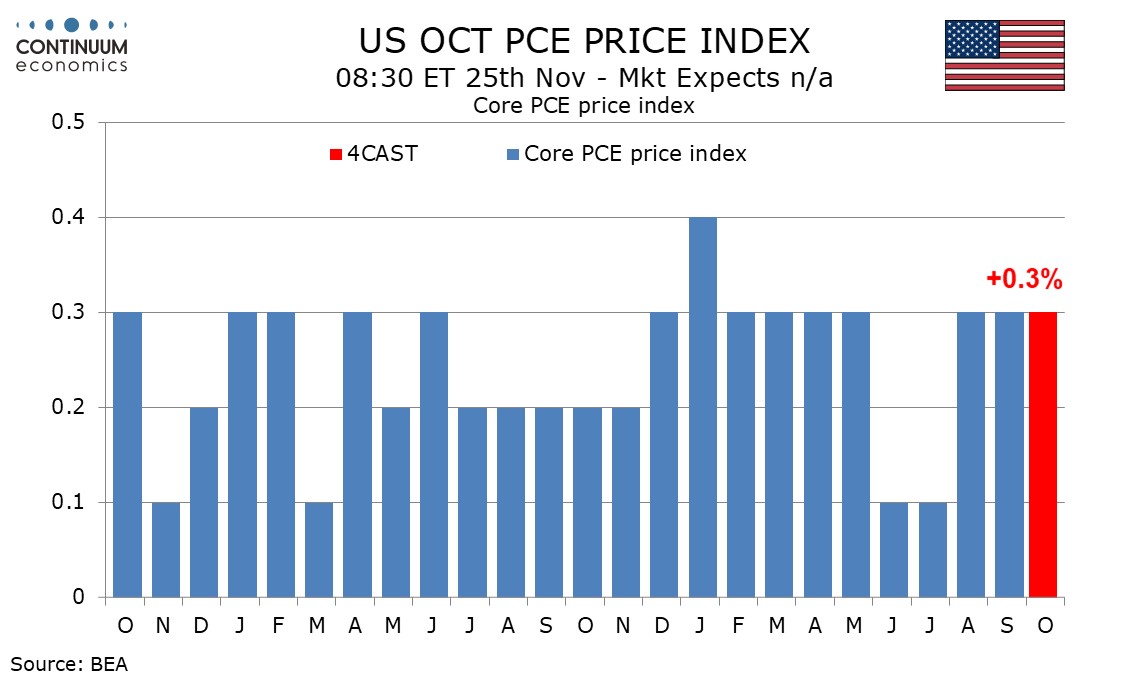
Preview: Due November 25 - U.S. October Personal Income and Spending - 5-month high for yr/yr core PCE prices
November 17, 2026 5:35 PM UTC
We expect October to see gains of 0.4% in personal income and personal spending, while PCE prices rise by 0.3% both overall and ex food and energy, meaning only marginal gains for income and spending in real terms.
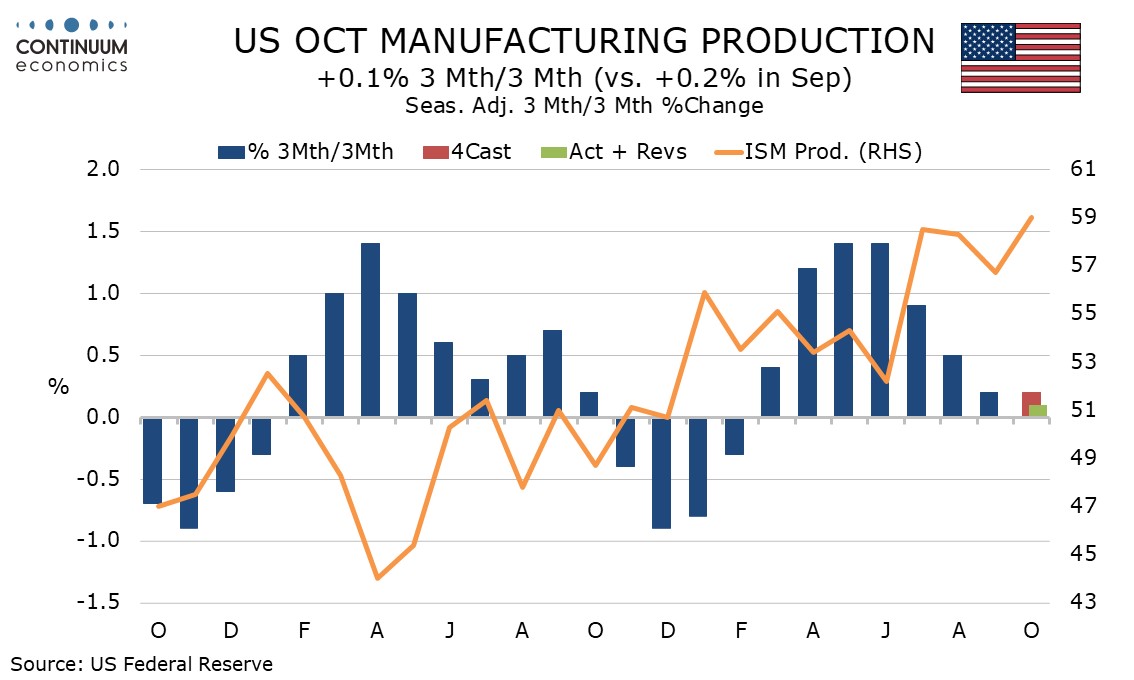
U.S. October Industrial Production - Utilities plunge, autos bounce, weaker elsewhere
November 17, 2026 2:33 PM UTC
October industrial production saw a 0.4% decline largely on a correction in the weather-related utilities sector. Manufacturing saw a second straight 0.3% increase, in line with expectations, but detail is less impressive, with the rise more than fully explained by autos.
U.S. October Industrial Production - Utilities plunge, autos bounce, weaker elsewhere
November 17, 2026 2:33 PM UTC
October industrial production saw a 0.4% decline largely on a correction in the weather-related utilities sector. Manufacturing saw a second straight 0.3% increase, in line with expectations, but detail is less impressive, with the rise more than fully explained by autos.
U.S. October Retail Sales - Continued underlying momentum
November 17, 2026 1:49 PM UTC
October retail sales are weak at 0.2% overall as autos see a soft month, but in line with consensus. Ex autos the rise is respectable at 0.6%, with the control group that contributes to GDP rising by the same amount. Sales rose by 0.5% ex autos and gasoline.
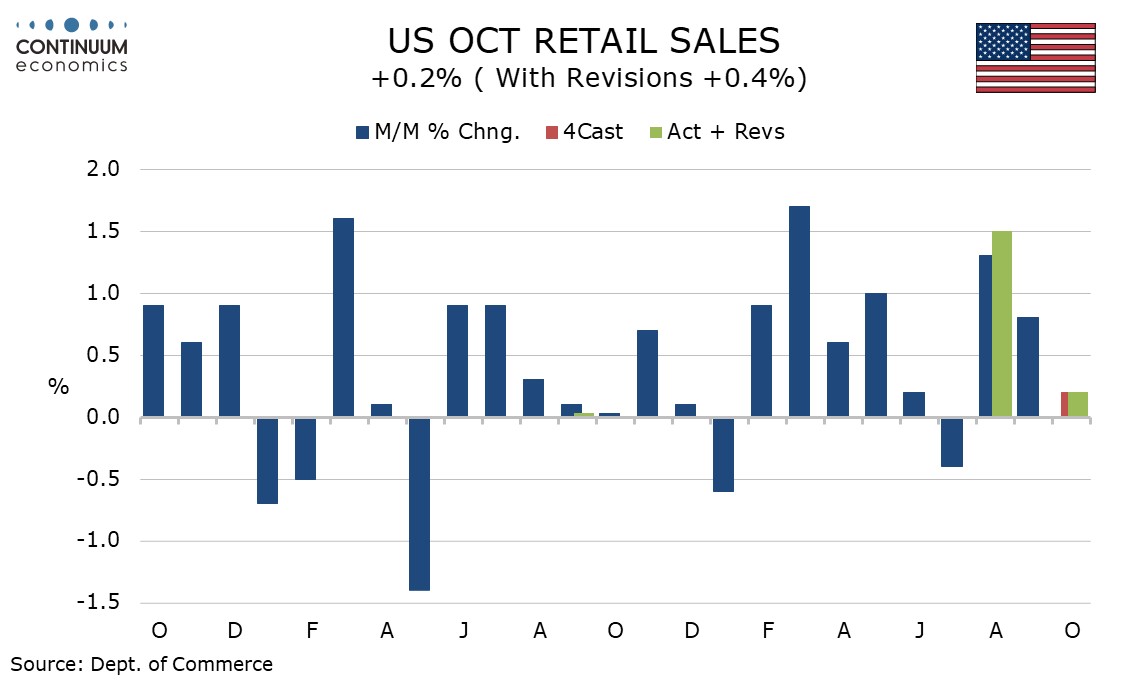
U.S. October Retail Sales - Continued underlying momentum
November 17, 2026 1:49 PM UTC
October retail sales are weak at 0.2% overall as autos see a soft month, but in line with consensus. Ex autos the rise is respectable at 0.6%, with the control group that contributes to GDP rising by the same amount. Sales rose by 0.5% ex autos and gasoline.
November 16, 2026
Preview: Due December 4 - U.S. November Employment (Non-Farm Payrolls) - Slower but far from weak
November 16, 2026 4:14 PM UTC
While there is no real reason to expect the labor market to break from trend, we expect October’s above trend 165k non-farm payroll increase to be followed by slower but still healthy 95k in November. We expect unemployment to remain at 4.1%, but with less impressive details than in October. Earni
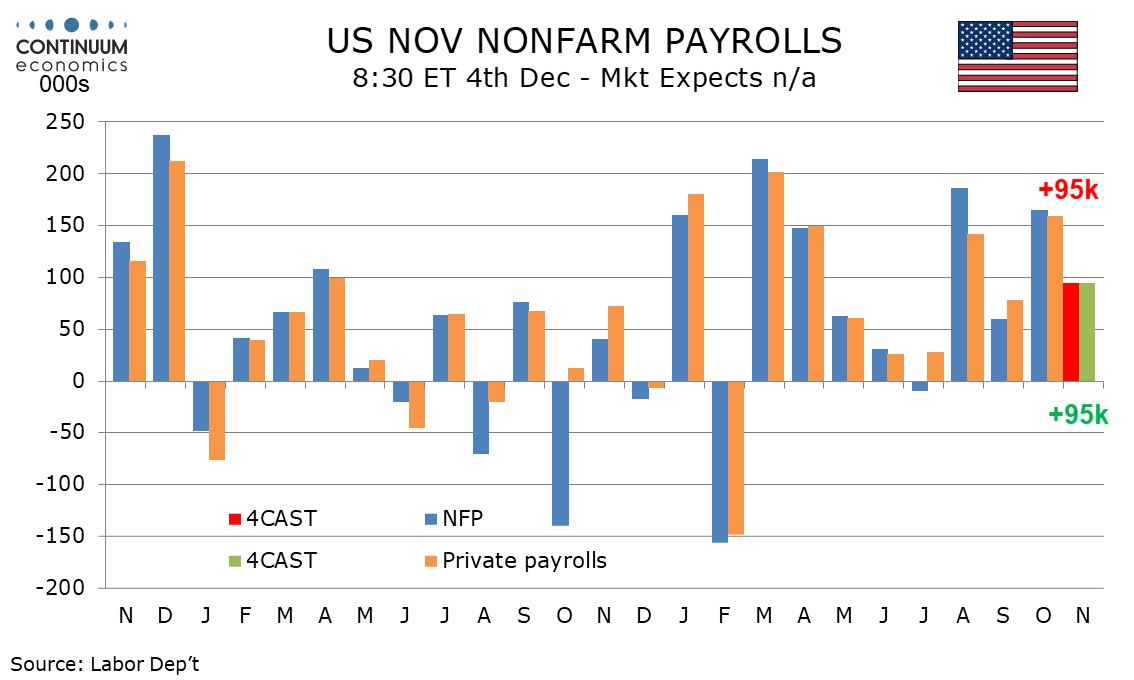
Preview: Due December 4 - U.S. November Employment (Non-Farm Payrolls) - Slower but far from weak
November 16, 2026 4:14 PM UTC
While there is no real reason to expect the labor market to break from trend, we expect October’s above trend 165k non-farm payroll increase to be followed by slower but still healthy 95k in November. We expect unemployment to remain at 4.1%, but with less impressive details than in October. Earni
Canada October CPI - Still little energy pass-through
November 16, 2026 1:52 PM UTC
October Canadian CPI, stable at 3.1% yr/yr, will probably come as some relief to the bank of Canada, continuing to show little evidence of pass-through to underlying inflation from energy prices. However there remain fears that the New Year could be the time that the pass-through starts to appear, g
Preview: Due November 17 - U.S. October Industrial Production - Dip on utilities, manufacturing still healthy
November 16, 2026 1:03 PM UTC
We expect a 0.1% decline in October US industrial production due to a significant correction lower in weather-sensitive utilities. We expect a respectable 0.4% increase in manufacturing.
Preview: Due November 17 - U.S. October Retail Sales - Momentum solid but some risk of slowing
November 16, 2026 12:57 PM UTC
We expect October retail sales to rise by 0.2% overall and by 0.4% ex autos, with a 0.3% increase ex auto and gasoline. There is some risk that Q3’s impressive resilience in retail sales will fade in Q4, but we do not expect October data to give any strong signals of that.
Europe Summary and Highlights 16 Nov
November 16, 2026 11:10 AM UTC
Dollar retains edge, slowing trend-action maintained across many pairs, some into bigger levels
Japan data slightly undershoots, USD/JPY keeps safe distance
AUD remains weighed since break, soft tech, copper, China data with the grain on the session
November 13, 2026
Preview: Due November 30 - Canada Q3/September GDP - Slower but with still healthy domestic demand
November 13, 2026 7:54 PM UTC
We expect Q3 Canadian GDP to increase by 1.3% annualized, consistent with the signals from monthly data assuming a 0.1% decline in September as suggested with August’s report. However, quarterly detail is likely to show a healthy picture outside a steeper inventory depletion.
Preview: Due November 16 - Canada October CPI - Slightly firmer
November 13, 2026 4:52 PM UTC
We expect September Canadian CPI to increase to 3.3% yr/yr in October from 3.1%, and to 3.27% from 3.09% before rounding. This would be the highest since December 2023. Energy will lead the increase, though we expect a marginal pick-up in CPI-Median, one of the Bank of Canada’s three core rates.
U.S. October PPI - Still firm ex food, energy and trade
November 13, 2026 2:05 PM UTC
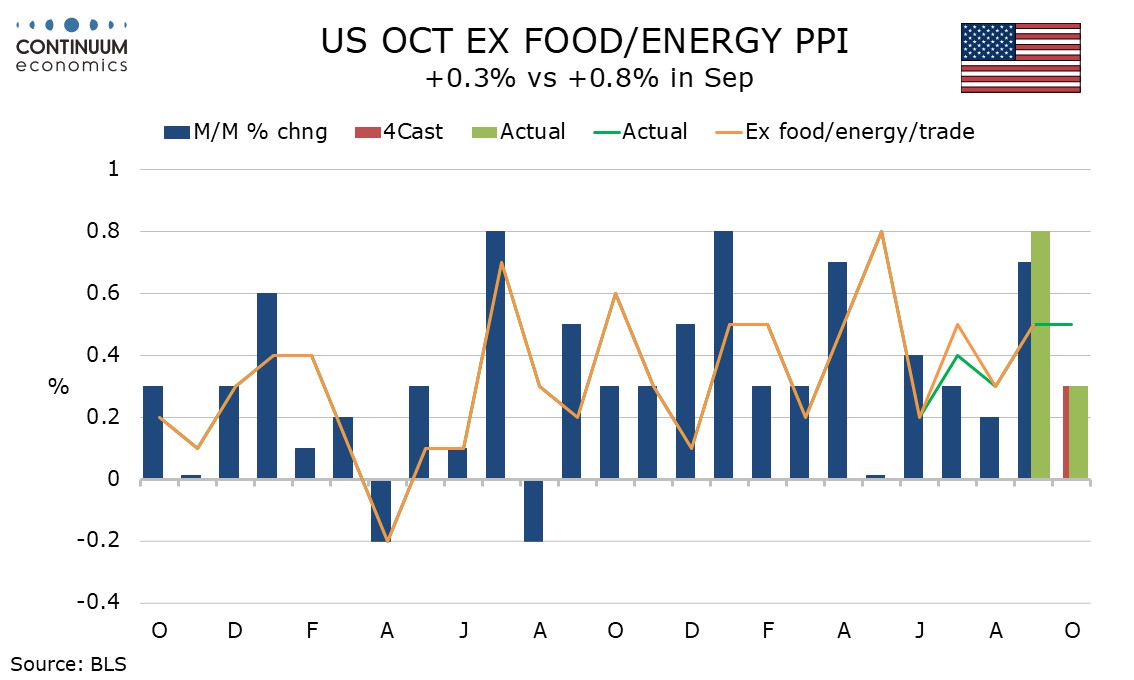
Overall October PPI is slightly softer than expected at 0.3% with a matching increase ex food and energy, this on consensus. However a 0.5% increase ex food, energy and trade suggests underlying strength, above what is acceptable to the Fed, persists.
U.S. October PPI - Still firm ex food, energy and trade
November 13, 2026 2:04 PM UTC
Overall October PPI is slightly softer than expected at 0.3% with a matching increase ex food and energy, this on consensus. However a 0.5% increase ex food, energy and trade suggests underlying strength, above what is acceptable to the Fed, persists.
November 12, 2026
Preview: Due December 4 - Canada November Employment - Avoiding a fourth straight decline
November 12, 2026 6:49 PM UTC
We expect Canadian employment to increase by 15k in a correction from three straight declines. GDP growth is likely to be slow in Q4 due to US tariffs but is unlikely to be negative, and that argues against a negative employment trend. We expect unemployment to slip back to 6.6% from 6.7%, while rem
Preview: Due November 25 - U.S. October New Home Sales - Several signals for weakness
November 12, 2026 5:56 PM UTC
We expect a 6.1% decline in October new home sales to 635k, which would be the lowest level since February. Even this would leave new home sales looking more resilient than other measures of housing demand.
U.S. October Existing Home Sales - Rising mortgage rates having an impact
November 12, 2026 3:13 PM UTC
October existing home sales have resumed a negative trend with a steep 5.5% decline to follow a 1.0% increase in September, which was the first rise in four months. The level of 3.75m is the weakest since August 2010.
US Initial Claims still low but rise merits some attention
November 12, 2026 1:41 PM UTC
Initial claims at 200k remain very low, though have risen to a 4-week high from last week’s 191k (revised from 189k, which matched the July 18 low). The survey week for November’s non-farm payroll comes next week.
Preview: Due November 13 - U.S. October PPI - Firm if less so than in September
November 12, 2026 12:59 PM UTC
We expect October PPI to increase by 0.4% overall and 0.3% ex food and energy, still too high for comfort but considerably slower than respective gains of 1.3% and 0.7% in September. Ex food, energy and trade, we expect only a marginal slowing, to 0.4% from 0.5% in September.
November 11, 2026
Preview: Due November 17 - U.S. October Industrial Production - Dip on utilities, manufacturing still healthy
November 11, 2026 3:52 PM UTC
We expect a 0.1% decline in October US industrial production due to a significant correction lower in weather-sensitive utilities. We expect a respectable 0.4% increase in manufacturing.
Preview: Due November 17 - U.S. October Retail Sales - Momentum solid but some risk of slowing
November 11, 2026 1:15 PM UTC
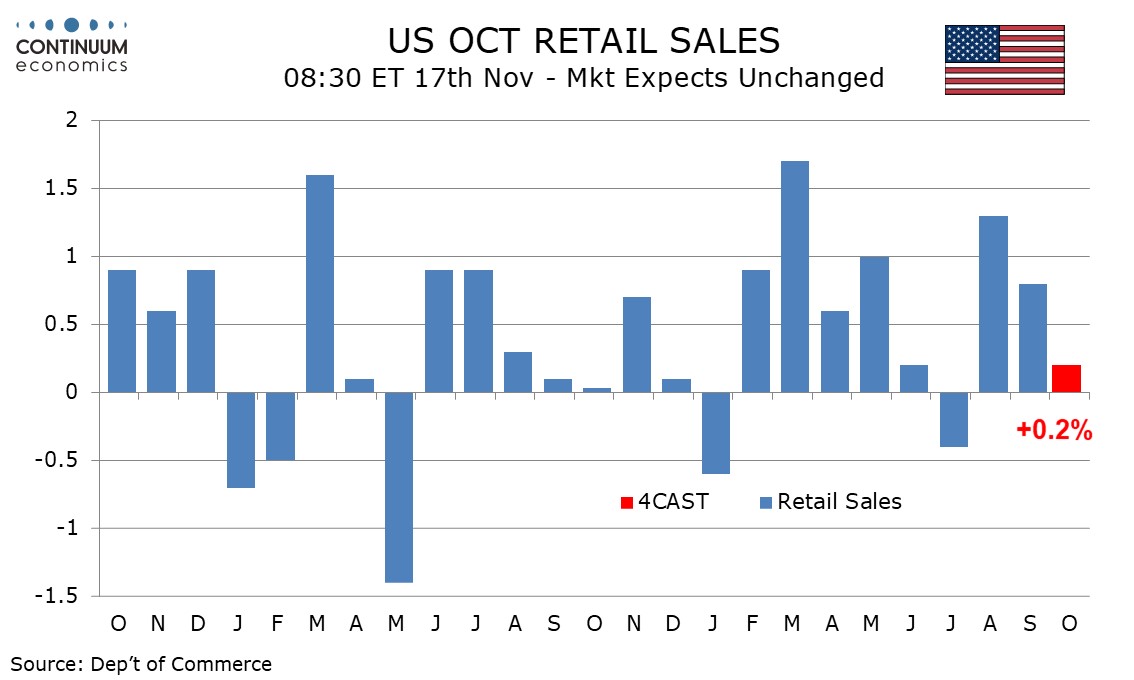
We expect October retail sales to rise by 0.2% overall and by 0.4% ex autos, with a 0.3% increase ex auto and gasoline. There is some risk that Q3’s impressive resilience in retail sales will fade in Q4, but we do not expect October data to give any strong signals of that.
Preview: Due November 17 - U.S. October Retail Sales - Momentum solid but some risk of slowing
November 11, 2026 1:14 PM UTC
We expect October retail sales to rise by 0.2% overall and by 0.4% ex autos, with a 0.3% increase ex auto and gasoline. There is some risk that Q3’s impressive resilience in retail sales will fade in Q4, but we do not expect October data to give any strong signals of that.
November 10, 2026
U.S. October Median CPI up 3.7% annualized, confirming CPI strength was broad based
November 10, 2026 8:19 PM UTC
Emphasizing the disappointing nature of the October CPI, the 0.3% rise in the Cleveland Fed’s Median CPI is consistent with the core CPI released earlier and the annualized pace of 3.7% is a 5-month high.
U.S. October CPI - 50bps now set to be debated at December FOMC
November 10, 2026 2:14 PM UTC
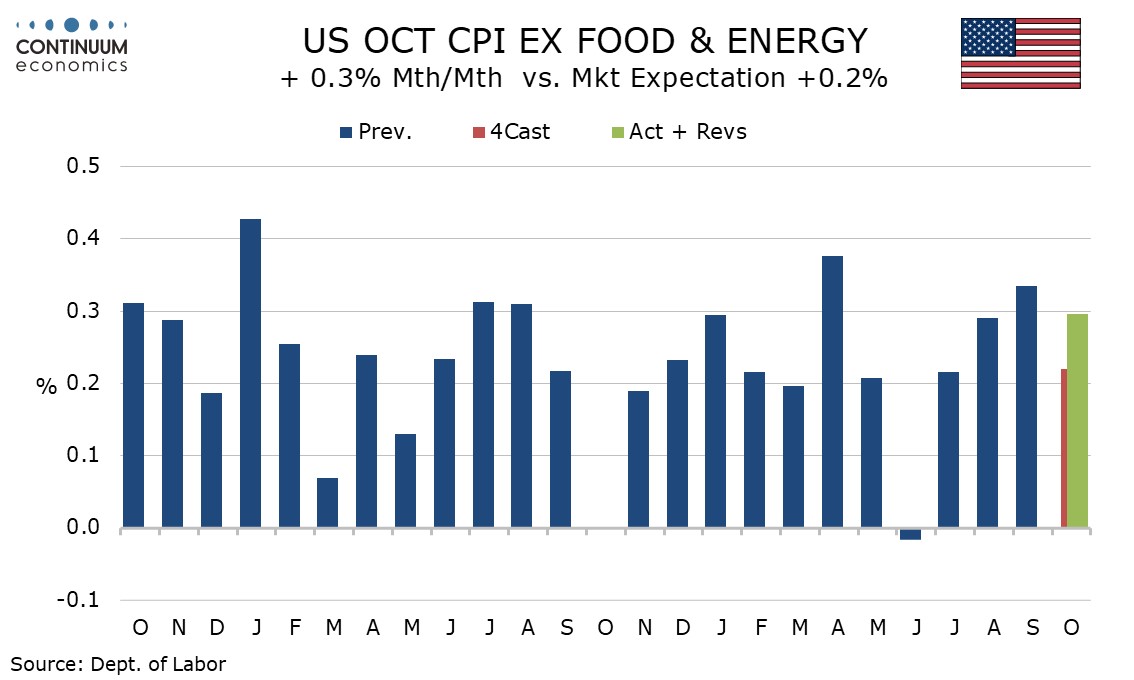
October CPI has come in stronger than expected at 0.4% overall with a third straight 0.3% rise in the core rate ex food and energy. Earlier today Fed’s Waller suggested that a 0.3% core increase would justify a 50bps tightening in December. That looks sure to be debated, particularly after October
U.S. October CPI - 50bps now set to be debated at December FOMC
November 10, 2026 2:14 PM UTC
October CPI has come in stronger than expected at 0.4% overall with a third straight 0.3% rise in the core rate ex food and energy. Earlier today Fed’s Waller suggested that a 0.3% core increase would justify a 50bps tightening in December. That looks sure to be debated, particularly after October