DM Data Weekly Oct 19-23
Quiet week in the US, outside of earnings
Eurozone PMIs, UK CPI and labour mkt data. Latter expected to cement Nov hike but no more
CPI the focus for Canada and NZ
Data Week Ahead
USA
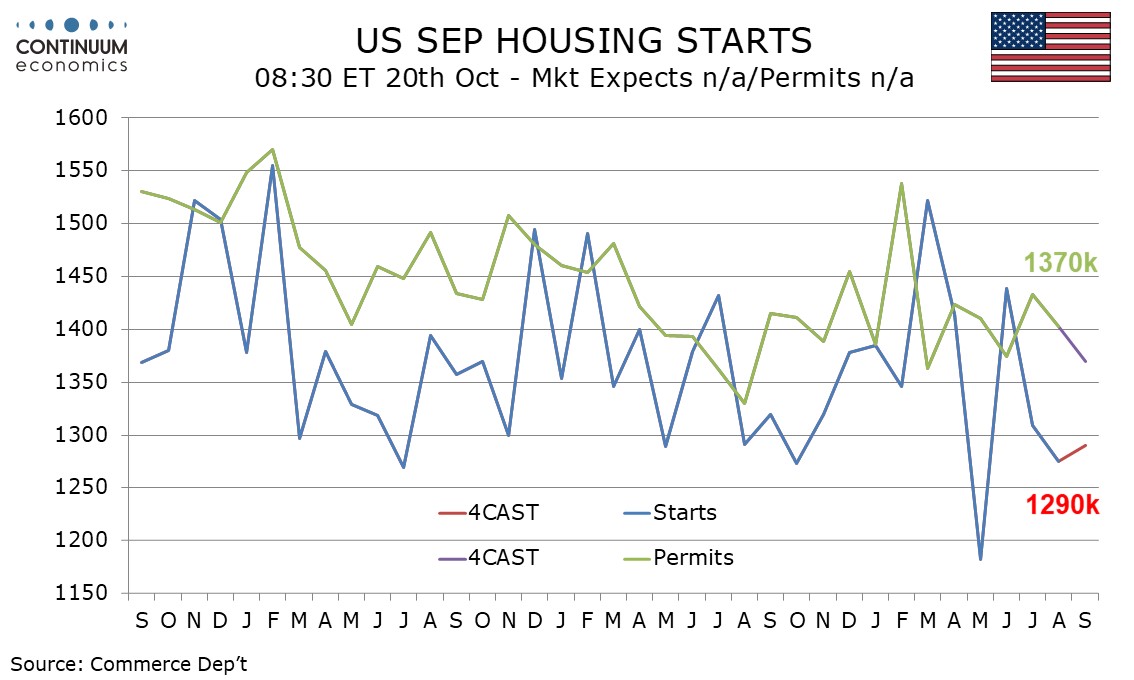
It is a very quiet week for the US calendar, with Fed speakers set to be quiet ahead of the October 28 rates decision. The data calendar is limited too. October’s NAHB homebuilders’ index is due on Monday. On Tuesday we expect September housing starts to rise by 1.2% to 1290k but permits to fall by 2.6% to 1370k. Thursday’s initial claims will cover the survey week for October’s non-farm payroll. September’s leading indicator follows. The most significant release of the week may be October’s S and P PMIs, which will be following very strong September data. The final October Michigan CSI is also due on Friday.
Earnings season also a background focus, with Meta, Tesla, and IBM on the tech side on Wednesday, the likes of GE, GM and Netflix on Tuesday.
CANADA
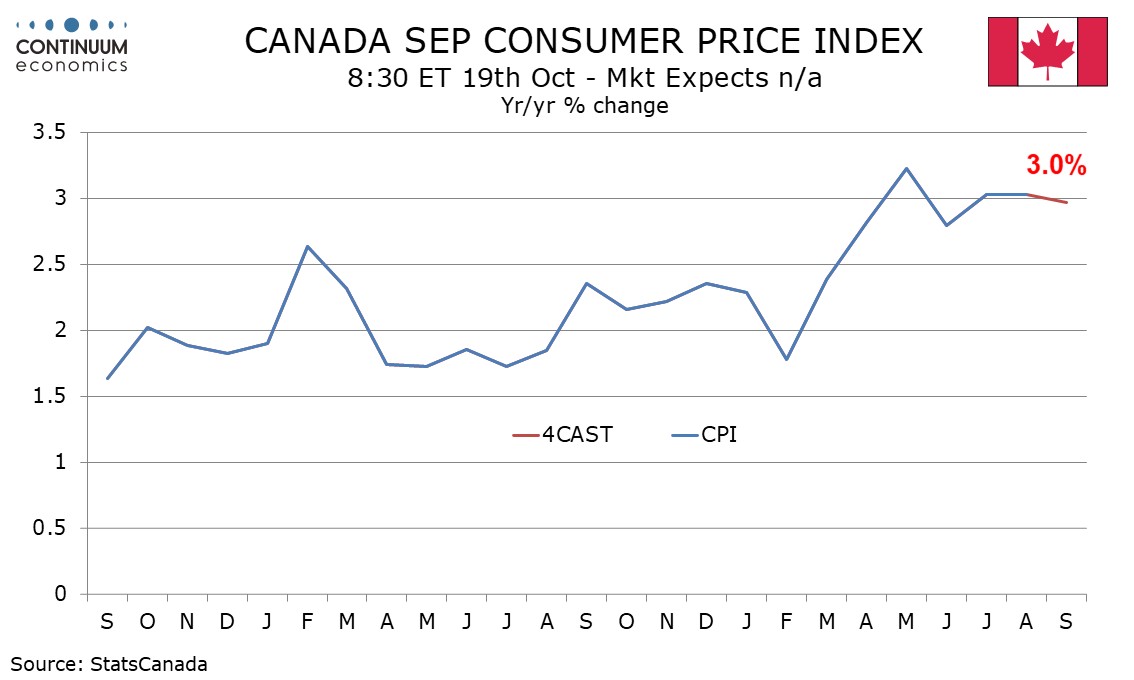
Canada’s key release will be October CPI on Monday. We expect the overall rate to remain at 3.0% yr/yr but with a slight slowing in the Bank of Canada’s core rates. Thursday sees October’s IPPI and RMPI. August retail sales are due on Friday. The preliminary estimate made with July’s data was for a 1.3% increase.
Eurozone
The service and manufacturing flash PMIs for October will be the key data points for next week. In the manufacturing sector, AI infrastructure and defence-related spending (mainly Germany) are likely to help order books stable, providing an offset to weakness in the auto sector. Services recovered strongly in September and some moderation might be in order given the recent deterioration in business confidence.
ECB President Lagarde participates at the IMF annual meeting in Thailand over the weekend.
UK
Inflation and labour market data are the main focus next week with both releases providing insights into whether the energy shock is filtering through to the broader economy.
Headline annual inflation rose to 3.1% in August and a further jump to around 3.4% is expected in September given the renewed increase in energy prices over the past two months. Core inflation has been steady at 2.6% since May. CPI will be the last piece of the puzzle before the MPC meets in November.
Tuesday sees the release of August labour market data with analysts looking for any signs of second round effects in the earnings data. Average earnings excluding bonus payments has slowed to 3.5% y/y in July from 4.7% last August as the labour market continues to shows signs of softening. HMRC payrolls data for September should show a further month on month decline.
BoE Governor Bailey and hawkish MPC member Mann speak at separate conferences on 22nd October.
JP
Japan sees Sep trade data Wednesday and nationwide CPI on Friday.
NZ
Q3 CPI Thursday the main event prior to the next ‘open’ policy meeting
AU
Quiet week with RBA speakers Hauser and Kent the main interest.