UK Growth Resilience Continues in August
In the event, growth did not contract by 0.1% m/m as consensus had expected, but grew 0.1% in August. While the month-on-month number can be volatile, the more reliable 3-month measure is showing the economy is proving to be a lot more resilient than many had expected. The better growth outturn along with hot headline inflation and recent commentary from BoE policymakers is likely to make the November MPC decision a difficult one for the doves in the committee. The market is now pricing in a 90% change of a 25bp hike in November. Today’s number means that Q3 GDP, when it is released on November 12th, is likely to show decent growth.
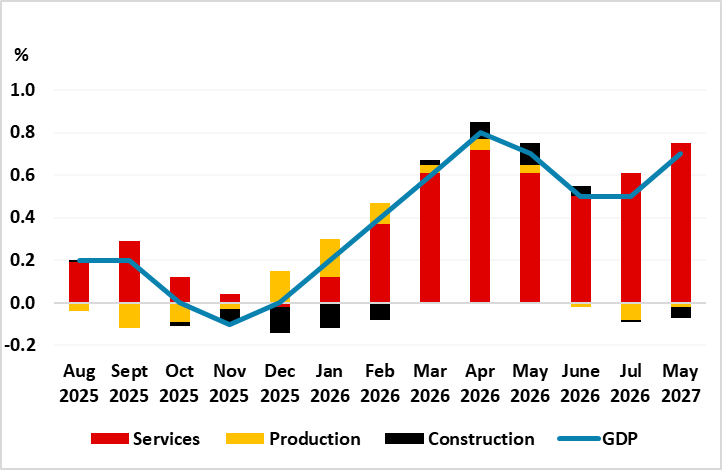
Today’s 0.1% month-on-month gain was driven by a large gain of 0.8% in production, no growth in services and a contraction of 0.2% in construction. But the stronger monthly gains recorded in June and July (both 0.4% m/m) along with today’s increase, means that the three-month measure of GDP - a more reliable measure of trends - increased by 0.7%. As with recent data, the service sector is contributing the bulk of the increase in growth and as the ONS release points out the 3 main sectors within Services seeing the strongest activity were professional, scientific and technical activities, and information and communication. AI is evident in the GDP growth figures.
The economy is proving to be more resilient than expected despite the strong headwinds faced by households given rising inflation and higher borrowing costs. Households may be riding these headwinds by reducing savings; so far in 2026, we have seen the household saving rate fall from 9.5% to 9.0%. Beyond the summer months it is likely that rising inflation and higher mortgage costs will weigh on household budgets. Slower wage growth and falling employment numbers are also likely to weigh on consumers.
Given that backdrop, Hugh Pill, who voted for a hike at the recent meeting, is likely to do so again in November. But he was keen to point out that a hike next month should not be interpreted by markets as the start of a long series of increases. "We shouldn't give the impression that because we act now, we are on another staircase ... like we saw in 2022 and 2023. It's a different shock."
As for the rest of the committee, today’s figures will embolden hawkish sentiment among policymakers by reinforcing the view that the economy is strong enough to withstand a rate rise, making a November a live meeting.
Figure 1: 3 months to August 2026 compared to 3 months to May 2026
Source: Datastream/CE