U.S. September CPI - Makes a case for tightening, will Warsh?
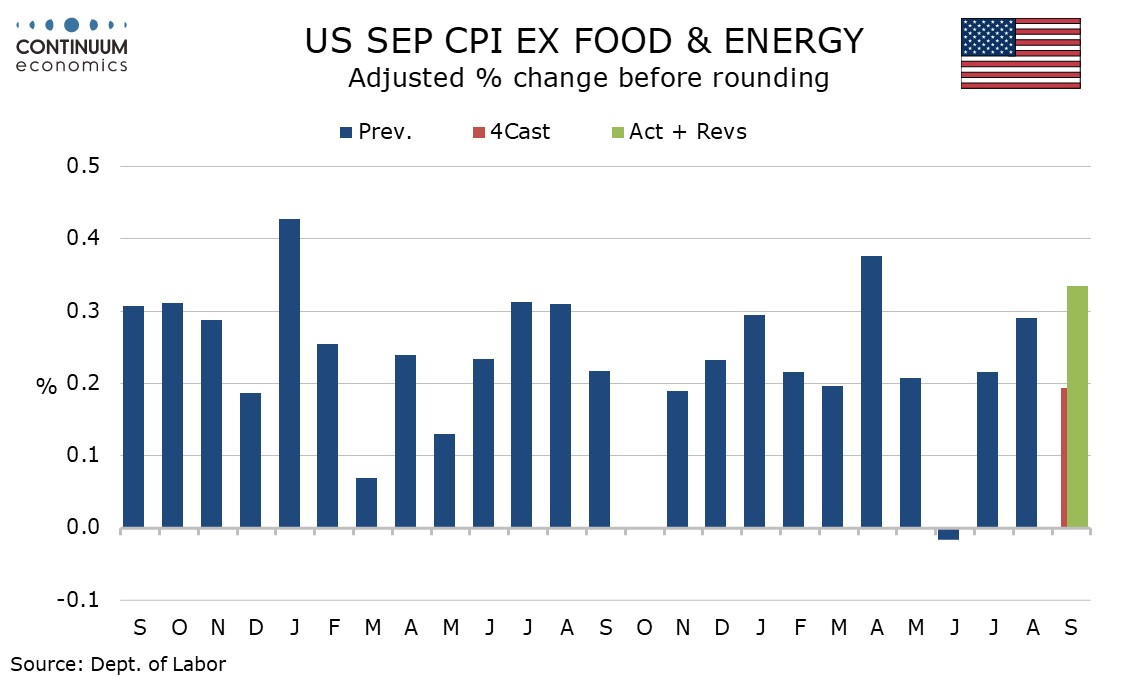
September’s core CPI is stronger than expected at 0.3% and at 0.335% before rounding a clear disappointment, with the strength broader based than August’s 0.29% when almost 0.1% came from what has proven a one-time bounce in telephone services. Overall CPI rise by 0.6% as expected, but was 0.649% before rounding, so came very close indeed to an upside surprise.
This is a number that will allow those who favor a rate hike in October to make a strong case, while those at the Fed who had seen recent data as encouraging, notably Williams yesterday, will find that their case has been undermined. There are those at the Fed, such as Waller, who are looking to tightening further but not necessarily at successive meetings. This data leaves a strong case for tightening, and it is now a close call whether it comes next in October or December. We will decide whether to adjust our call that it will be December after Warsh speaks early on Friday in Thailand.
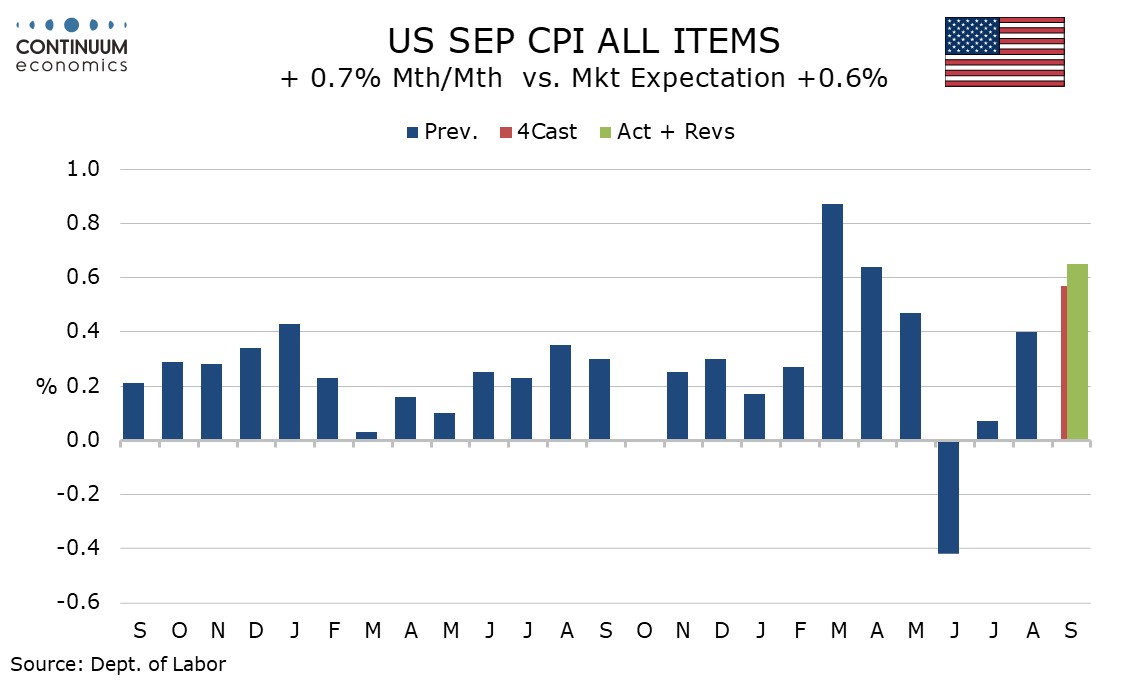
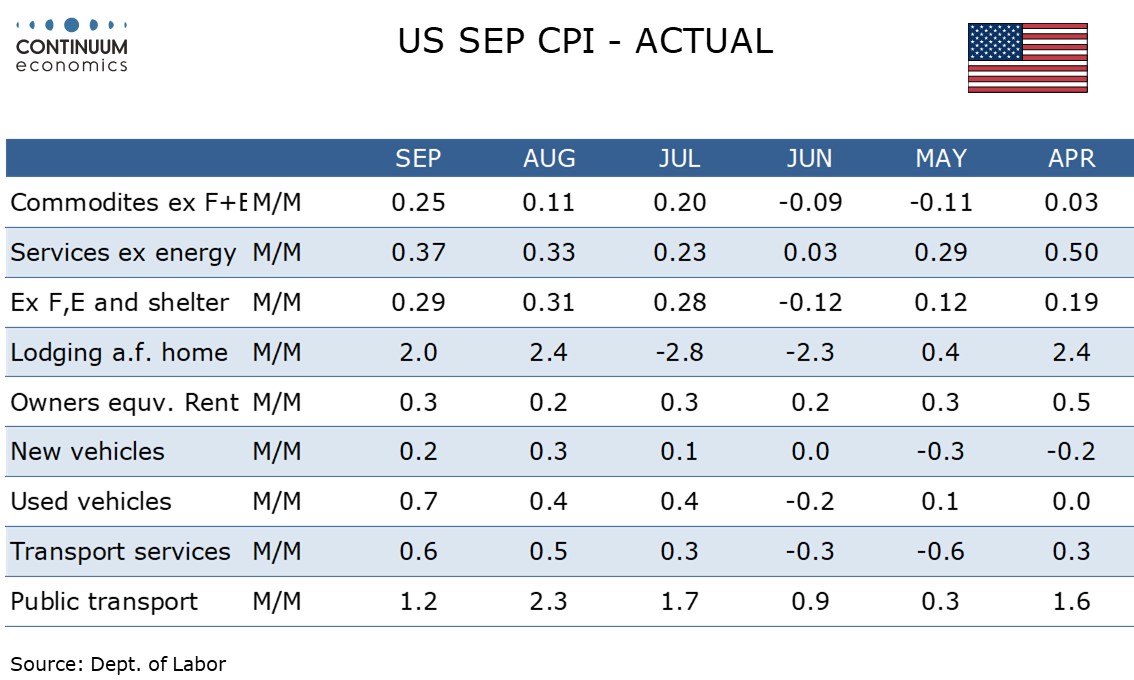
Commodities less food and energy at 0.251% and services less energy at 0.369% are both uncomfortably firm. The former is the strongest since February 2025 and the latter exceeded this year only by April (when housing saw catch up from price gains that were missed in the government shutdown) and January (the new year often sees one-time gains). CPI ex food, energy and shelter rose by 0.29% and this is a third straight month very close to 0.3%.
Used autos with a 0.7% increase are the most obvious standout on the upside in the core commodities detail though there is a so a downside standout with a 0.7% decline in medical commodities showing that strength is not confined to autos.
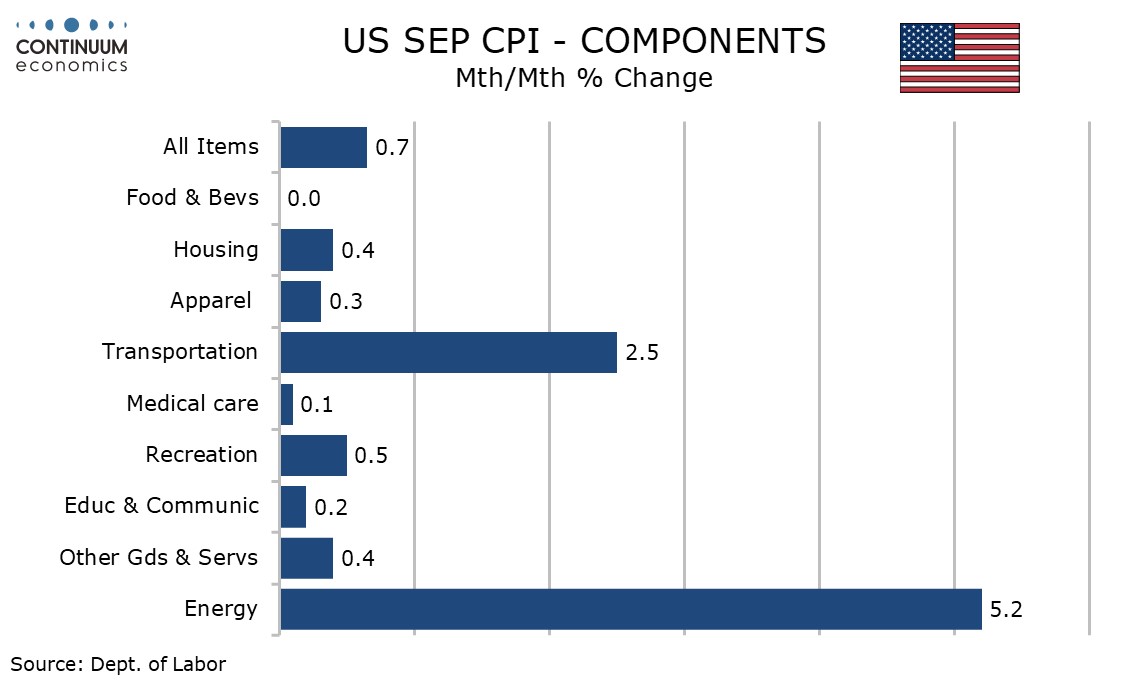
Core services saw lodging away from home firm at 2.0%, a second straight strong gain after two straight similar declines, though housing also saw support from owners’ equivalent rent that was very close to 0.35%. Air fares were up by 1.2% but this is a slowing from 2.7% in August, but transport services still accelerated to 0.6% from 0.5% after motor vehicle insurance edged up by 0.1%, breaking a recent negative trend. Telephone services fell by 0.1% after a 5.4% August surge.
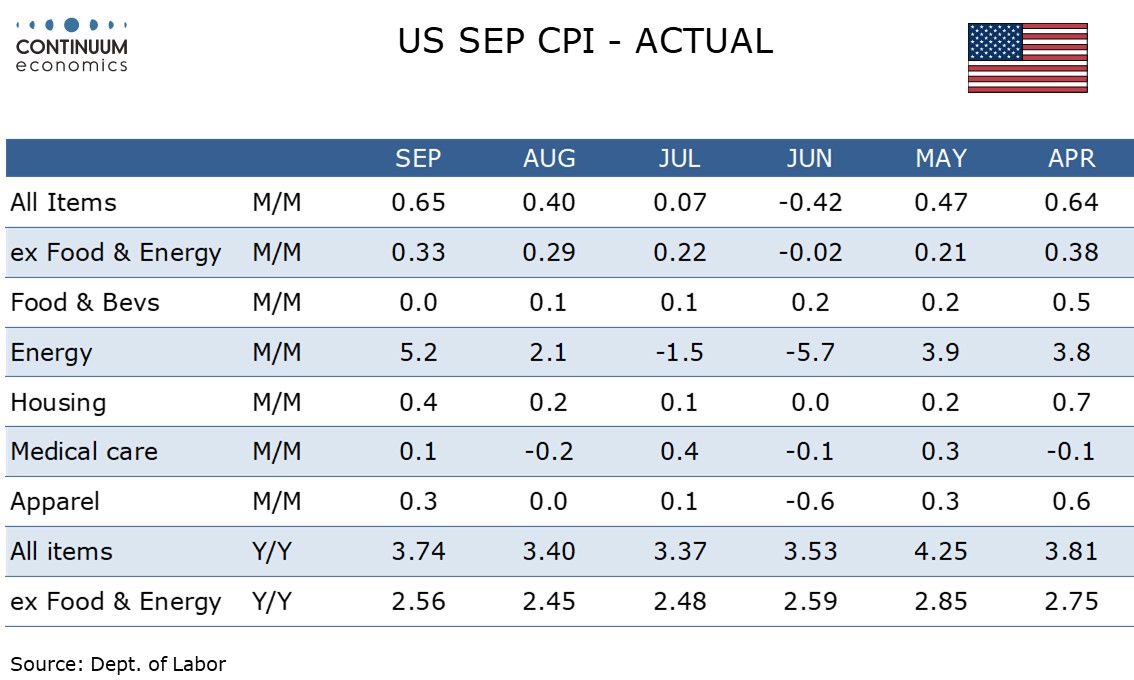
Energy was firm at 5.2% led by a 9.1% rise in gasoline but food was subdued, with an unchanged outcome.
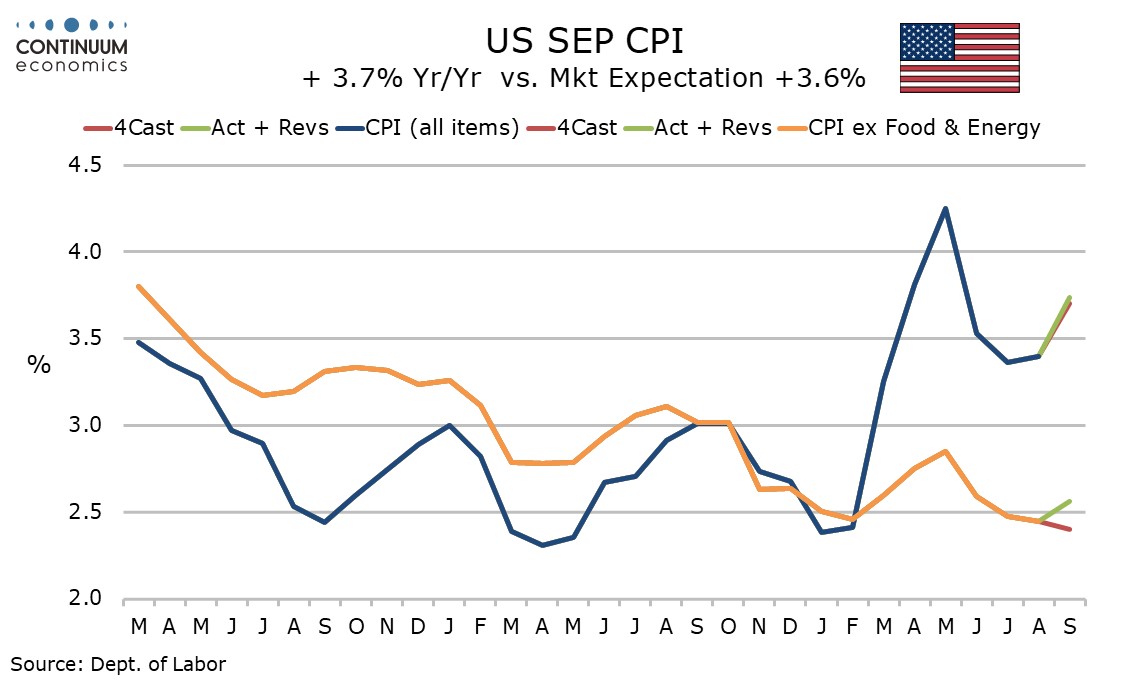
Yr/yr CPI at 3.7% from 3.4% is a 4-month high while the ex food and energy rate rose to a 3-month high of 2.6%, picking up from 2.4% in August which was the slowest since March 2021. The case that core inflation was trending towards target looked stronger after August’s data than it does after September’s.