U.S. October CPI - 50bps now set to be debated at December FOMC
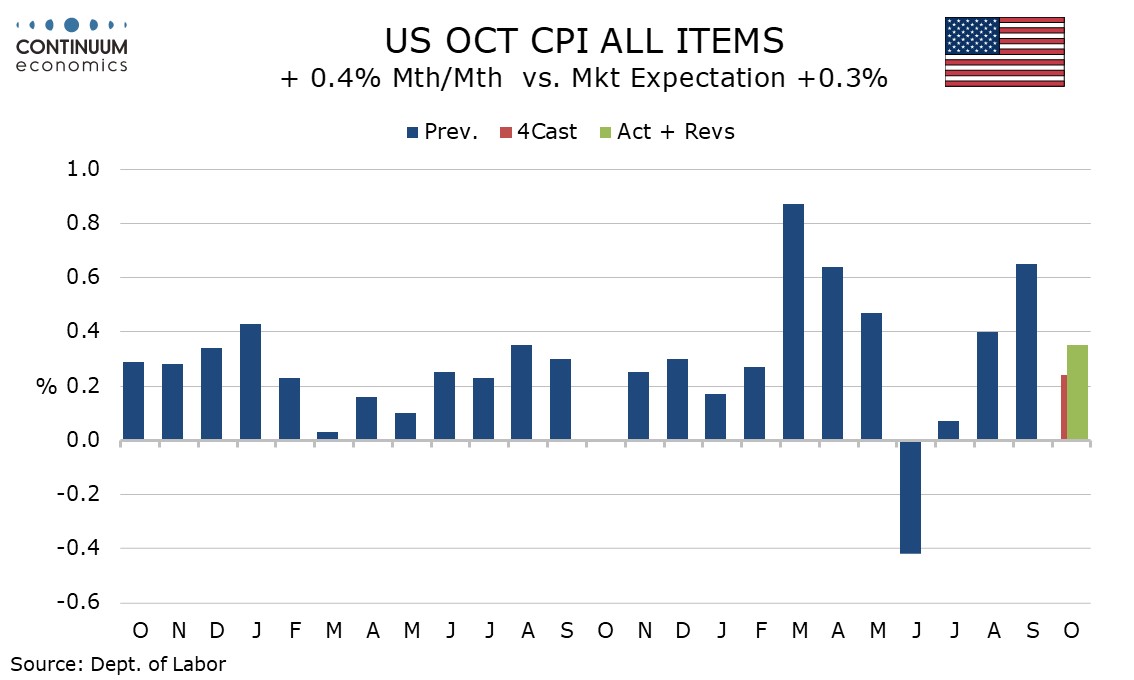
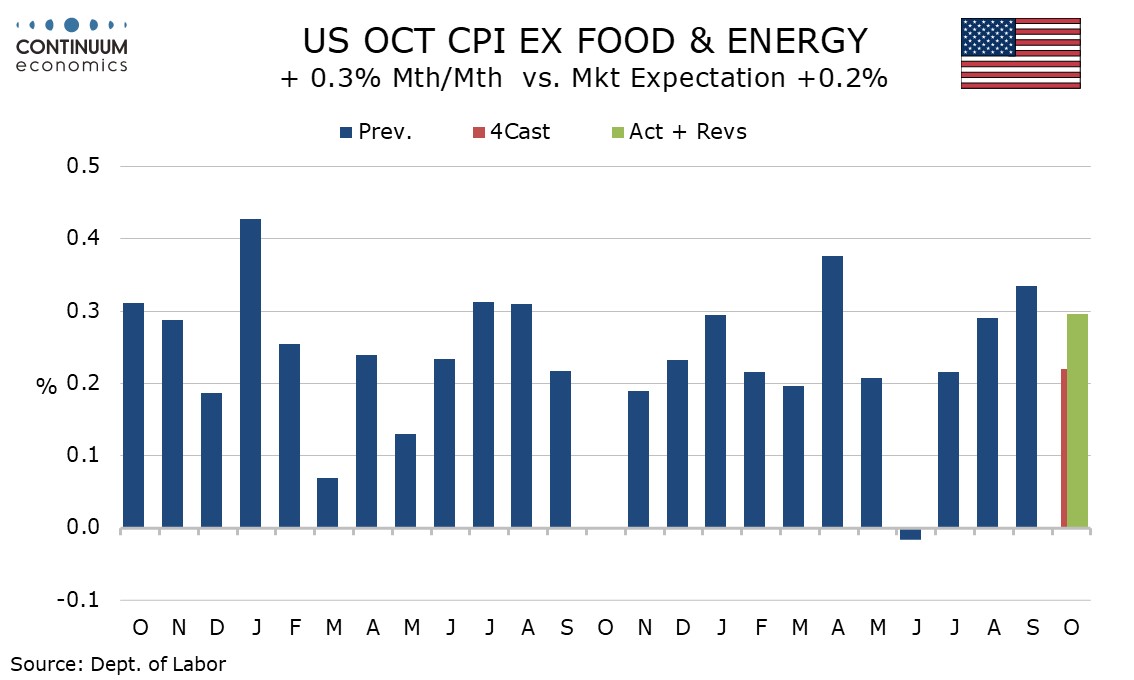
October CPI has come in stronger than expected at 0.4% overall with a third straight 0.3% rise in the core rate ex food and energy. Earlier today Fed’s Waller suggested that a 0.3% core increase would justify a 50bps tightening in December. That looks sure to be debated, particularly after October’s strong payroll. This is the last CPI release before the December 9 FOMC meeting, though November’s non-farm payroll will be released on December 4.
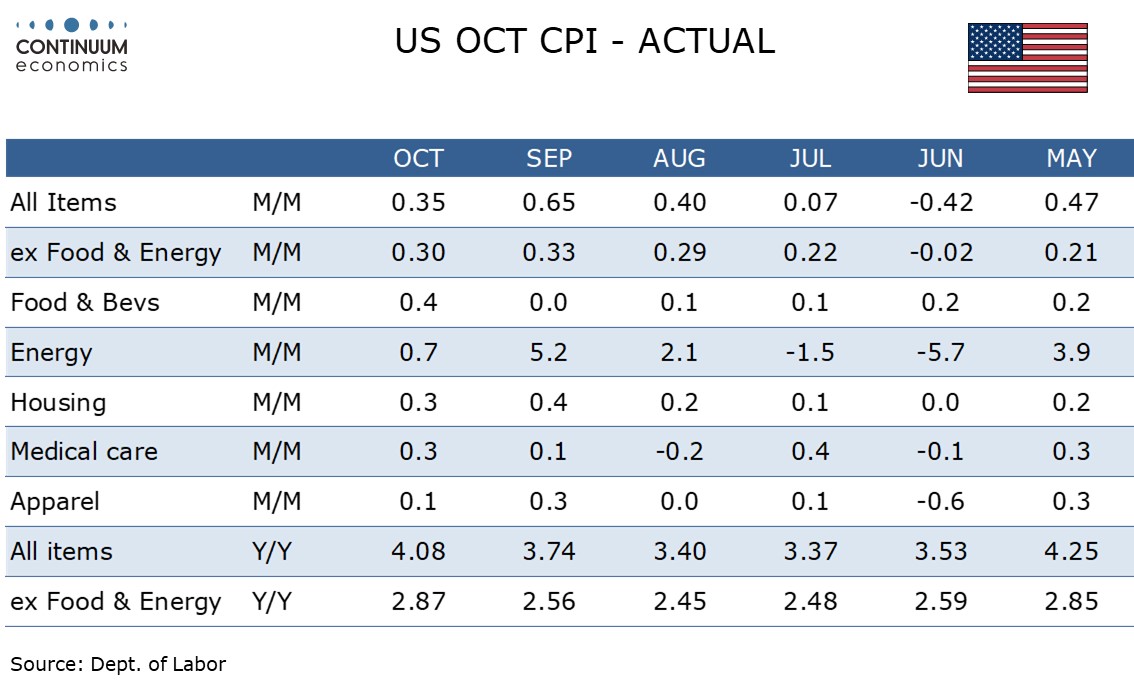
The core rate rose by 0.296% before rounding, not quite as strong as September’s 0.335% but the gain clearly suggests inflation running above target. Overall CPI was close to 0.35% before rounding. There are no yr/yr rates published because there was no survey in October 2025 due to the government shutdown. Gains from September 2025 are 4.0% overall and 2.9% ex food and energy seasonally adjusted.
Energy rose by 0.7% with gasoline up 1.0%. Coming months may see some slippage in energy. Food saw a strong month at 0.4% after five straight subdued months no higher than 0.2%.
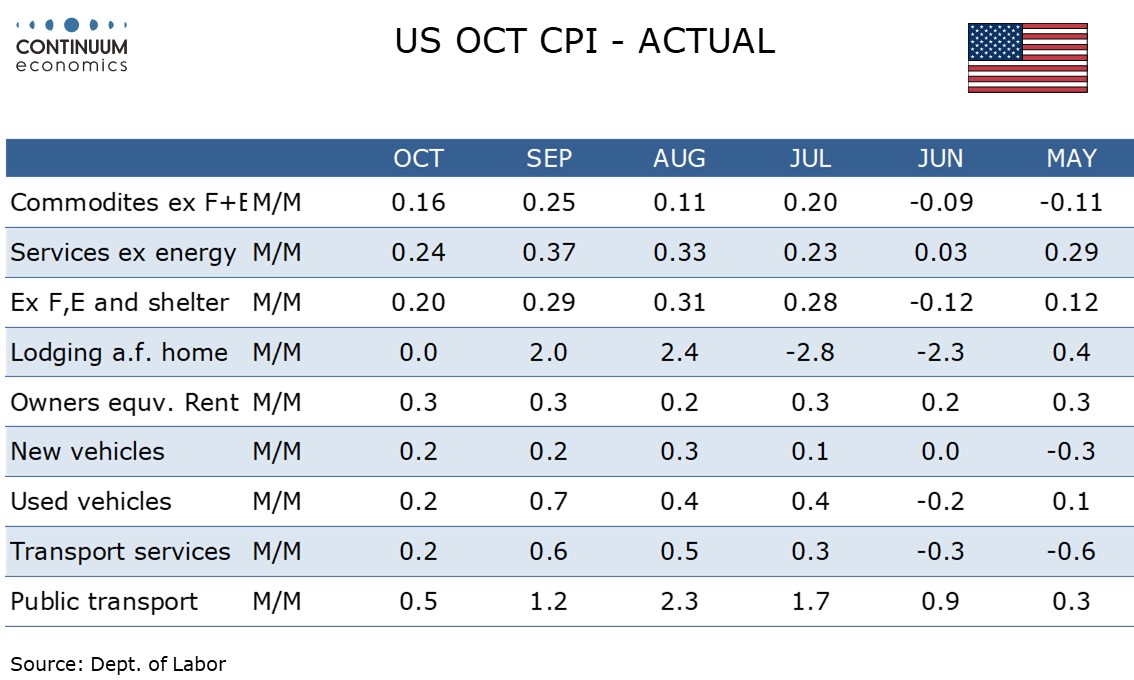
Commodities ex food and energy rose by 0.2% despite a significant 1.2% decline in used autos which corrected strength seen in recent months. Strength was seen in household furnishings and supplies at 0.7%, medical care commodities at 0.5%, recreation commodities at 1.8% led by revisions and other video equipment, and education and communication commodities at 0.5%. That is not a short list.
Services less energy rose by 0.3% for a third straight month. Transportation services were particularly firm at 0.8% led by intracity transportation. Auto services also outpaced a modest 0.4% rise in energy-sensitive air fares. Recreation services rose by 0.9%. Shelter rose by a moderate 0.3%, with lodging away from home at 0.6%, far from an exceptional rise given the volatility of that series.
Given Waller’s comments it looks clear that on December 9 the FOMC will be debating between a 25bps tightening and 50bps. Waller did not sound impressed by the recent correction lower in oil. We have not yet revised our call for a 25bps move but will be watching to see how other FOMC speakers react to this data, while FOMC minutes from October’s meeting are due on November 18.