SNB: Keeps Rates Unchanged - in no Rush to Hike
Yesterday’s announcement left the SNB on hold at 0% while nudging its inflation forecast modestly upwards and dialling down its threat of intervention as a weakening in the Franc prompted it to pivot towards more vigilance on inflation. The market expects the SNB to hike early next year but we see little reason for the SNB to change its policy rate, particularly if global energy prices eventually decline. For the SNB to hike it would need to see Core and Service sector inflation move higher, for evidence of second round effects manifesting themselves in higher wage growth and for the CHF to weaken noticeably.
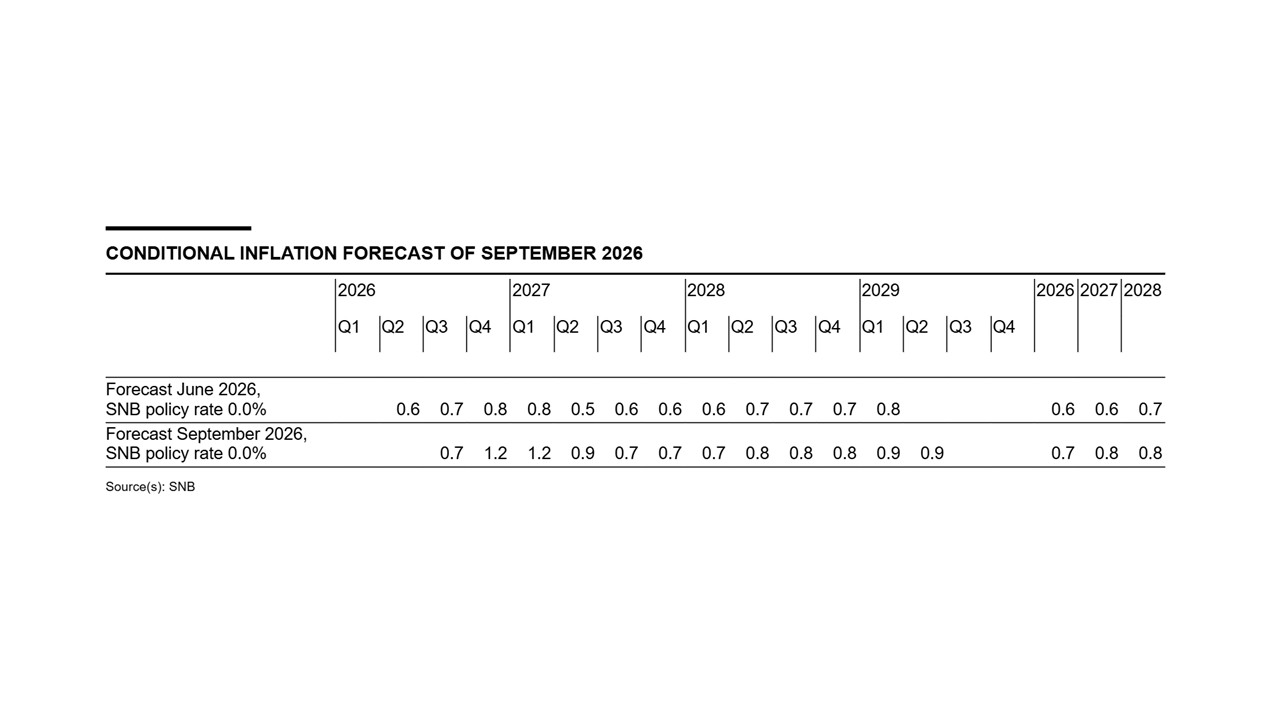
The September quarterly assessment saw a modest upgrade to the inflation with average annual CPI now roughly +0.1 percentage points higher in each of the years out to 2028. The updated forecast now sees headline inflation at 0.7% this year instead of 0.6% (see Figure 1) while growth is now expected to be between 1.5% and 2%, above June’s prediction of “around 1%”. The SNB continues to expect growth of around 1.5% for 2027
The upgrade in growth is a result of the stellar boost in Q2 when activity increase by 1.5% q/q driven by a robust performance in the chemicals/pharmaceuticals industry of 10.5%. That sector overstated the underlying growth momentum though even without this effect, growth was solid and broad-based. At the same time, capacity utilisation was below average, especially in manufacturing, while unemployment rose again somewhat through to early summer.
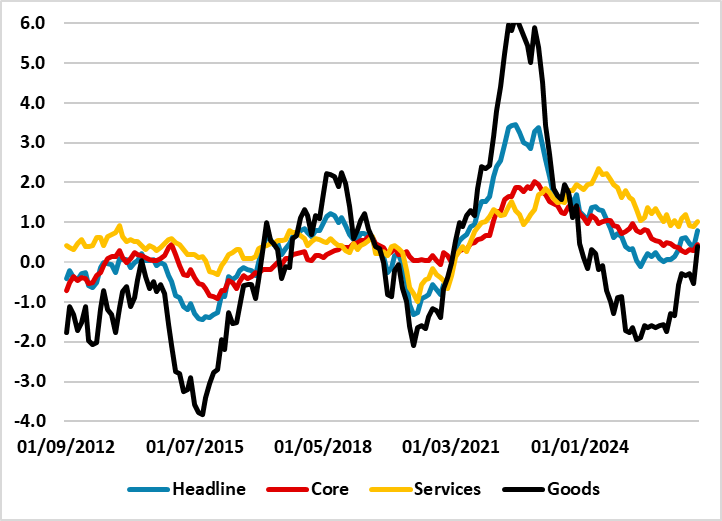
The upward revision to the inflation projection is due primarily to energy costs, and this has been reflected in an increase in Goods inflation, which in August saw its first positive print in over 2 years (Figure 2). Underlying inflation remains low, domestic price pressures are contained and the pass-through from the energy shock remains limited.
The SNB’s conditional forecasts show that inflation will continue to increase in coming quarters, before declining in the first half of 2027. The Bank expects that the energy prices will ease over time.
The market expects the SNB to hike early next year but we see little reason for the SNB to change its policy rate, particularly if global energy prices eventually decline. For the SNB to hike it would need to see Core and Service sector inflation to move higher, for evidence of second round effects to manifest themselves in higher wage growth and for the CHF to weaken noticeably.
Figure 1: SNB Inflation Outlook Little Changed
Source: SNB
Figure 2: Inflation Driven by a Pick up in Goods
Source: Datastream/CE