ECB Minutes Showed Unanimous Support for September’s hike
Minutes to the September meeting at which the deposit rate was increased by 25bps to 2.75% was backed by all members of the committee. The next meeting takes place in October 29th and it’s unlikely that the macro picture will have changed much in the next three weeks. One obvious discussion point at the October meeting, however, will be the rise in government bonds yields, the fiscal situation in France and the extent to which rising yields are weighing on growth and inflation.
At this stage markets see a low chance of a hike in October and a 70% chance of an increase at the December meeting. We continue to expect the Bank to lift rates to 2.75% before this year is out while the market is now fully pricing in a hike by February of next year.
The minutes suggested that while future policy decisions will remain “data-dependent and meeting-by-meeting,” with no pre-commitment to a particular path, the repricing at the long end, “provided it remained orderly,” was supporting the intended monetary policy stance and “could have implications for appropriate policy rates in the future.” That view was repeated by Lagarde this week when she noted that “while growth has been resilient, since our last meeting long-term interest rates have risen notably, which will slow growth and reduce pass-through by more than projected in our September exercise”.
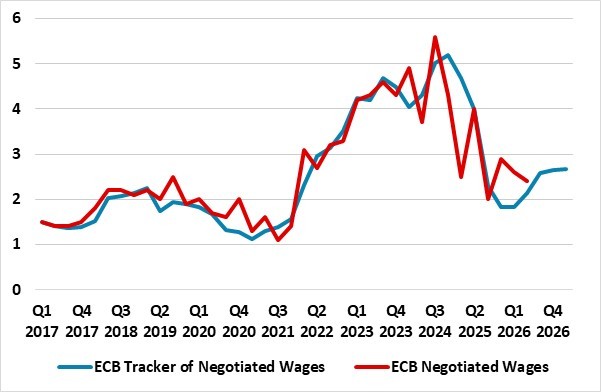
On inflation, members “largely agreed” that the inflation outlook had deteriorated with the September staff forecast pointing to inflation staying above target for longer than previously expected. Inflation could also turn out higher if the effects of the energy shock on other prices and wages were stronger than currently expected. Turning to underlying inflation, most measures had been broadly stable in July. Although all measures continued to stand above 2%, underlying inflation was judged to have remained contained so far. Lane commented this week that energy prices are high but the strength of the pass-through to the rest of the economy remains uncertain though “some” pass through to core from energy is likely next year. On the risk of wage-price spiral, Lane also said “we have not seen so far very strong second-round effects”. Recent labour market continues to show moderating wage growth.
We suspect October’s meeting will allow the Bank room to discuss the potential implications of the recent jump in yields and how they respond at the December meeting.
Figure 1: ECB Negotiated Wages Remain Contained
Source: Datastream/CE