USD Focused on CPI, EUR on 2027 French Budget
• USD: CPI and U.S. Treasuries
• EUR and The French Budget Debate
• CHF, JPY and GBP: different safe havens from 2010-12
• AUD Underappreciated by FX not Rates
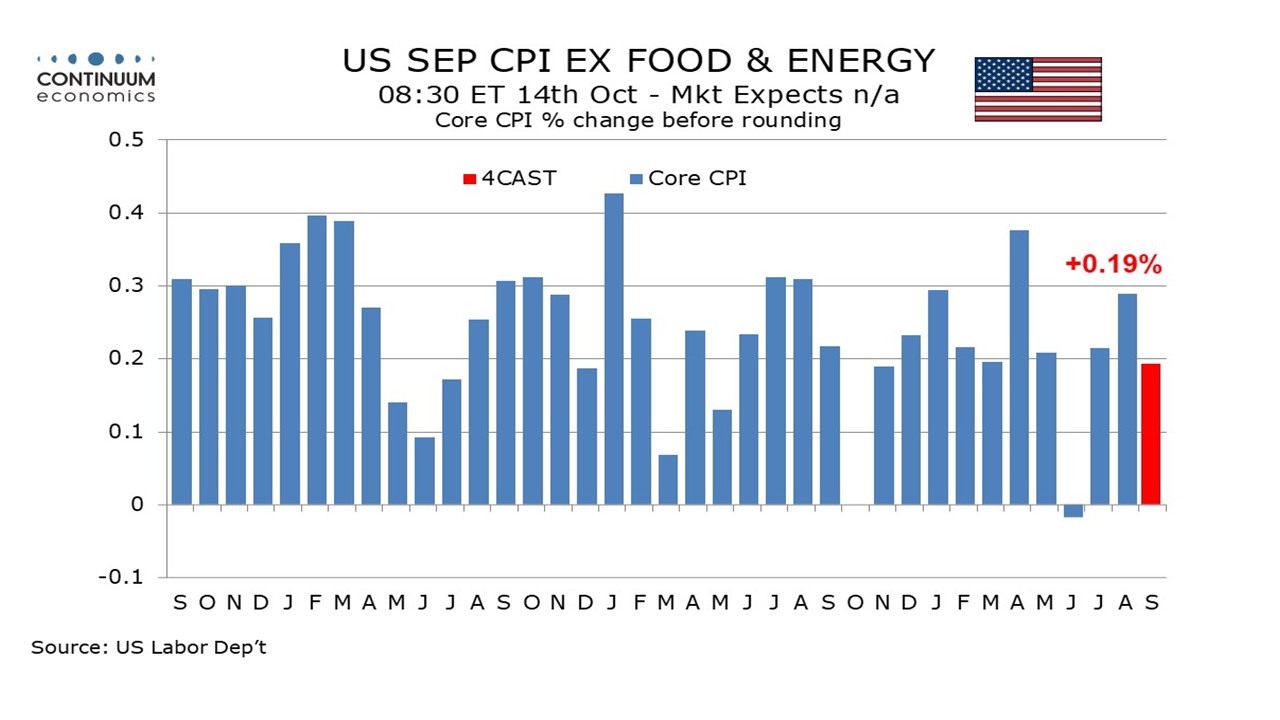
September U.S. CPI is the data highlight of the coming week and the headline will be boosted by higher Iran driven energy prices. However, the core CPI is more important for Q4 Fed policy and we look for a subdued 0.19%. This will reinforce the view that an October hike is unlikely, but that the Fed will most likely hike in December. Rate expectations for 2027 may not change much in the remainder of the month, though we still think a further modest correction lower in U.S. Treasury yields could be seen (here) and this could be a headwind for the USD generally this coming week and cause small/modest intermittent corrections.
 Meanwhile, the USD has not been moved by President indicating that the U.S. would not attack Iran before the mid-term elections. The FX market had a certain degree of scepticism that the previous threats were just an attempt to act tough with Iran without launching a new phase of the Iran war. Indeed, we still feel that Trump could claim a breakthrough in peace talks just before the November mid-term elections. This is all an attempt to deflect blame and get a temporary dip in oil prices. On oil prices, the new Houthi attacks last week have kept oil prices high, but the recent increased flows through the Straits of Hormuz have helped cap oil prices and could be more important multi week.
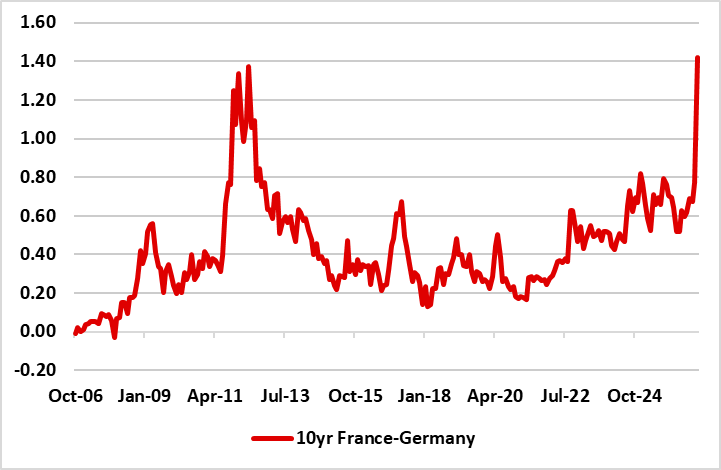
The other big event this week is the start of the 2027 French budget debate, with the 10yr France-Germany government bond spread off the September highs but still very elevated compared to experience over the last 15 years (see chart). End investors will likely be reluctant to buy French government bonds at current spreads until they can be confident that the National Rally will support the 2027 budget and this coming week could see some volatile negotiations. Failure could also trigger older investors to offload some French bonds! Despite optimism in France over the 2027 budget passage, the bond spread will not automatically narrow and movements in the 10yr France-Germany can swing the EUR not only against the USD but also on the crosses.
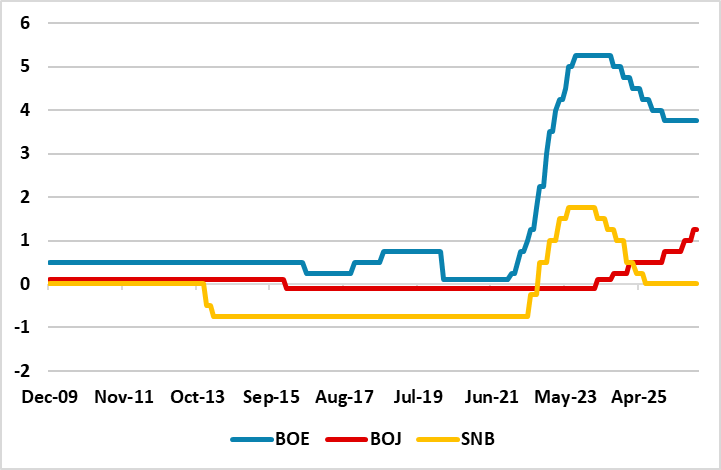
On USD/JPY, the sense is that fresh news is required to trigger a move, as both Fed and BOJ are expected to hike by 25bps in December. Most feel it will be U.S. or Japan data, with the question of key levels on USD/JPY downside also important. However, we would also point to potential jawboning from U.S. Treasury secretary Bessent who is concerned that higher JGB yields are hurting Treasuries. If he jawbones USD/JPY before the mid-terms it could help him with his demanding boss Trump. However, this is a risk more for the last week of October rather than next week. On the issue of safe havens, if the 2027 French budget fails to pass the National Assembly in the coming weeks/months, what is the best safe haven? The starting point is different from 2010-12 with UK policy rates and yields much higher that Switzerland or Japan, while Japan also now has a yield premium versus Switzerland (see chart below).
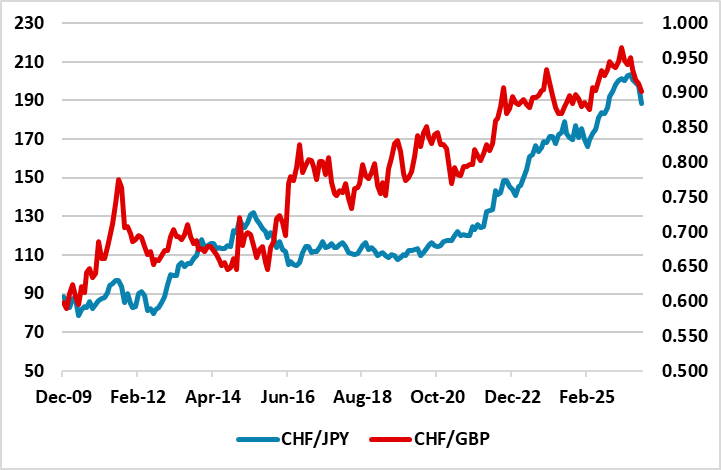 Secondly, the CHF has appreciated significantly since 2010-12 against the JPY and GBP and the CHF is overvalued. Thus though the natural knee jerk is towards the CHF in times of French budget trouble, we feel that GBP and JPY could be better beneficiaries – they could also be support by their own central bank tightening in coming months.
 France would rollover the budget like 2025/26 if the 2027 budget did not pass, but this would likely mean a 6.5% budget deficit rather than 5.4% expected for 2026. This would cause a further moderate tensions, rather than a full blown crisis.
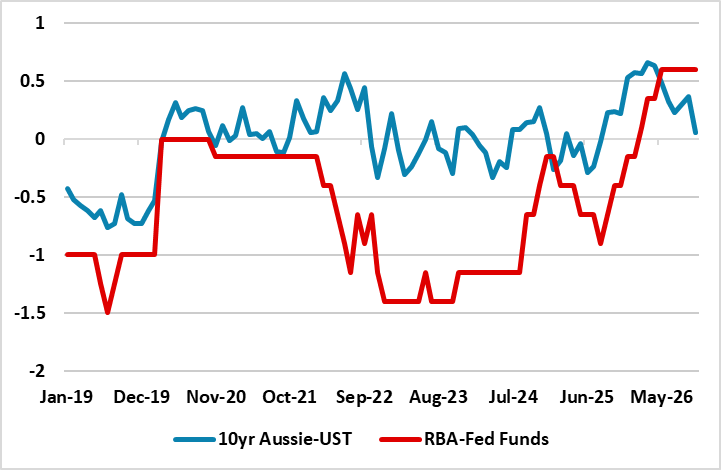
Finally, the USD rally against most DM currencies since early September has dragged along the AUD, which is little changed over the last month versus the EUR! This is typical when a larger move spill over across DM, but AUD is not the EUR. Australia has little correlation to events in France. Additionally, AUD is a DM high yielder, with the policy rate spread is favour of the RBA. Government bond markets feel that 10yr AUD yields are high enough long-term and the spread versus the U.S. has narrowed in September – see below. The FX market could come to appreciate the AUD more and one way is short EUR/AUD. Any EUR bounce should see a similar move in AUD/USD, but any further EUR selloff is unlikely to be matched by the AUD.