Riksbank: December Hike
· The Riksbank statement guidance that the 1st hike could be delivered in December is important. It suggests that the Riksbank now see modest tightening as highly likely and going in December rather than Q1 2027 would have a strong signal effect. This would also avoid too much Swedish Krona weakness, given that the ECB will likely hike again to 2.75% in December. Thus we now forecast a 25bps hike at the December meeting and a further 25bps hike at the March meeting to 2.25%. We then see a prolonged pause from the Riksbank.
Figure 1: Sweden Policy Rate Projection (%)
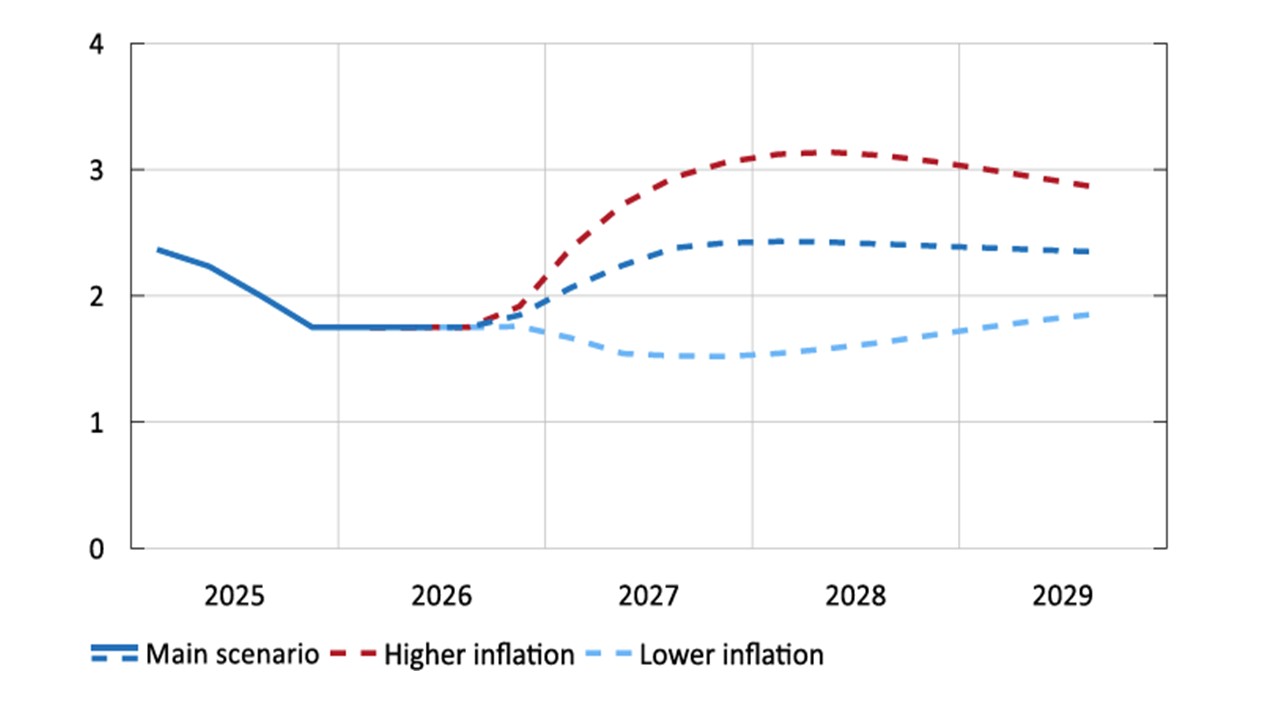
Source: September Riksbank Monetary Policy Report (here)
The unchanged Riksbank policy rate was very much as expected, but a number of points are worth noting.
· Recent data/Developments. The Riksbank raised the CPI and CPIF forecasts for 2027 to 3.2% and 2.1% respectively. In the statement the Riksbank noted that the measured rate of inflation is low largely due to the direct effects of temporary fiscal policy measures, but adjusted for these, inflation is relatively close to 2 per cent. The Riksbank are also concerned that healthy economic momentum (2026 GDP revised upwards from 2.2% to 2.8%) and the continuation of the energy shock from the Iran/U.S. war could combine to produce upside inflation surprises.
· Forward guidance. Given the upward shift in forecasts, the forward guidance was that the Executive Board assesses that the increases in the policy rate will begin this year, which makes the December meeting a live meeting (the forecast table had a 1.85% for Q4 2026, which is consistent with December). For 2027, the baseline Riksbank guidance is for 50bps of hikes, with the forecast table suggesting Q1 and Q2. The Riksbank show in the associated monetary policy report that this is consistent with the estimates of the neutral policy rate. However, the statement also makes clear that upside risks exist to inflation and this brings the alternative scenario in Figure 1 into focus. This sees faster and larger policy tightening to a 3% policy rate by end 2027. For now we would see this as a risk scenario, rather than a high probability scenario. We remain of the view that the U.S. and Iran will agree a 2nd ceasefire in Q4 2026/Q1 2027 (here). This will bring energy prices down and leave the Riksbank comfortable that modest tightening will deliver 2% inflation.
· December hike? Though the official forecast have the first hike in Q1 2027, the Riksbank statement guidance that the 1st hike could be delivered in December is important. It suggests that the Riksbank now see modest tightening as highly likely and going in December rather than Q1 2027 would have a strong signal effect. This would also avoid too much Swedish Krona weakness, given that the ECB will likely hike again to 2.75% in December. Thus we now forecast a 25bps hike at the December meeting and a further 25bps hike at the March meeting to 2.25%. We then see a prolonged pause from the Riksbank.