Preview: Due October 2 - U.S. September Employment (Non-Farm Payrolls) - Healthy if less strong than August
We expect September’s non-farm payroll to rise by 100k both overall and in the private sector, slower than in August but still maintaining a healthy trend. We expect a 4.1% unemployment rate for a third straight month but a slightly slower 0.2% rise in average hourly earnings and a stable workweek. Overall such a report would be seen as a solid one.
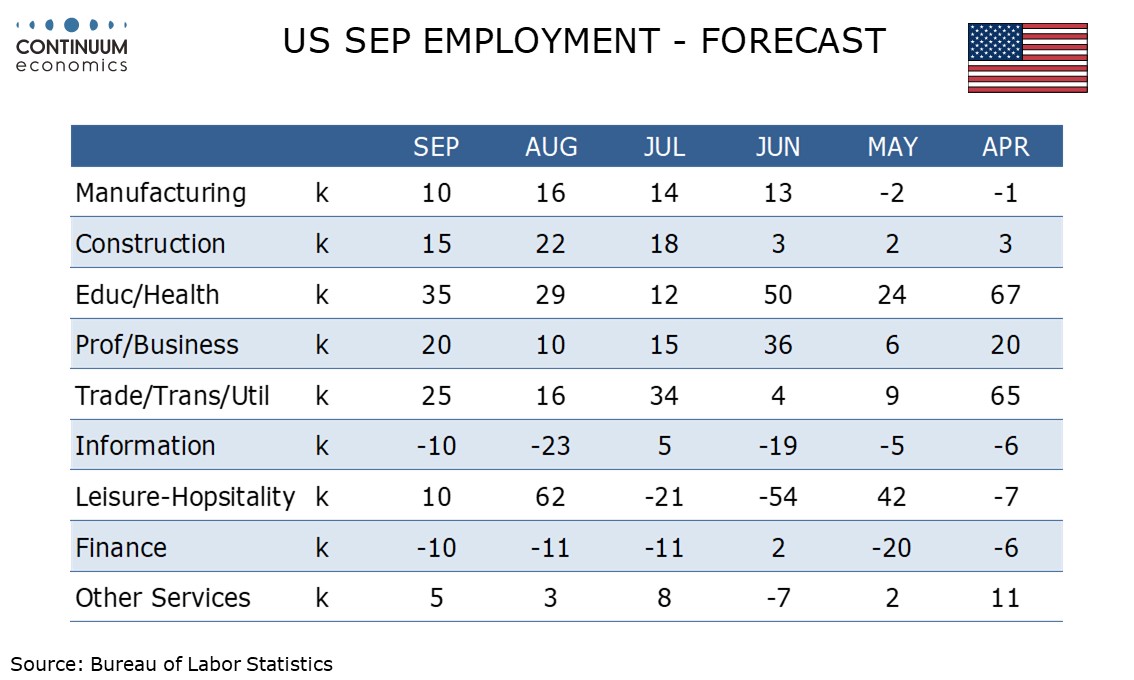
Overall payrolls have been volatile recently, with a strong rise of 162k in August following weak gains of 21k in July and 31k in June. However most of the volatility came from two components. Leisure and hospitality rebounded by 62k in August after losses of 21k in July and 54k in June. Government rose by 35k in August after falling by 50k in July (the moves led by local government education) after a modest rise of 5k in June.
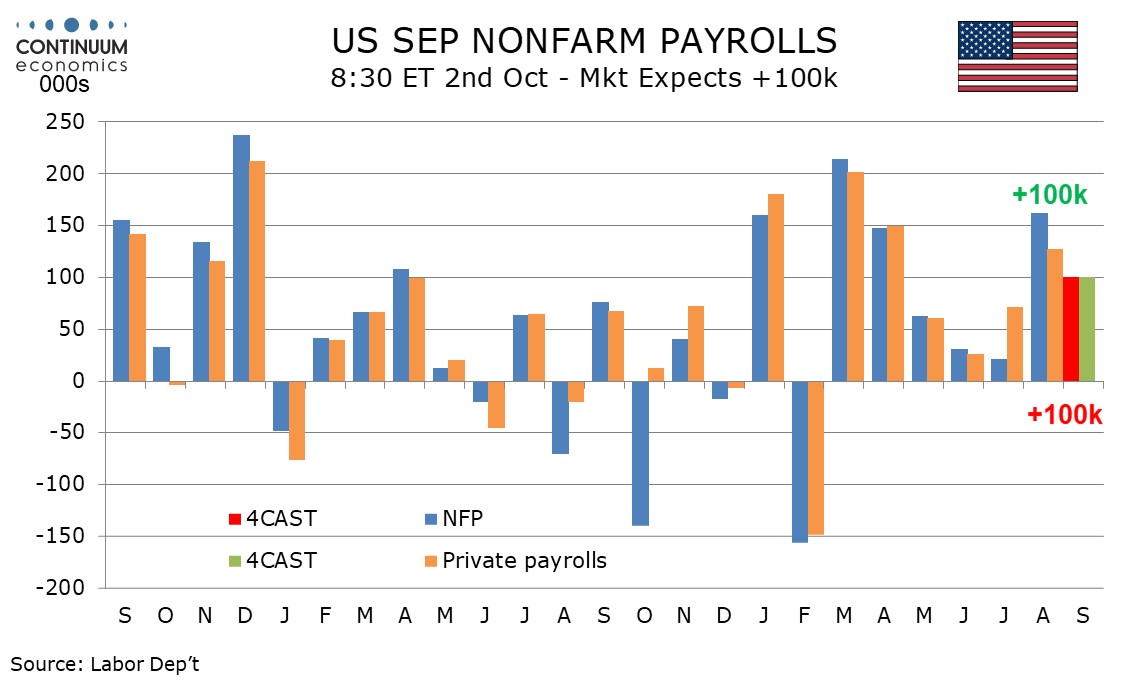
Private payrolls excluding leisure and hospitality have not seen much volatility, slowing to 65k in May after gains of 92k in July and 80k in June. Lower initial and continued claims suggest a modest underlying improvement in September, with a 90k increase excluding leisure and hospitality and government. We expect a modest 10k increase in leisure and hospitality and no change in government as both series return to trend after recent volatility.
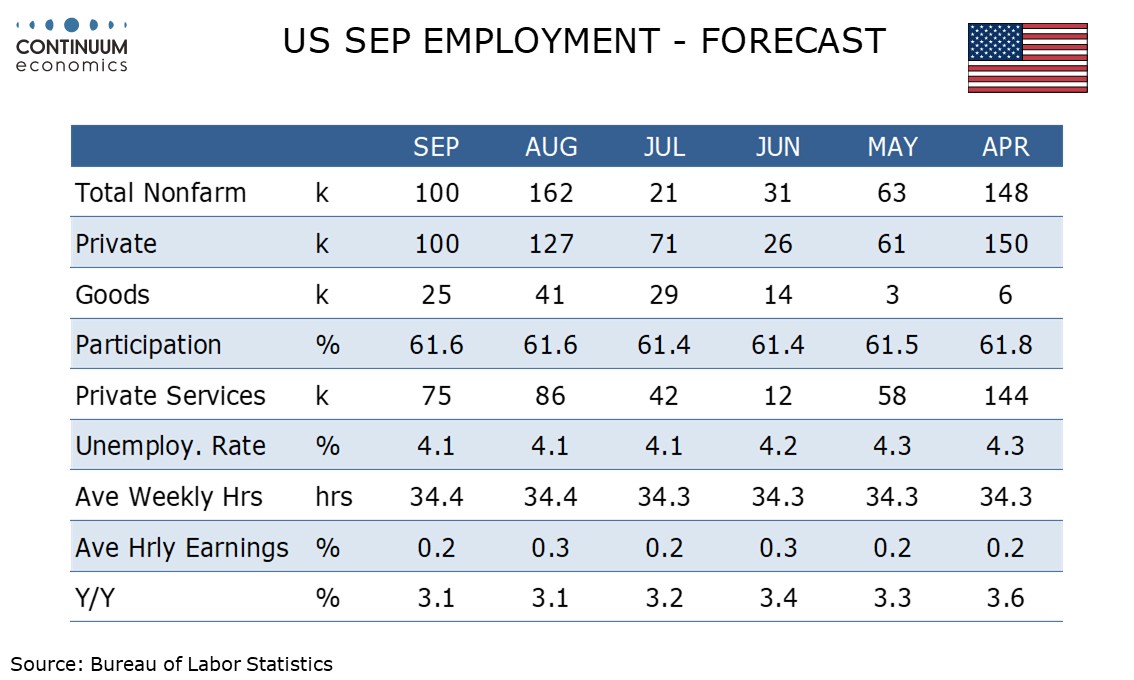
Within the private payroll detail we expect a modest slowing in goods, with manufacturing at 10k versus 16k in August and construction at 15k versus 22k in August, but improvement in services. We expect a 75k rise in private services, down from 86k in August, but we expect private services excluding leisure and hospitality to rise by 65k, well above August’s 24k but similar to July’s 63k and June’s 66k.
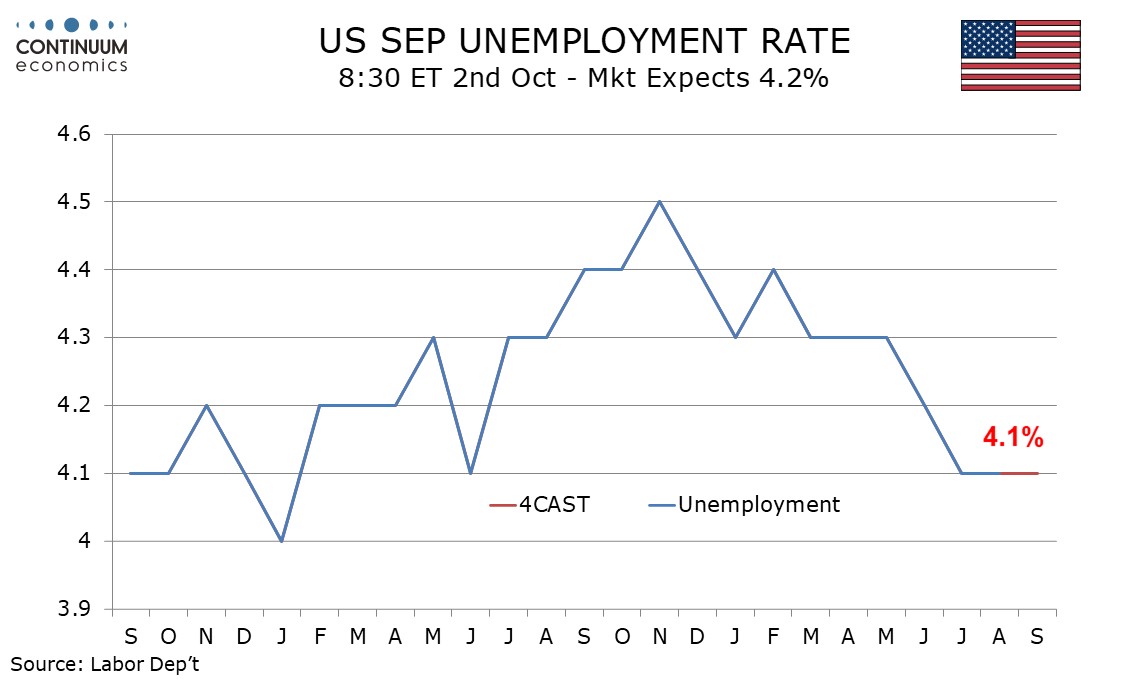
The household survey, which calculates the unemployment rate, also showed a much stronger employment gain in August, of 569k. However, with the labor force up by 683k unemployment edged up to 4.14% before rounding from 4.09% in July, though both rounded to 4.1%, and in neither case did August’s rise fully erase two preceding declines. We expect September data more in line with trend, but in seeing a 100k incase in employment and an unchanged labor force we expect unemployment at 4.08% before rounding, rounding to 4.1% for a third straight month. We expect participation to remain at 61.7%.
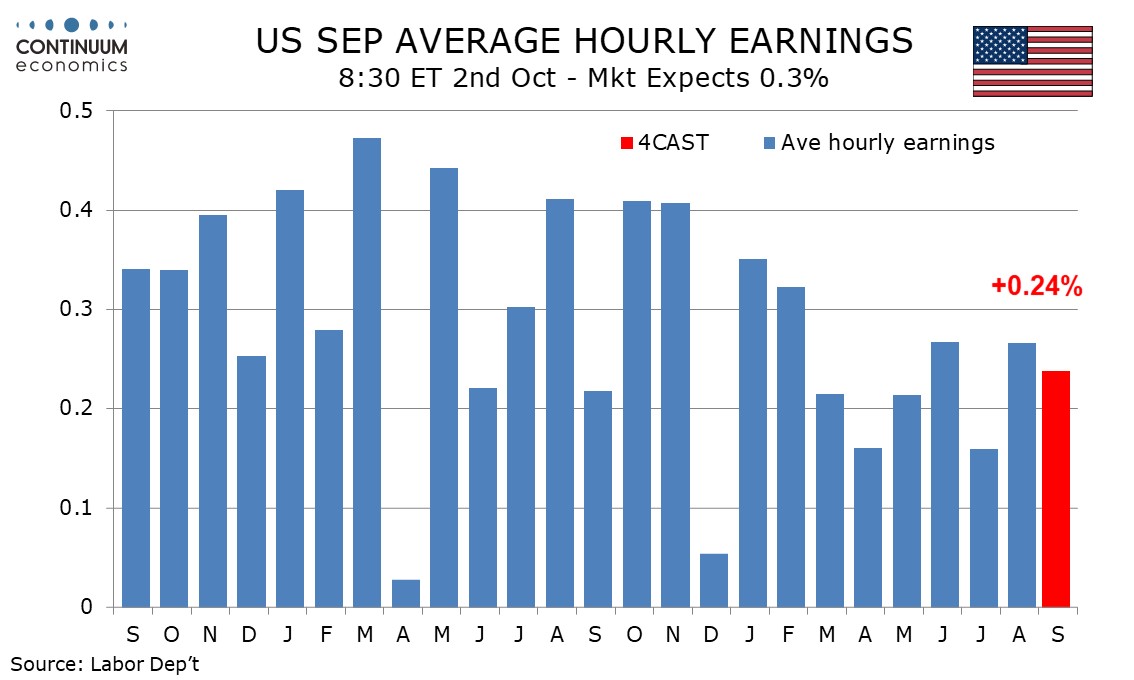
We expect a 0.2% rise in average hourly earnings after a 0.3% increase in August, but before rounding the change we expect is marginal, to 0.24% from 0.27%. Trend in average hourly earnings has slowed from a little over 0.3% per month a year ago to around 0.25%, and with unemployment low we doubt it will slow much further. We expect yr/yr growth to remain at August’s 3.1% pace, which was the slowest since May 2021.
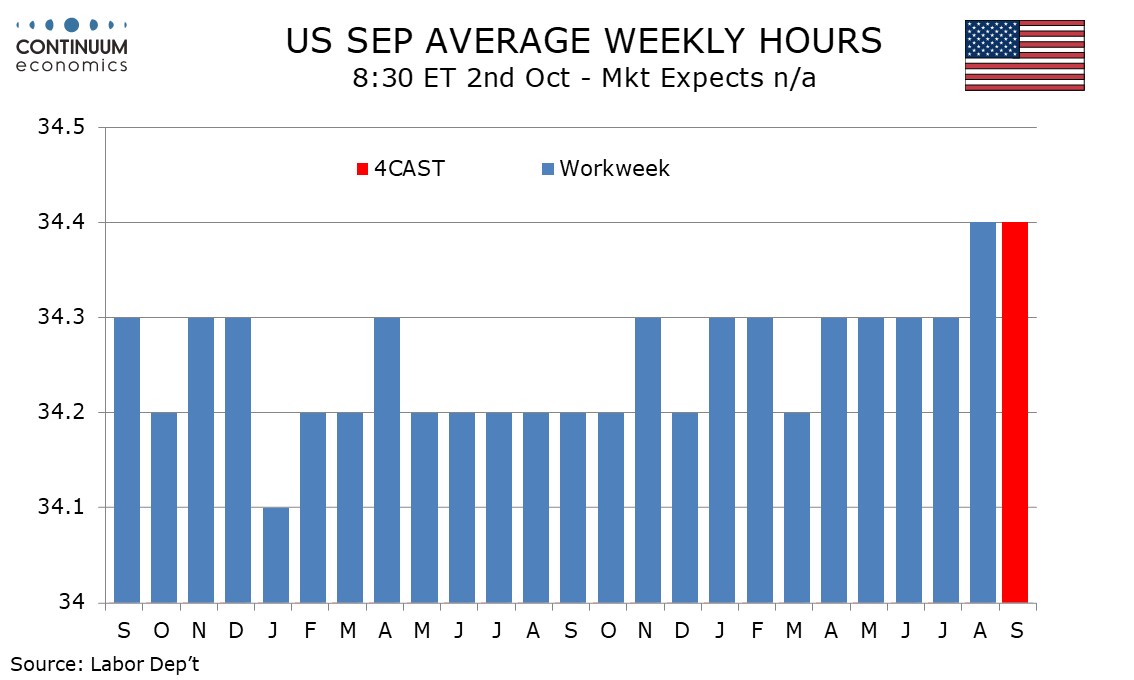
The workweek bounced in August to 34.4 hours after seeing four straight months at 34.3, reaching its highest level since March 2024. A dip back to 34.3 is more likely than a rise to 34.5, but we expect a second straight month at 34.4. That, and our payroll forecast, would leave aggregate hours worked up by 0.1% on the month and 1.5% annualized in Q3, only marginally up from 1.2% in Q2. With Q3 GDP looking set to be significantly stronger than in Q2, aggregate hours worked are likely to hold up in September.