FX Weekly Strategy: Asia, Nov 23-27
Yen remains a good risk hedge from the right position location
Need to keep an eye on shifting sands and implications for dollar's drivers
Calendar factors to keep in mind for both book and rebalancing forces
Anthropic’s suitably flashy and first-day-pump IPO launch ended up being a mere distraction from the ongoing tech/AI correction and wider Asia/China/commodity pressure theme. Moves have become significant - certainly in Asia with losses the largest since covid - so an element of froth will have unwound. The question still how much more negative follow through follows.
We still haven’t finished the “traditional” challenging Oct-Nov period yet, though Thanksgiving can sometimes end up being somewhat of a fire-break and trend-changer on big trades. Indeed, part of the recent accelerator may well be the Nov book close factor, leading to noisy position squaring and profit-taking, and resulting piggy back momentum trade. Whether this then segues to pre-positioning for a December and eventual Santa rally is the more open question.
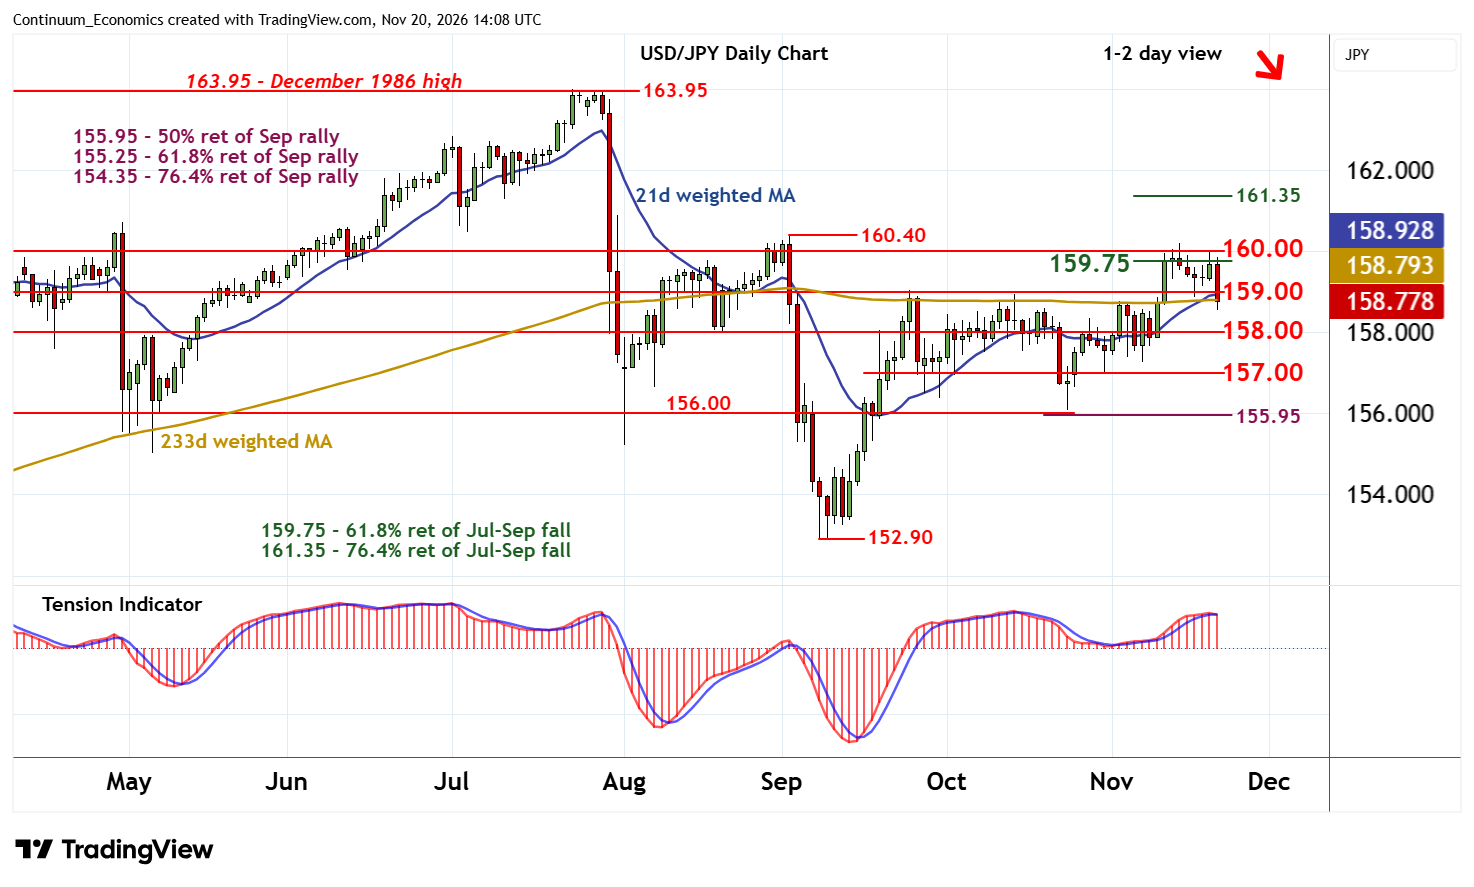
FX is at a challenging juncture too. As noted in the intraday commentary, maybe one of the more reliable trading approaches of late has been to take advantage of the interest-rate spike led yen sell off to buy as a kind of options trade hedge. The concept being MoF (and less reliably US Treasury) are the downside put protector giving a somewhat downside and volatility contained free call as a wider risk hedge. Less prosaically, USD/JPY has continued to see strong supply (and squaring impulses on intraday long) build up from 160, seeing capping and downside pressure win out.
On the charts, the pair is not looking super bearish immediately yet and is more in a range consolidation down to 158 at present.
The other big picture consideration to keep in mind is recent action is not without its consequences for questioning some of the recent driving forces. That is, while the early month developments have all been wind to the dollar’s sails, the market has now fully adjusted in terms of its Fed pricing, its more inflationary macro perspective and of course its positioning and overbought posture. This rapid adjustment has been reflected in the dollar and dollar/risks lack of additional traction through Friday’s further Asia lurch.
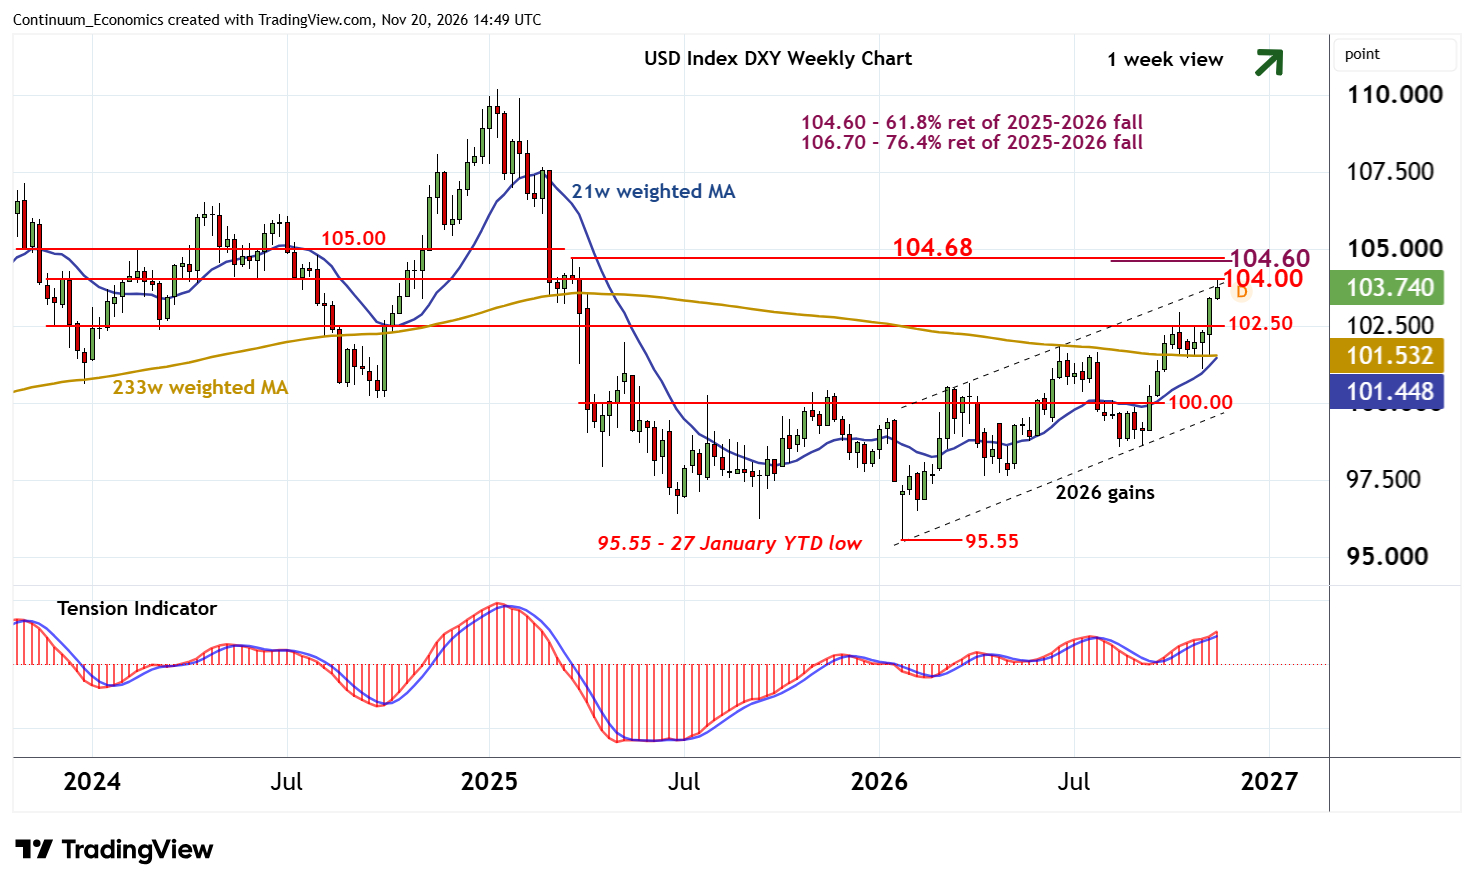
From here, and partly dependent on how far and in what style the current tech correction extends, there are reasons to remain mindful and not get too locked into the new theme and trend unquestioningly. Commodity prices have declined considerably, risk is currently retreating and indeed some US data has just started to show some possible slowing and move to downside over upside surprise. All the factors that drove the interest-rate powered dollar surge are not fixed in time, and the market could reach a point of revaluation at some stage if it starts to feel an overshoot and notice a conspicuous UST reversal and divergence.
Similarly, December can also see reserve manager passive rebalancing kick in, that can have the effect of counter-trend performance to the YTD action. This would be especially true of passive dollar gains where the bias is still diversification rather than shift to deaccumulations. So on a multi-week view, it is worth remaining live to some possible corrective forces, without rely solely on abstract factors either.
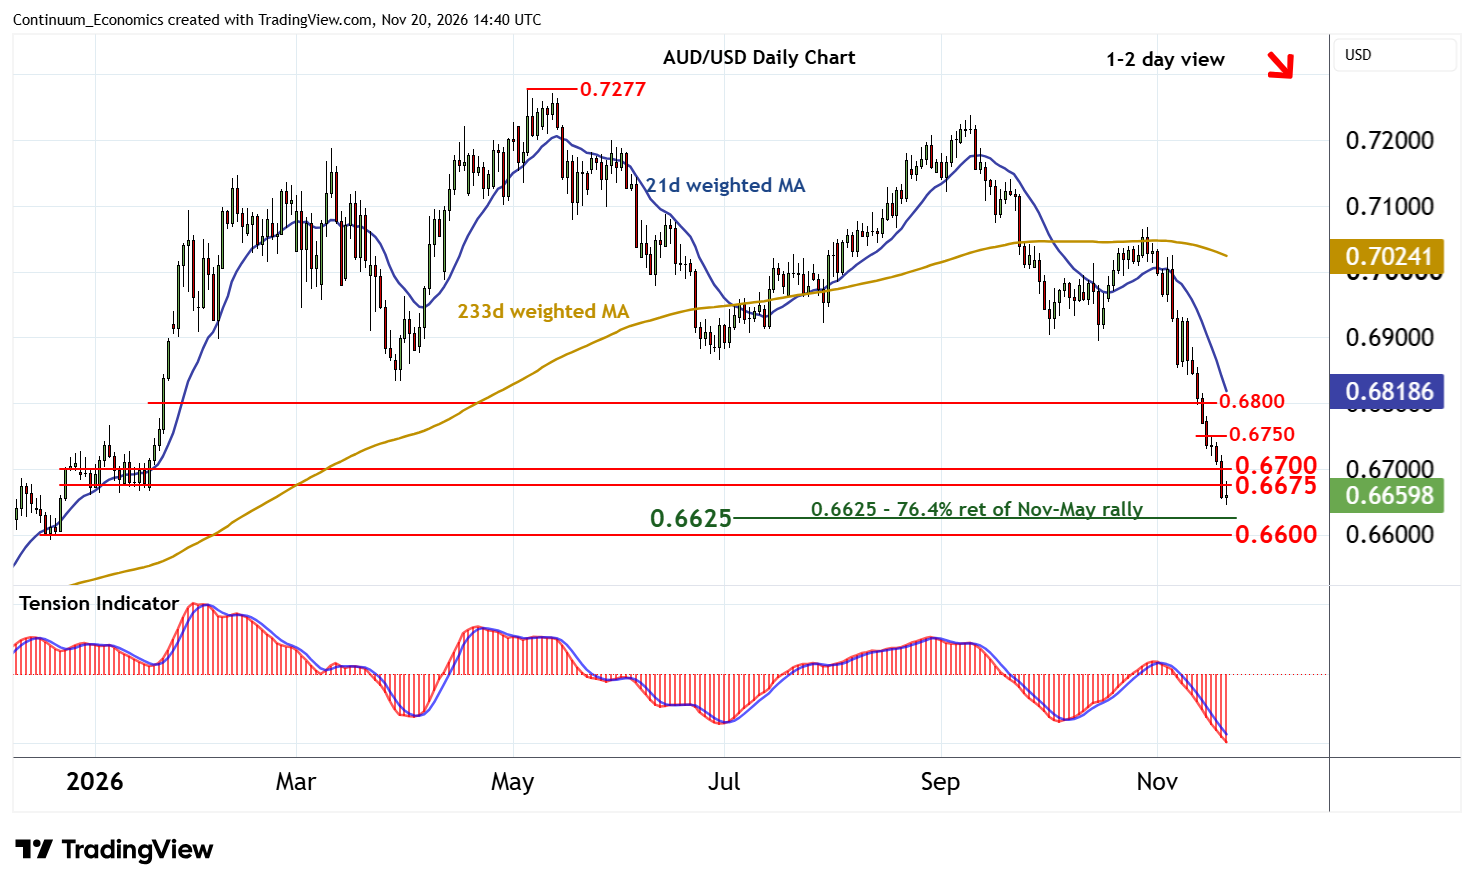
On the quintessential recent risk trade, AUD, where positioning is (very profitably) record spec short, AUD/USD is now has approaching strong support from 0.6660 to the 0.6625 Fib, and amid very oversold dailies.
Week Ahead
USA
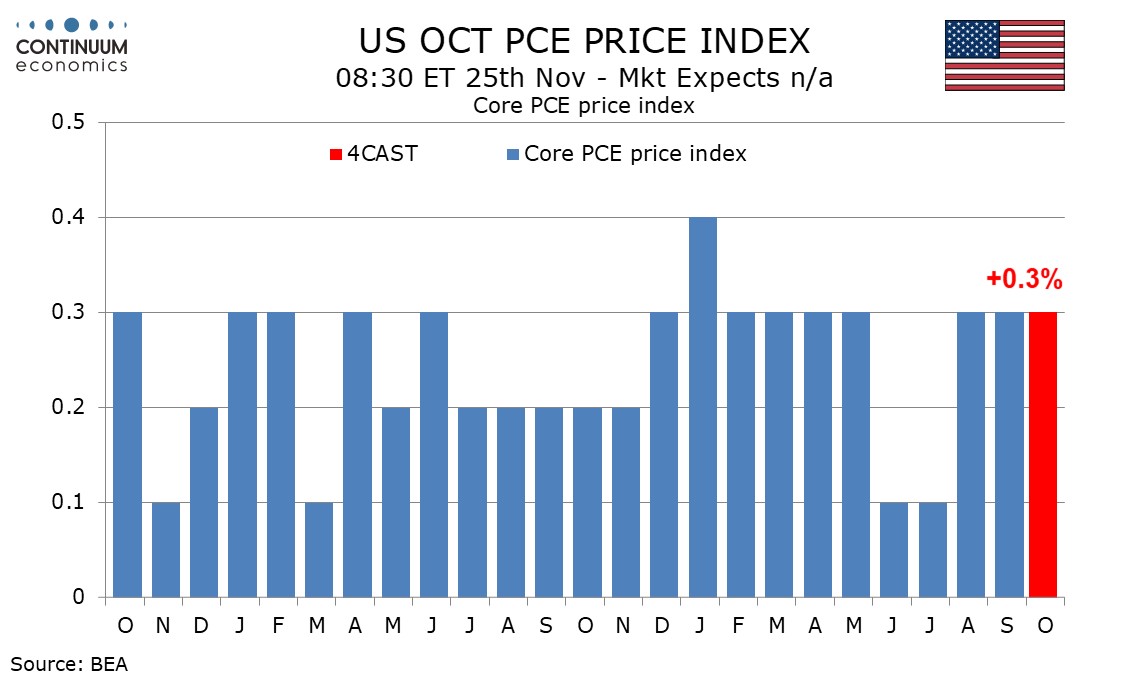
The US sees November’s S and P PMIs released on Monday, and November consumer confidence on Tuesday. The most significant data release of the week will be October core PCE prices on Wednesday, which we expect to rise by 0.3%, matching the core CPI. We expect overall PCE prices to also rise by 0.3%, marginally softer than a 0.4% overall CPI. We expect 0.4% gains in both personal income and spending. Also on Wednesday we expect Q3 GDP to be revised up to 3.6% from 3.4%, and October durable goods orders to increase by a modest 0.2%, 0.,5% ex transport. Later we expect October new home sales to fall 6.1% to 635k, extending a recent string of softer housing sector data.
The Thanksgiving holiday will mean no data is released on Thursday, with weekly initial claims brought forward to Wednesday. On Friday we expect October’s advance goods trade deficit to continue a recent deterioration, rising to $143.3bn from $135.1bn. There is not much Fed talk scheduled in a holiday-shortened week, though the dovish Williams will speak on Monday.
CANADA
Canada’s weekly calendar is quiet though the Q3 current account is scheduled on Friday.
UK
Flash PMIs for November are likely to show a further tick up as suggested by the rebound in orders in the monthly Industrial Orders CBI survey. More broadly, the indices will be watched for signs that tighter financial conditions are weighing on activity and whether inflationary pressures are increasing. So far there is no sign of that happening in the service sector. BoE’s Pill is scheduled to speak on a panel at the Oesterreichische Nationalbank Conference on European Economic Integration in Vienna on Monday, 23 November.
Eurozone
Flash PMIs covering November are expected to show a mixed picture. In October business activity slumped in France given social unrest whereas in Spain growth remained strong along with robust expansion in Germany. Higher borrowing costs as well as strikes in Spain and protests in Germany may weigh on November services PMIs. Eurozone business and consumer sentiment indices will also be released on Friday and the key “consumer inflation expectations” sub index should be watched for any sign of de-anchoring of inflation expectations.
Japan
Thin week with Japan on holiday on Monday. Tokyo CPI the key data release with consensus looking for a further acceleration to 3% from 2.6%, further away from target. In the current environment, it is market stability rather than data that is the factor that would need to become dominant to prevent the drive for a Dec hike delivery.