Preview: Due November 10 - U.S. October CPI - A more moderate month
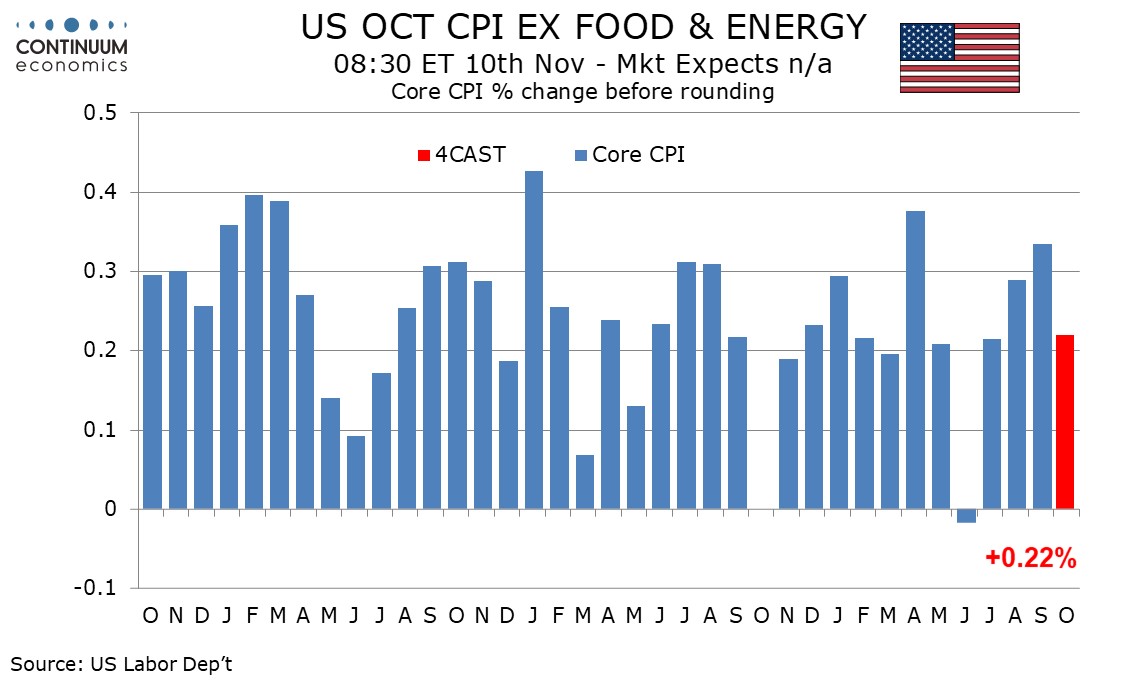
We expect more subdued CPI in October after two straight disappointing 0.3% gains in the core rate, with October’s core rate seen at 0.2%, 0.22% before rounding. Gasoline prices have seen only a marginal rise on the month, and we expect overall CPI to also rise by 0.2%, though at 0.24% before rounding.
August’s core CPI was above expectations largely because of a one-time 5.4% surge in telephone charges, with lodging away from home also giving a boost after two straight sharp declines. The Cleveland Fed’s Median CPI, removing the impact of volatile components, rose by only 0.17% in August.
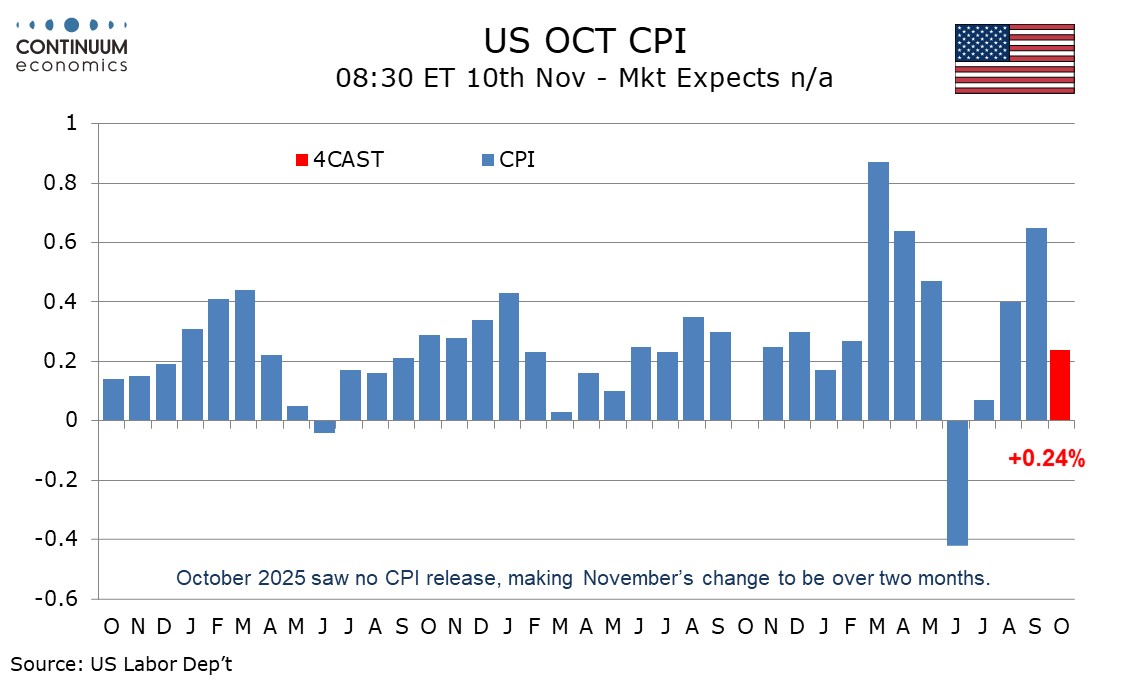
September’s core CPI was more broadly disappointing, though the Median CPI was still moderate at 0.23%. Lodging away from home saw a second straight strong month, and that suggests the two straight declines have now been corrected. Used autos at 0.7% also saw a strong month, which is unlikely to be fully matched in October.
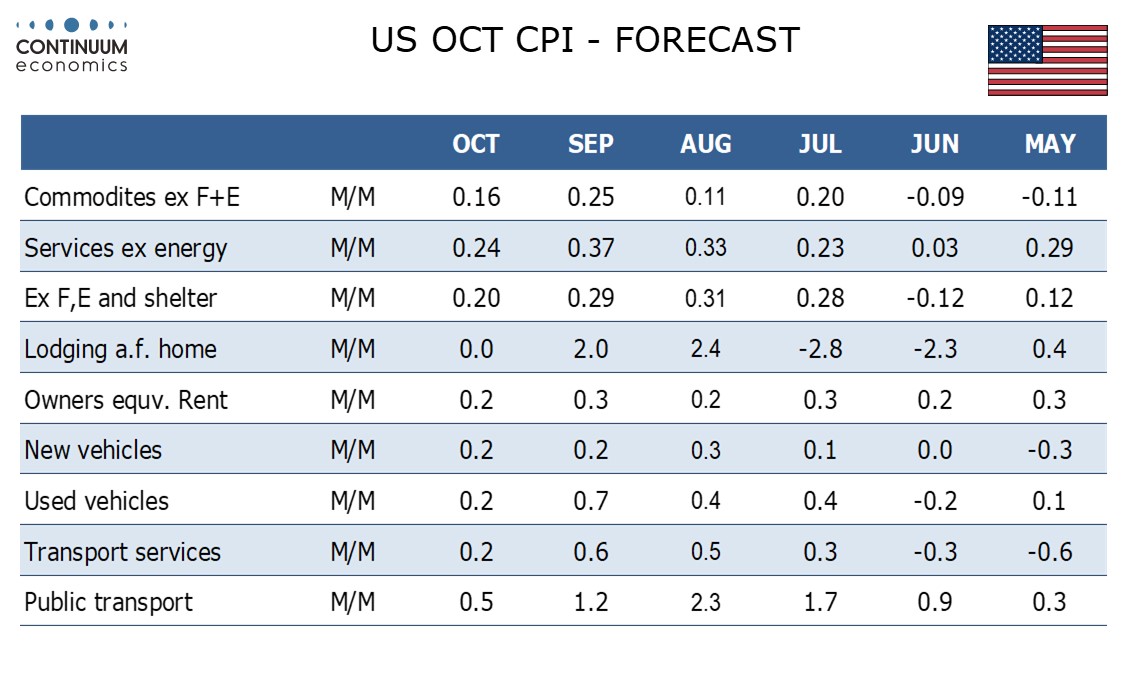
We expect goods ex food and energy to rise by 0.16%, and services less energy to rise by 0.24%. Air fares are likely to see some feed through from energy, but less than in September, with gasoline having seen a much more modest increase in October than September. We expect food to remain subdued with a rise of 0.1%. Ex food, energy and shelter we expect a rise of 0.20%, a four-month low.
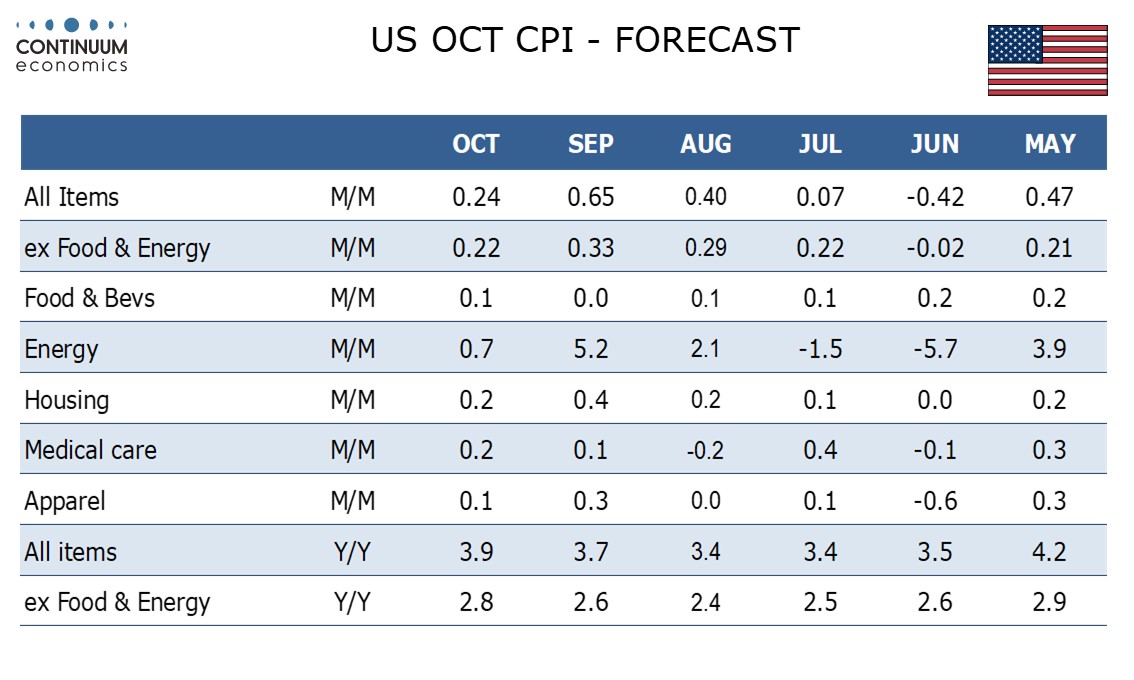
October 2025 saw no monthly CPI data released due to a government shutdown, thus leaving accurate yr/yr comparisons unavailable. Compared to September 2025, CPI under our forecast would be up by 3.9%, versus a 3.5% September/September comparison, with the ex food and energy rate up by 2.8%, compared to a 2.6% September/September comparison.