FX Weekly Strategy: N America, 26-30 October
*Central bank meeting flurry - BoC might disappoint, ECB eyed for tone change, RBNZ seen a cert
*UK Budget may have its critics, but not seen taking any chances
* JPY along with CHF regaining its safety credentials
*France remains a focus, Moody's a sideshow to the bigger arc
A degree of standoff between negative euro sentiment and developments on one side and positional exhaustion on the other continued to play out in last week’s consolidation. That didn't apply to all crosses however and some other related themes remained active.
First, further indications that periods of tech-pressure are presently weighing rather than boosting the dollar - if within the context of large overhanging dollar longs and yield retreats in USTs. And related, second that CHF and JPY especially are increasingly regaining their ‘traditional’ risk-aversion favoured status, in the context of equity noise and the France-centric euro concerns. These crosses are also stretched nearby but underlying bear trends look increasingly established, playing in favour of further potential extensions ahead.
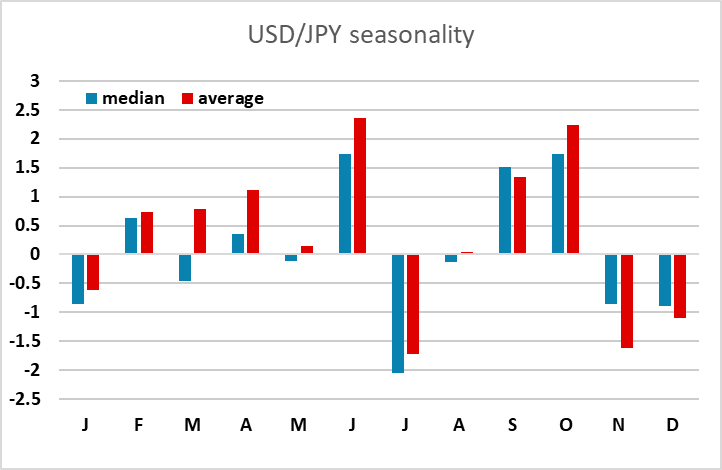
Seasonal bias can also tend to be lower for USD/JPY in November. Not a factor to be overplayed, but relevant if we are entering a challenging period of heightened strains and stresses ahead where volatility may pick up in coming weeks. Technically, 156~ is important support now on the pair, as break through here gives a much more bearish picture of further momentum to follow on from the recent distributive supply of recent weeks. That opens up 155.20/155.00, and through there further out returns focus to the 152.90 September low.
The week, of course, will be dominated by two major, and partly linked, factors: the swathe of central bank meetings and the ongoing French-led sovereign action.
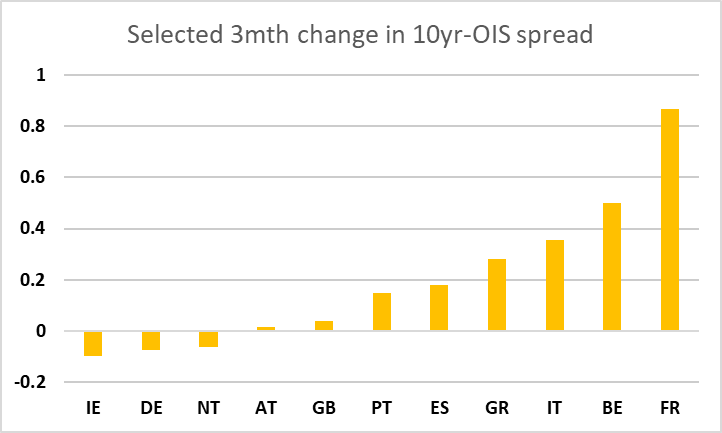
On the latter, Moody’s will have reported on its France rating after last Friday’s close and while the market certainly saw clear event-positioning prior, especially in Thursday's acceleration, it also a certain amount of short-covering/profit-taking on Friday too. In that sense, ‘buy the fact’ is evidently possible but not totally a given. On the hourly chart, pullback support on the spread is around 168bp. The market may also be tempted to trim outright speculative short positions into the ECB, ‘just in case’, even if nobody is expecting the ECB to ride to the rescue with TPI at this point in time. Pullback to re-test the 160 daily break level on the spread in that case would be entirely 'normal', and wouldn't alter the overall bullish and accelerating chart structure.
The more interesting nuance from the ECB will be whether Lagarde doubles down on recent tone change that shifted focused more onto the financial tightening seen through recent bond action and its implications for growth and inflation forecasts. That could feed a more dovish market take, and further erode the projected ECB tightening path priced in to the money market from here.
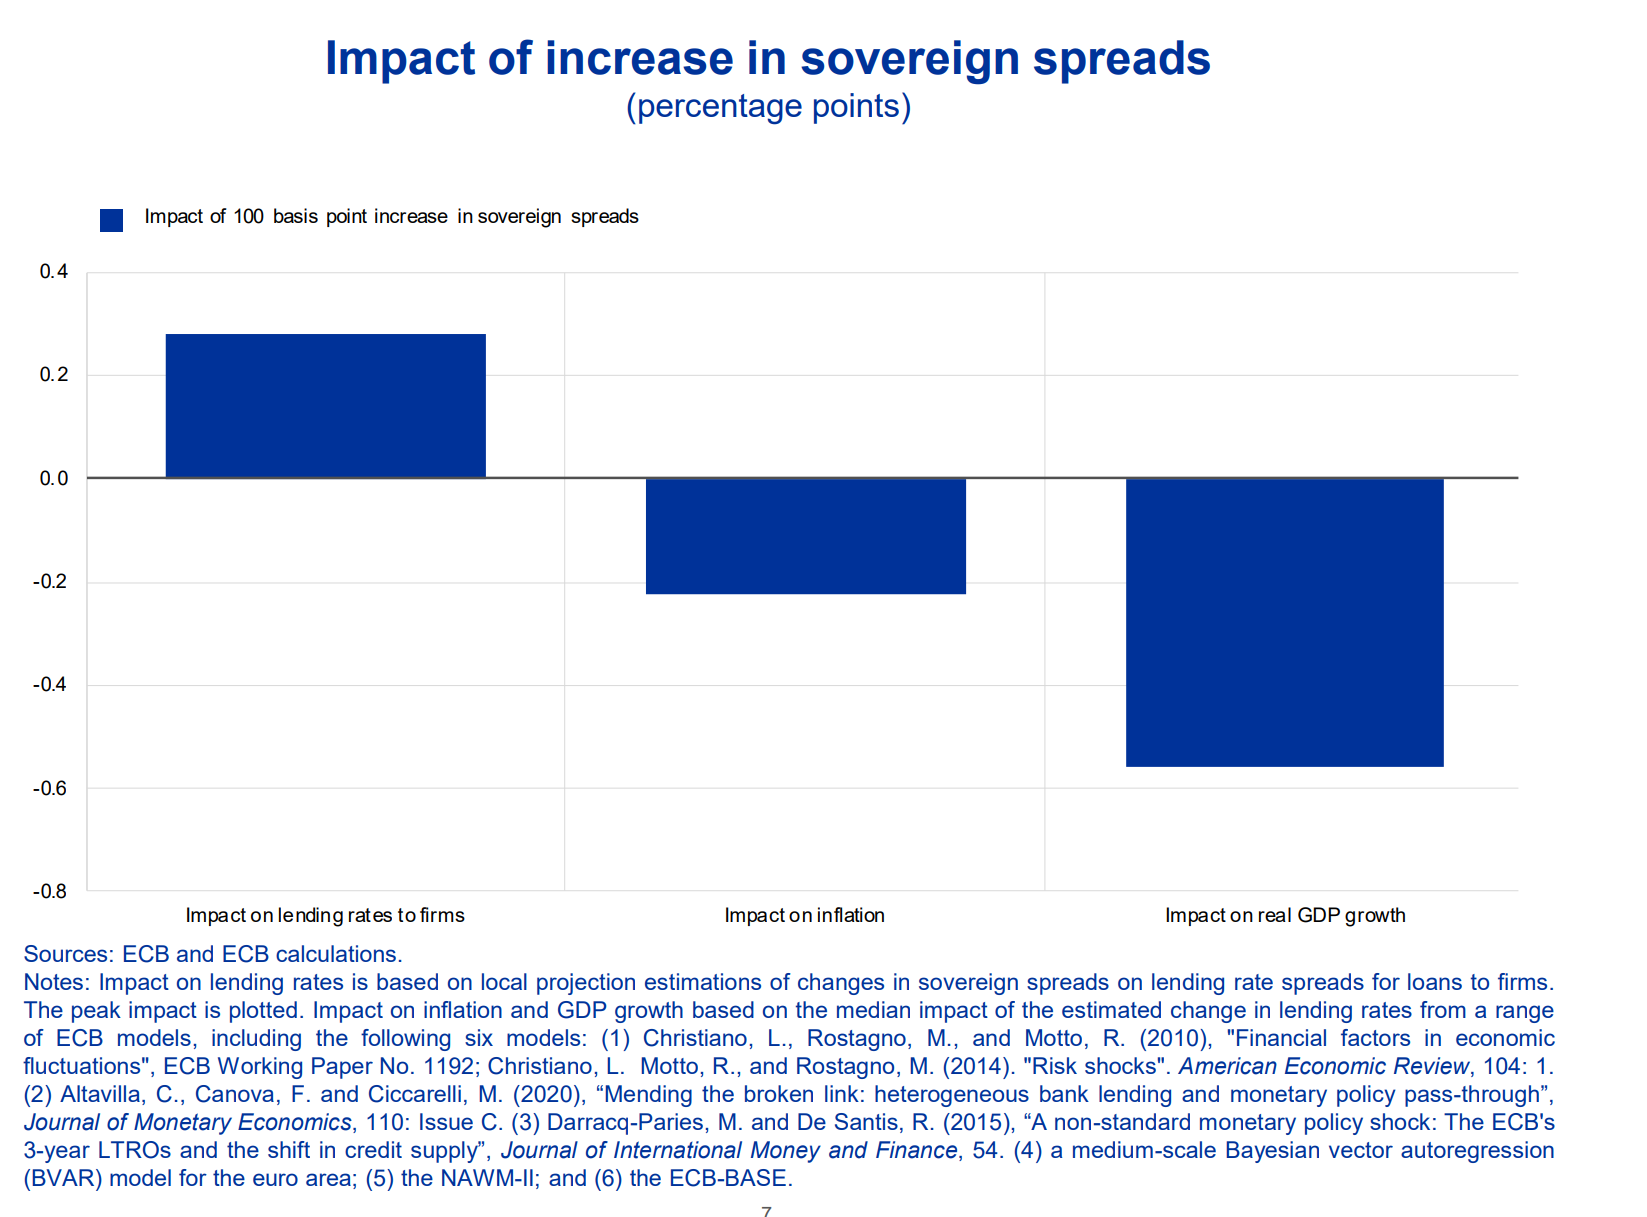
Regardless of this week's meeting, there is a very credible risk scenario where, without active policy intervention, a Dec ECB hikes gets forced off the table in coming weeks by further escalation, with OAT-bunds accelerating further towards 200bp, in an ‘echo’ move from 2012. At that stage, spillover would likely become wider and less discriminating.
If the recent EUR/USD consolidation fails to gain any squeeze traction through early week, this inability to bounce could become a time correction that gives way ultimately to a re-test of the 1.1115 current year low.
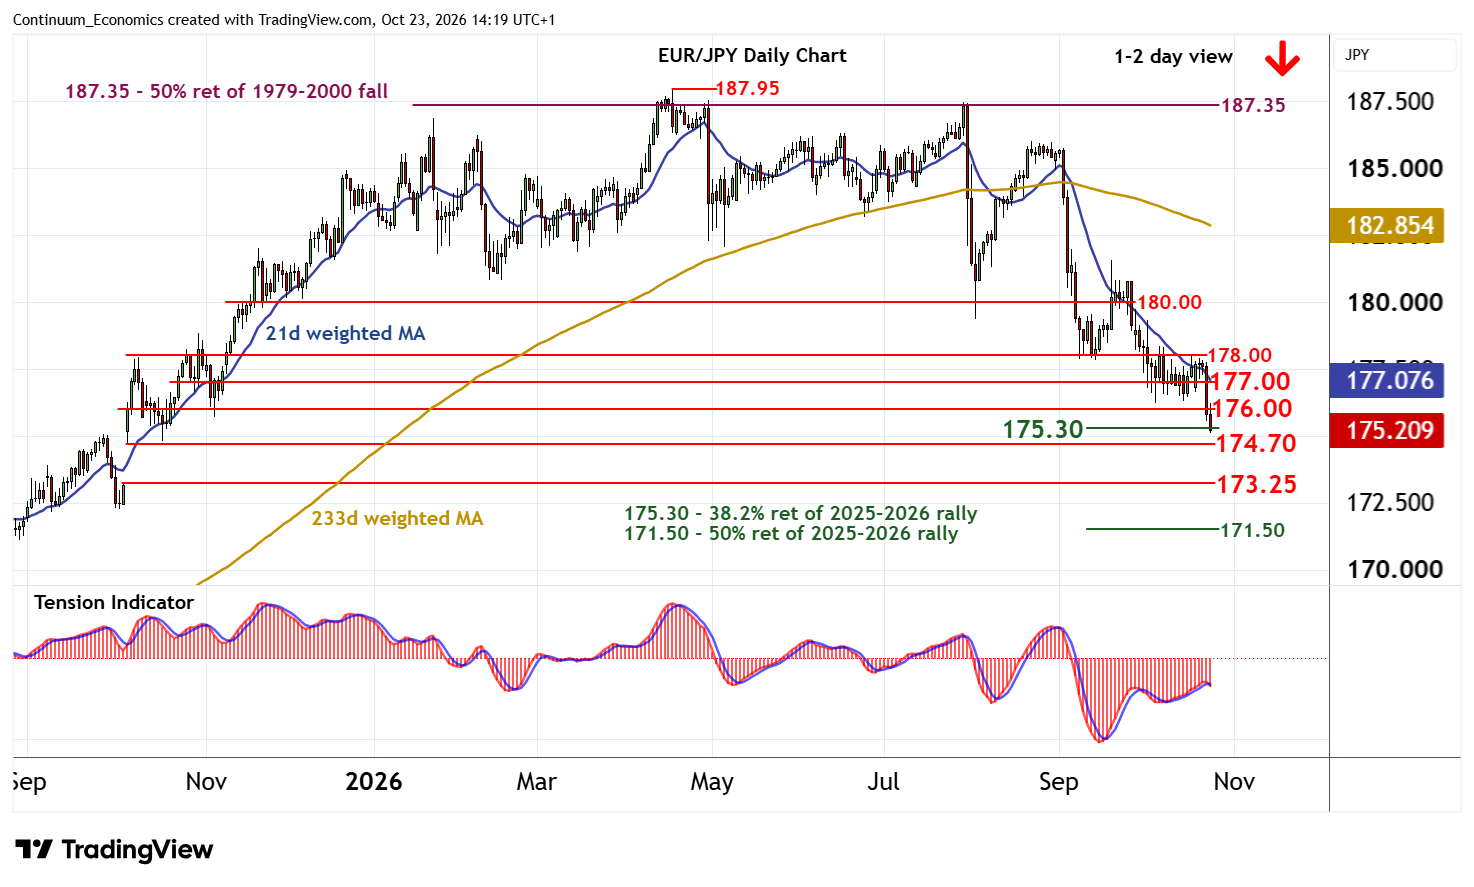
EUR/JPY takes the dollar out of the equation and, notwithstanding recent oversold action, looks to remain on a weak trend. Below 176, opens 175.00 towards the 174.70 gap high from 6 October. A further break will add weight to already bearish price action and put focus on the 173.25 gap low.
Along the theme of early week caution and taking some chips off the table, faster money may also be tempted to book some profits on GBP longs too into the UK Budget, given the recent stalling around fib support and ahead of 0.8350 on the cross and around 1.34 and 50% on cable. Budget day itself is frequently characterised by think tank commentary that typically prefers to focus on discovering optimistic assumptions, project scenarios of missed rules, and seek out ‘black holes’. Ultimately though, the Budget is not expected to take any risks against the current backdrop and should leave the current re-ranking in place. Indeed, further out, EUR/GBP still risks deeper tests into more major multi-year range tests and the market has been focusing more on options positioning for such scenarios.
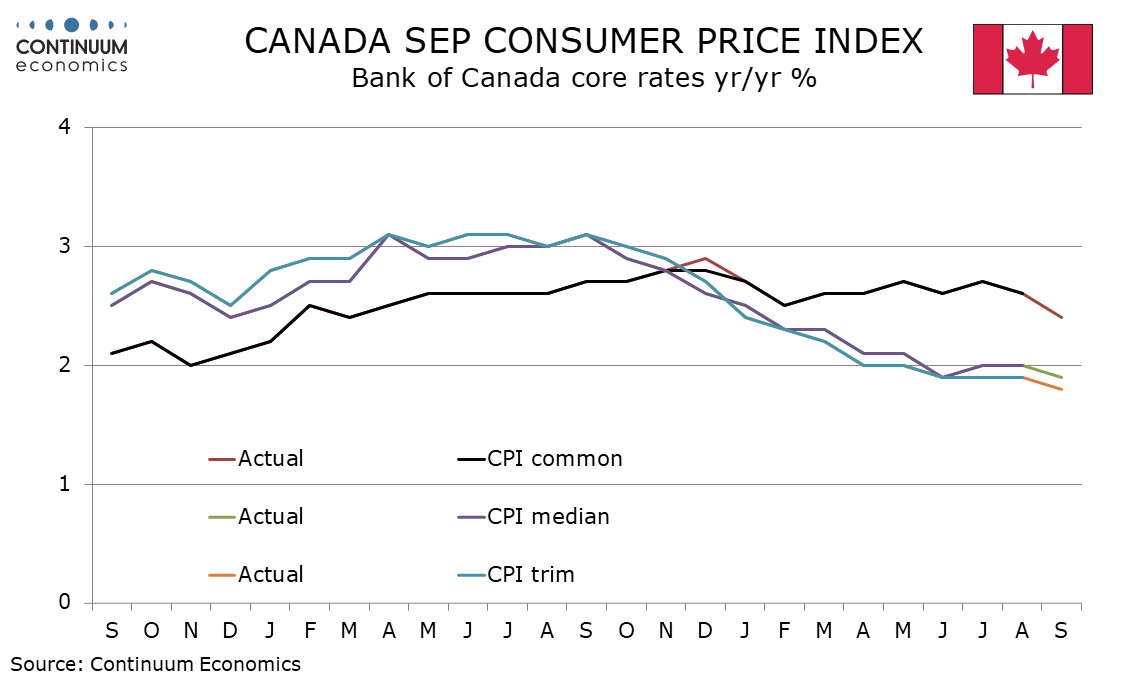
Canada is perhaps the other side story to watch out for this week. We see risks the BoC opts to leaves rates unchanged (and indeed that even Dec is not a shoo-in) while consensus leans firmly on the side of a hike. That could see some kneejerk disappointment for CAD, especially as its been on a decent retracement run.
Week Ahead
USA
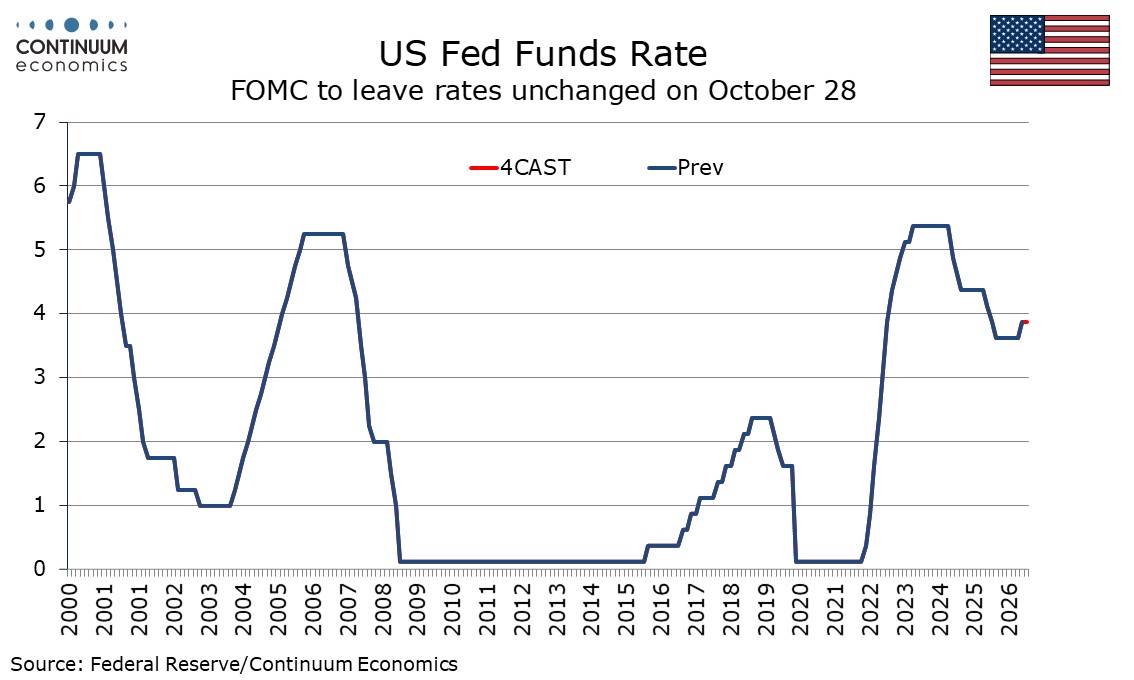
The FOMC meets on Wednesday and while tightening will be debated, we expect rates will be left unchanged, with two or three hawkish dissenters. A December move remains likely but forward guidance is unlikely to be provided. Thursday is a significant day for data with Q3 GDP set to rise by 2.8% annualized with a 2.4% rise in the core PCE price index for Q3. That assumes a 0.3% increase in September’s core PCE price index, which will be released at the same time. Big tech earnings also due with Alphabet, Amazon and Microsoft, as well as Intel and oil majors.
CANADA
The Bank of Canada meets on Wednesday and is likely to leave rates unchanged. Risks to prices will be more stressed than those to growth, but the tone may be a little more balanced than in September, meaning a December move should not be seen as a done deal.
EUROZONE
Thursday’s ECB meeting the big focal point, less for the decision, with rates left unchanged, than for the commentary and recent developments and their impact, especially with regard to France and bond spreads.
Alongside more secondary data, the main interest comes from flash Q3 GDP, with expectations centred on 0.2%q/q to leave the yr/yr rate fairly steady at 1.1% from 1.2%. Focus is more shifting to whether recent bond and cost impacts start to exert more of a negative impact from here.
UK
The Budget dominates the UK week and remains key to sterling’s recent risk-repricing. Speculation has been reasonably low level into the event although kite flying has revolved around potential bank taxes and a broad framing of maintaining existing fiscal rules, albeit with some erosion of the safety margins presented as event (Iran) justified use of contingency. The market is reasonable comfortable with outturns that stick within that guidance. On the bond side, the DMO outlook will also be watched, particularly any further move away from long end issuance in the context of structurally declining pension demand.
JP
The BoJ is almost unanimously expected to leave rates unchanged this meeting although there will be some focus on the latest projections, with sources suggesting that inflation projections might be revised up, supporting the intention to continue to tighten in coming months, global backdrop allowing. In that context, the usual end-month batch of price and activity data increasingly focuses on the Tokyo CPI data, where the market is expecting core to level at 2.6% from 2.7%, well above 2%.
NZ
A packed week for central banks also sees the RBNZ meet, with a hike virtually 100% priced in, shifting focus to the forward guidance. At present, the curve has another hike in by Feb and a further by May and then Aug, running at a bi-meeting pace.
AU
Q3 CPI is a key data release, particularly given recent RBA comments suggesting that it may have to deal with the hard choices of dealing with inflation over protecting the labour market. Consensus looks for 1.3%q/q and 1.0% trimmed mean, leaving yr/yr rates steady at their highs. Market pricing has nudged in favour of a Nov hike (around 60%), and so would need a clear downside surprise to shift the balance. RBA speakers on Wednesday will also be watched to see if this guidance is repeated.