Preview: Due October 14 - U.S. September CPI - Stronger, but with a slower core rate
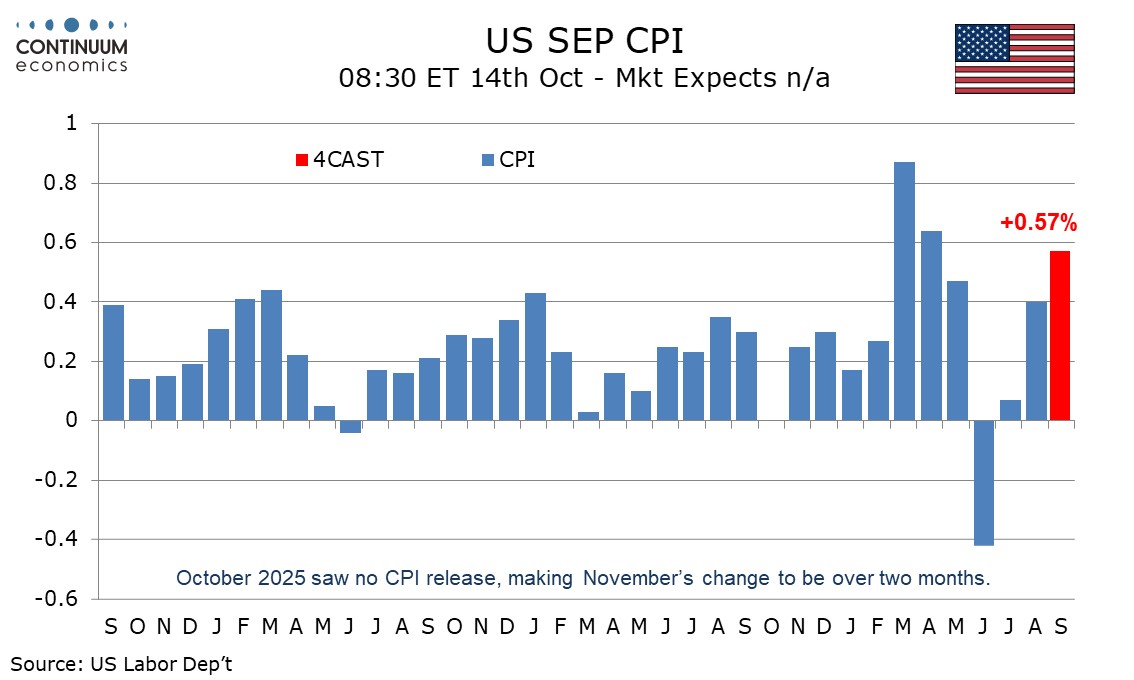
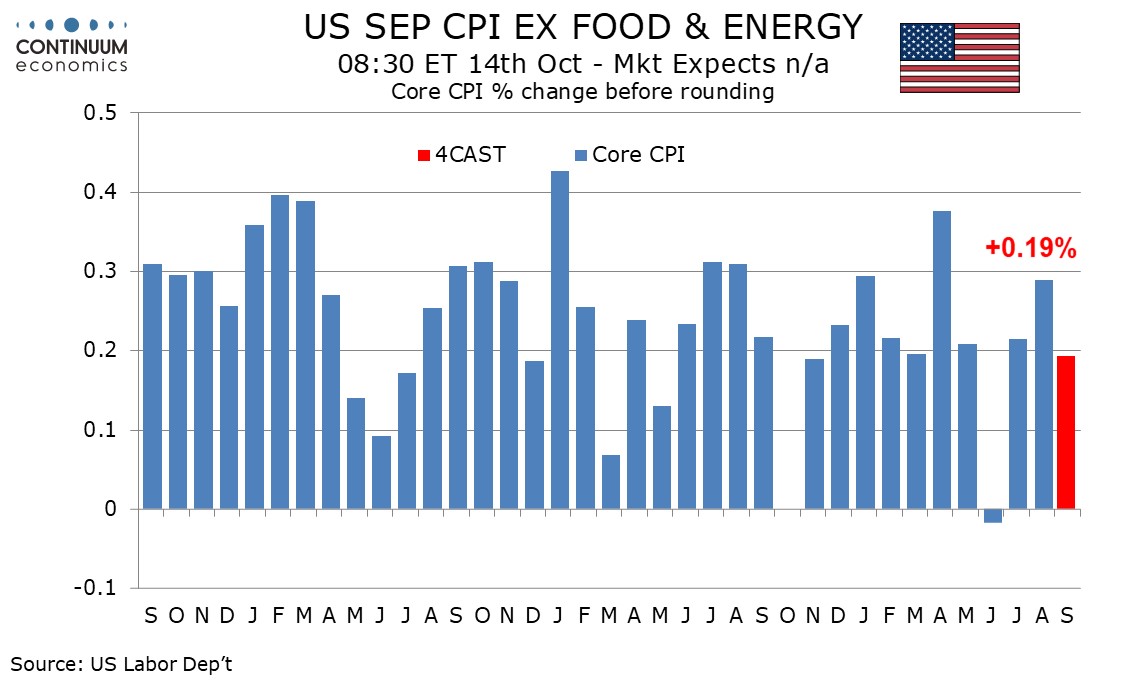
We expect a stronger rise of 0.6% in overall CPI in September, but a moderate 0.2% increase ex food and energy. Before rounding we expect the respective gains to be 0.57% and 0.19%. The latter would be a significant slowing from August’s 0.29%, but the former would be the strongest since April.
An upside surprise in August’s core CPI was narrowly based, with the Cleveland Fed’s Median CPI up by only 0.17% in the month, slower than July’s 0.26%. The surprise was led by a 5.4% bounce in telephone services which added 0.096% to the core CPI, and came after fresh methodology in the component was introduced. We expect the August bounce in telephone services to be a one-time event and the sector to make no significant contribution in September.
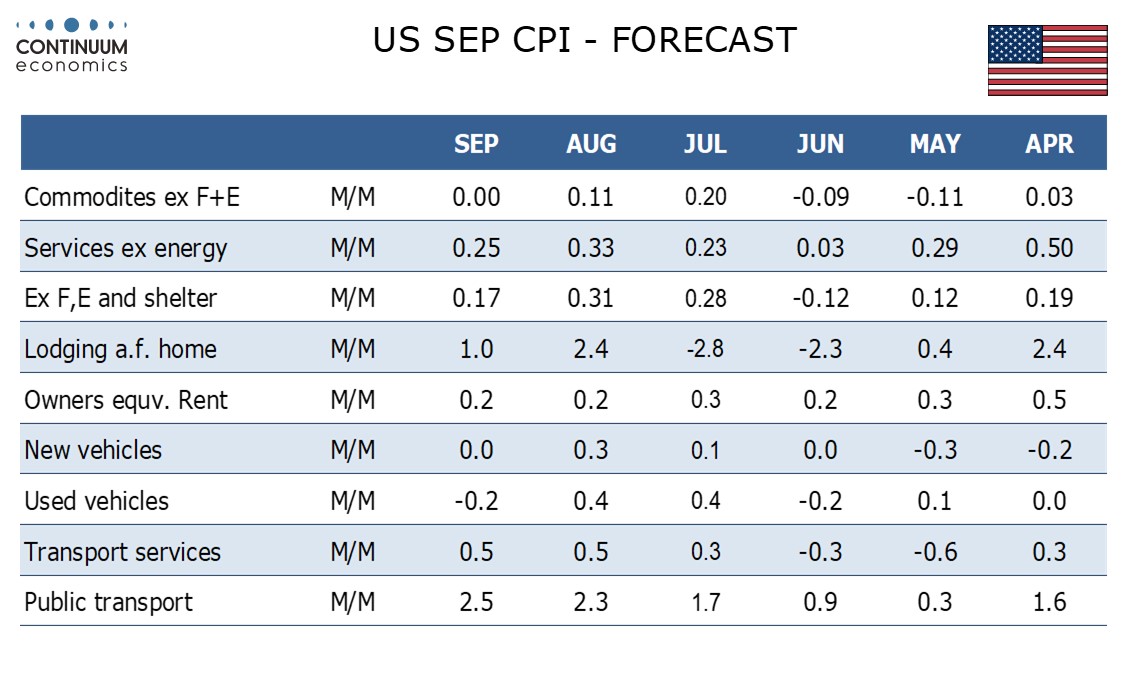
Also firm in August was a 2.4% rise in lodging away from home, which followed two straight declines of similar magnitude. We see scope for the correction here to extend further, but September’s rise is unlikely to match that of August. Used autos saw a second straight strong month at 0.4% in August and we expect a correction lower here. Most components of the core CPI are likely to remain fairly subdued but we expect energy pass-through to bring continued strength in air fares.
We expect CPI ex food, energy and shelter to increase by 0.17%, down from 0.31% in August. Energy is likely to see a strong 5.5% increase led by gasoline and that would be its strongest contribution since a 10.9% surge in March. We however we expect a third straight subdued 0.1% increase in food.
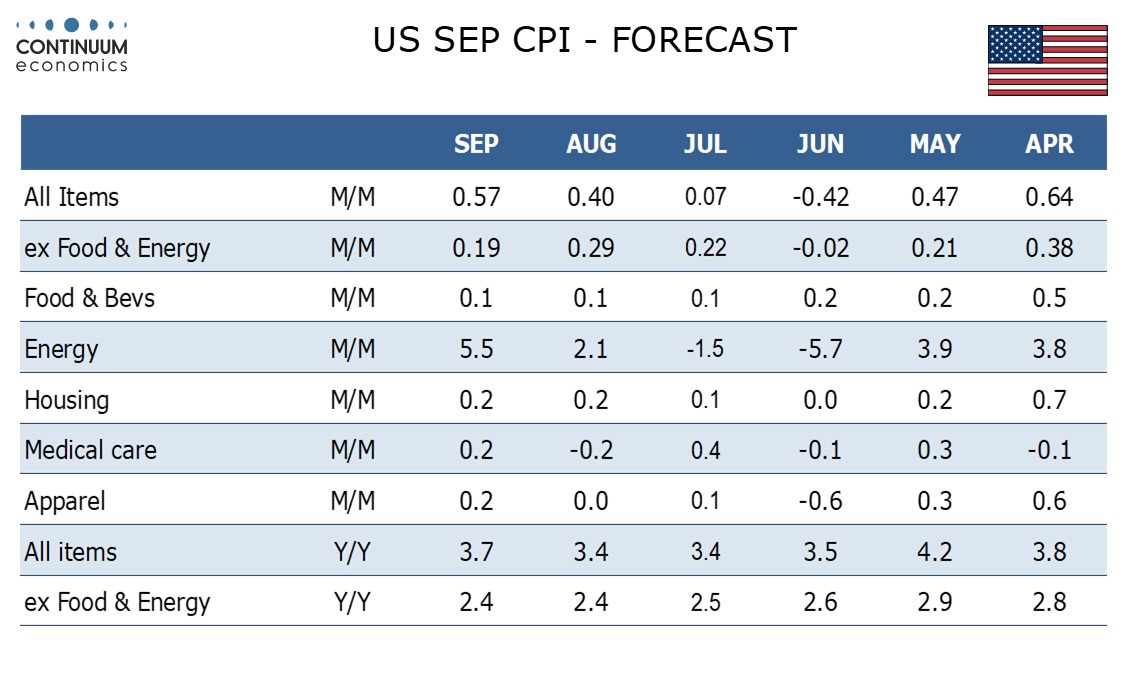
Our forecast would leave yr/yr core CPI at August’s 2.4% pace which was the slowest since March 2021. Overall CPI however looks set to bounce to 3.7% yr/yr from 3.4%, and that would be a four-month high.