Preview: Due November 6 - U.S. October Employment (Non-Farm Payrolls) - Subdued report to hint at Q4 slowing
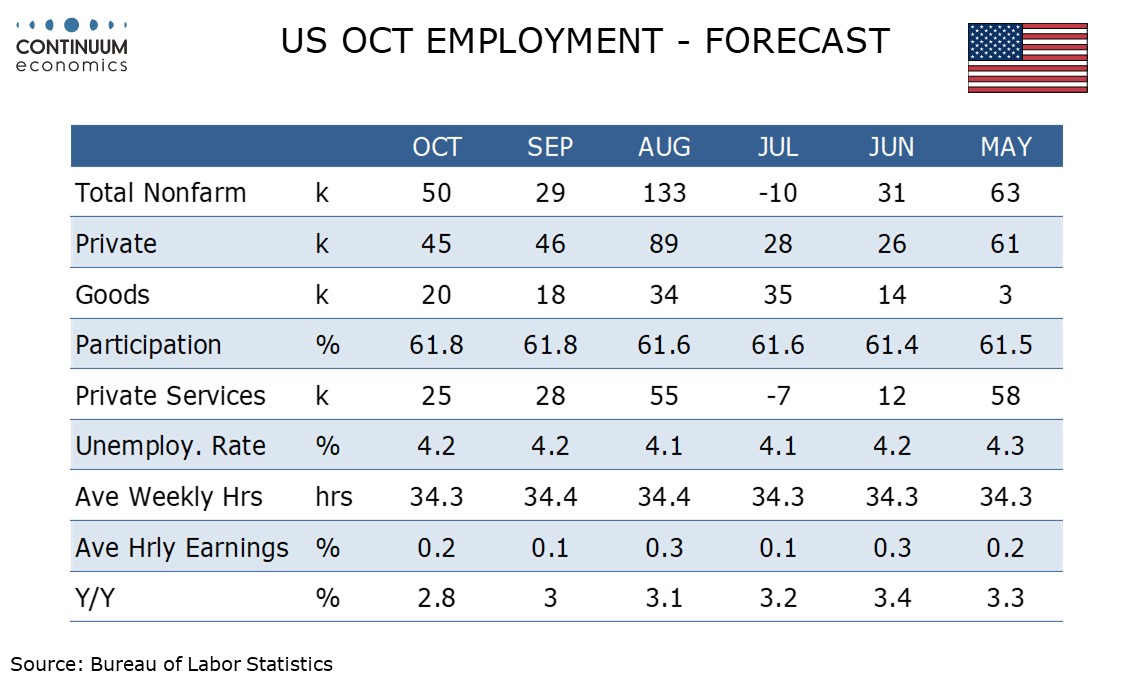
We expect October’s non-farm payroll to rise by 50k and by 45k in the private sector, in line with recent trend. We expect unemployment to remain at 4.2%, sustaining September’s increase after two months at 4.1%. We expect a modest 0.2% rise in average hourly earnings and a fall in the workweek to complete a generally subdued breakdown.
Initial claims have been very low recently, and particularly so in the payroll survey week. However continued claims appear to be finding a base after recent declines. Despite the low level of initial claims, the economy faces risk of some loss of momentum entering Q4 given recent gains in mortgage rates and gasoline prices.
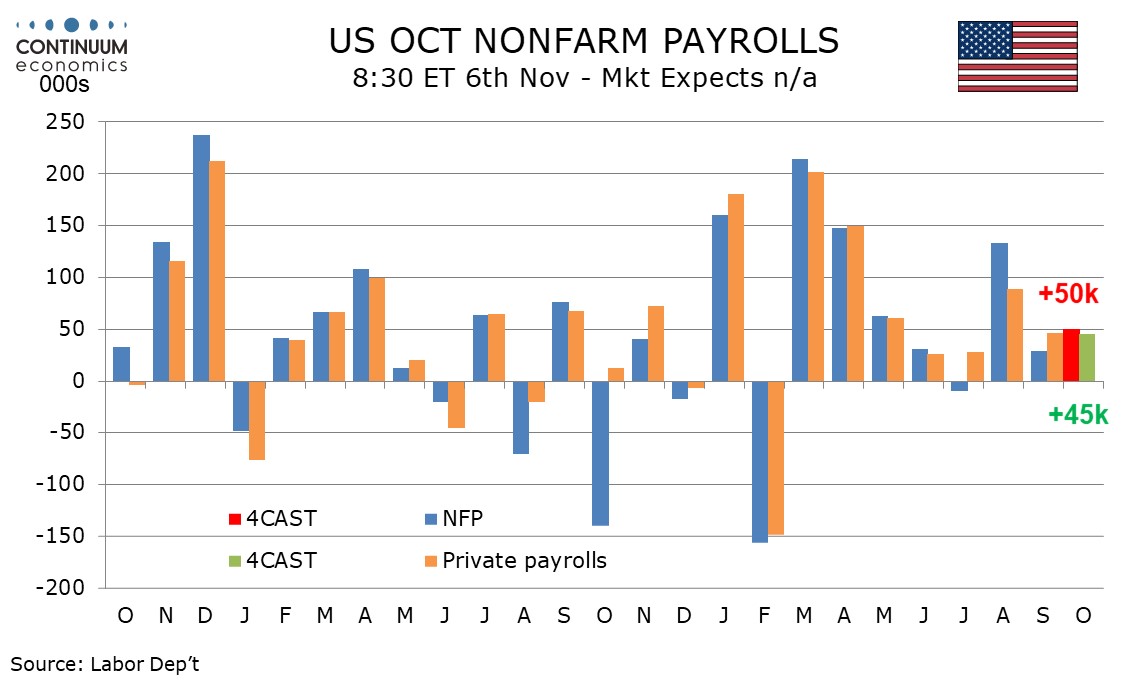
Our forecasts for both overall and private sector payrolls are close to September’s 3-month averages of 51k and 54k respectively. Private payrolls will be almost identical to September’s 46k increase though overall payrolls will be stronger than September’s 29k but slower than August’s 133k.
Changes are likely to be modest in most sectors. Government has been volatile recently with losses in July and September outweighing a rise in August. We expect a modest 5k rise in September. Leisure and hospitality has been the main recent swing factor in the private sector, but September’s moderate 10k rise hints at stabilization. We expect a 5k increase in October.
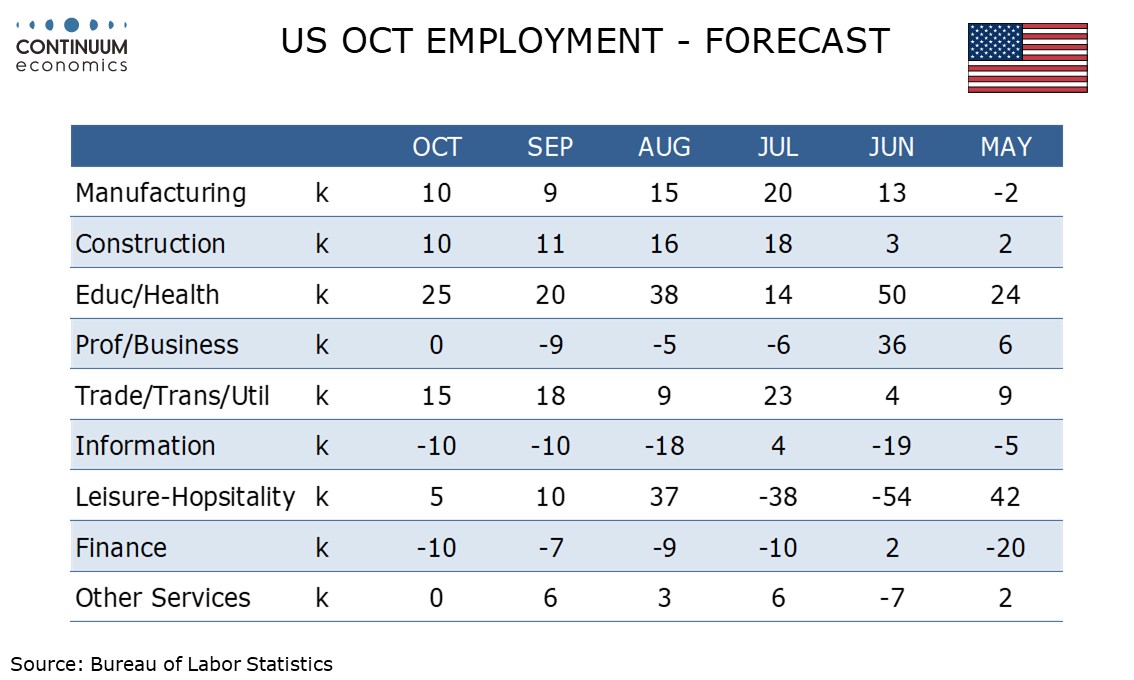
Education and health has lost momentum and we expect a modest rise of 25k, up from 20k in September but well below trend was at the start of the year. Modest gains of 10k in both manufacturing and construction will be supported by AI, but balanced by 10k declines in both finance and information, also influenced by AI.
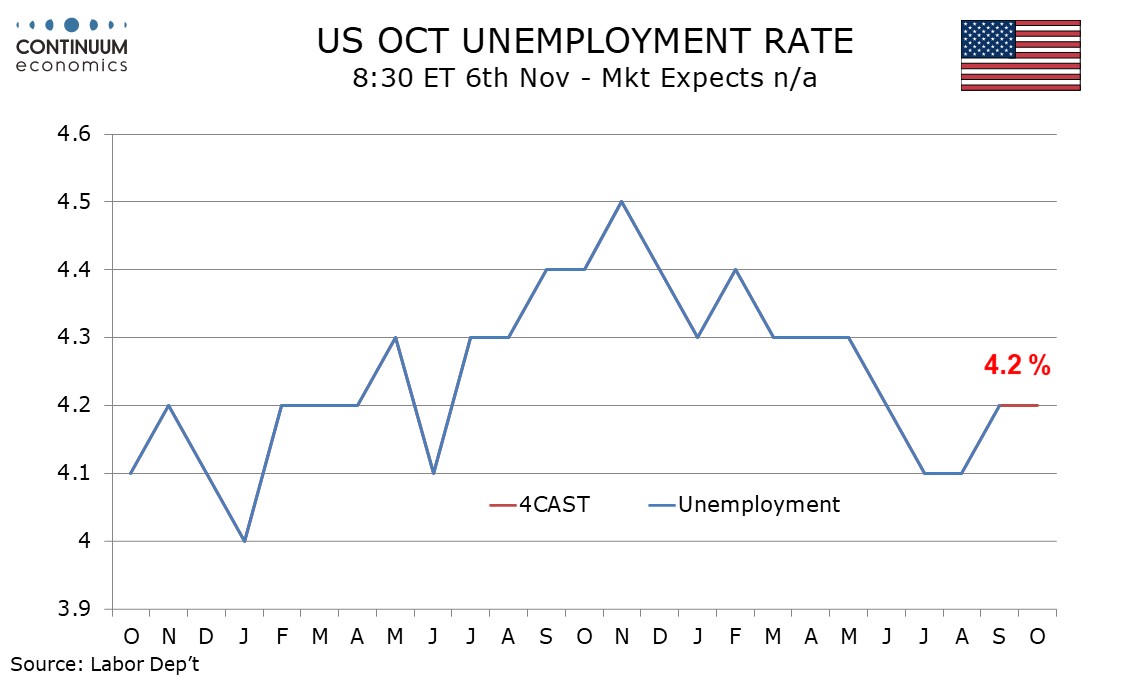
We expect the household survey to show little change in the labor force and a slight decline in employment, both after two months of strong gains, lifting the unemployment rate to 4.205% from 4.176% before rounding.
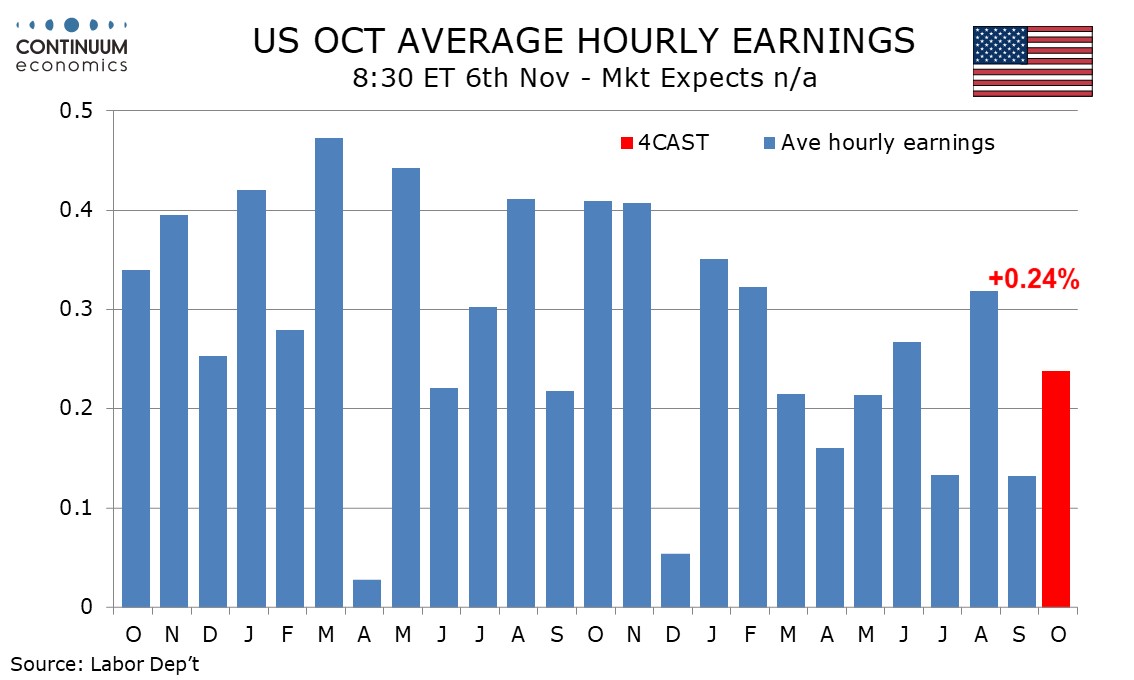
Average hourly earnings trend now looks closer to 0.2% per month than 0.3% where it started the year. We expect a 0.2% rise in October, up from 0.13% in September, but this would still see yr/yr growth decline to 2.8% from 3.0%. This would be the slowest since May 2021.
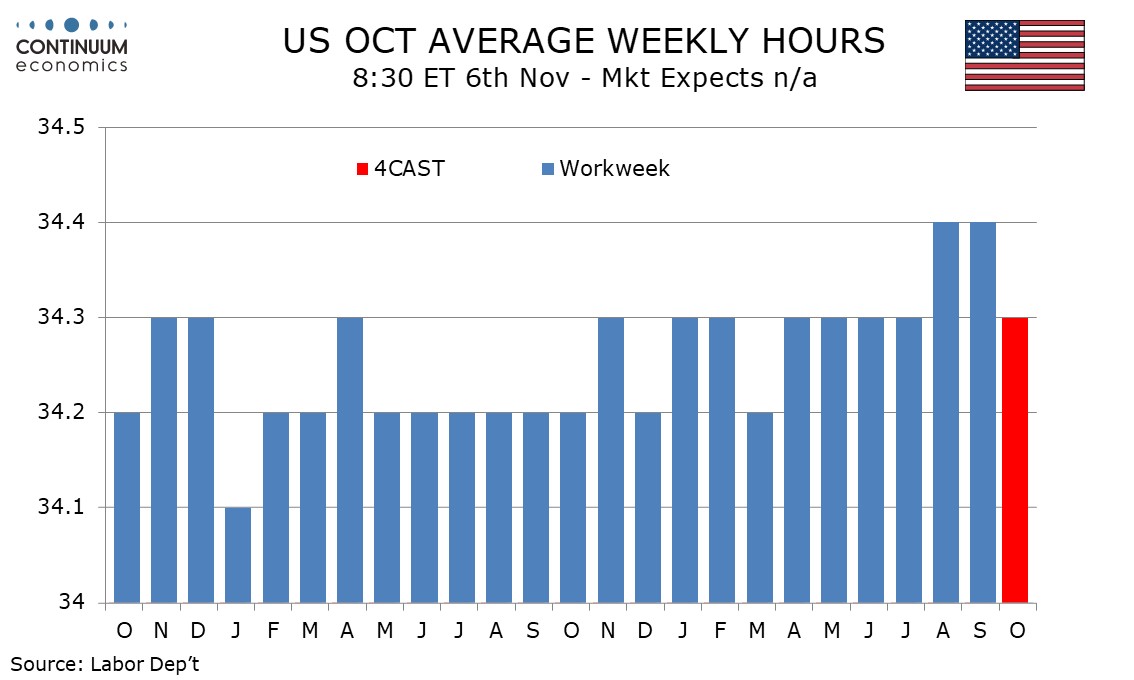
We expect a dip in the workweek to 34.3 hours after two months at 34.4 to hint at a loss of economic momentum entering Q4. The two months at 34.4 were the strongest since early 2024.