FX Daily Strategy: Asia, Oct 1
Oversold sterling sees a bounce as NoV BoE hike firms, Fed fever tempers
EZ headline inflation hot, but France spread continues to blow out, one to watch (EUR/GBP downside?)
ISM main data focus ahead of payrolls
Some shuffling the pack in the last couple of days in the FX beauty contest and while this has somewhat stymied the dollar’s overbought charge - and in particular left the previously noted oversold sterling better positioned for a bounce - it’s somewhat chequered news for the euro.
Some of the current short-attention-span FX focus is on ‘who comes next’ in the tightening sequences - in part, for what that supports in terms of speed and extent of delivery given how much in many cases has become priced in.
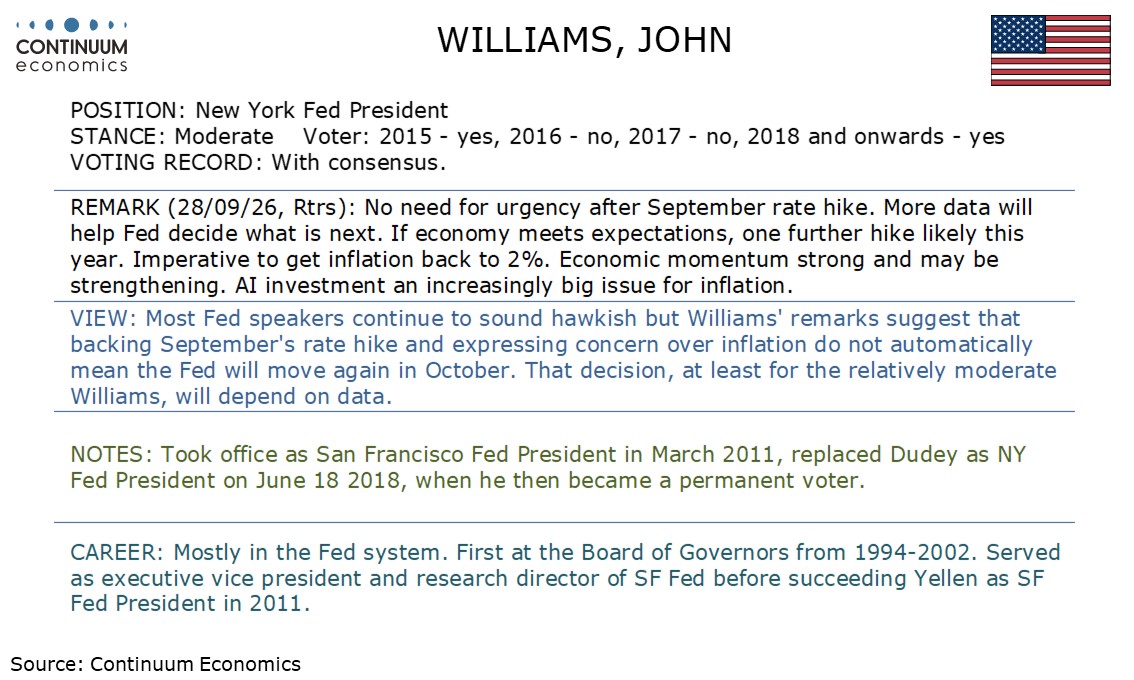
Fed Williams’ more relaxed tone (‘no urgency after Sep’) has slightly cooled off the charge for an Oct Fed follow up vs December for now. Williams – data allowing – would seem to prefer the ‘one hike implied by year end’ to happen in more measured fashion in December rather than allow the market to continue to extrapolate.
Data has also to an extent played ball with that, albeit with a mix of inflation news generally more favourable, but growth data also more positive too (negatives from the wider trade deficit being the main exception there).
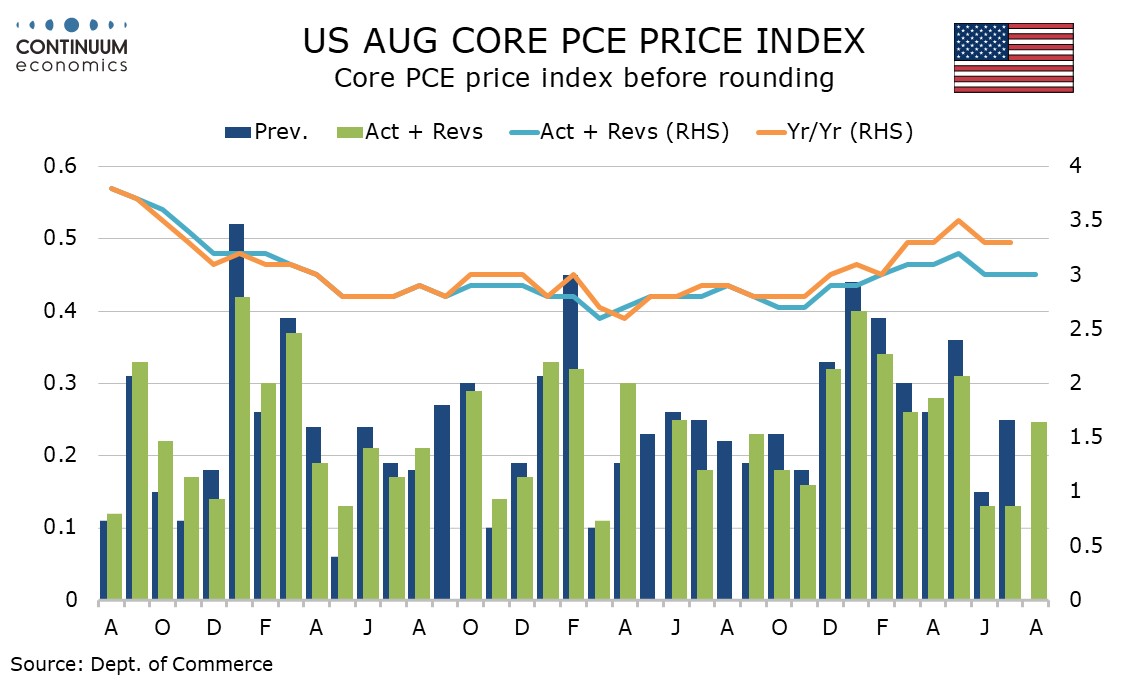
Back revisions to PCE data in particular see core PCE down to 3% from 3.3% on the expected technical annual revisions, while also seeing the savings rate lifted by around 1pp to look less low, if still declining. ADP data also came in on the upside of expectations, if within the bounds of noise versus payrolls expectations. Net picture is slightly more favourable though there are still the payrolls itself and then the next CPI data to come - the latter might err back to the upside again.
Euro national inflation data meanwhile is running hot for Sep, with the devil to be in the detail in terms of energy vs domestic. Lagarde’s ‘measured response’ language earlier in the week keeps the market here biased to December over Oct, if with Oct pegged in the 30%s.
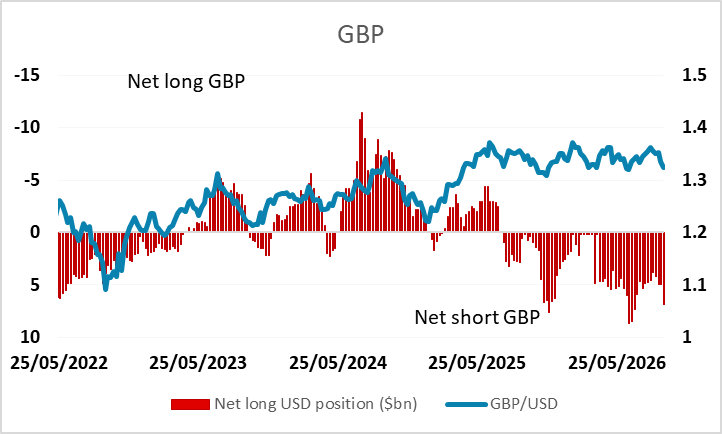
That all leaves the UK coming up the rails as a November hike (geopolitical developments dependent) being priced in increasingly confidently (80-90%) after the upward revision to GDP left a resilient picture, through Q2 at least, in place. With the market having got overly short GBP, that is tending to play to the current corrective bounce, that in turn could even become a mini squeeze, especially with the EUR/GBP roll back from the failed resistance test earlier in the week.
The background stories here are also relevant. UK PM Burnham has flagged the potential for increasingly close EU options for the UK, all the way through to full return (Brentry?). Not going to happen in a hurry but it is a possible medium-term positive given the negative terms of trade and GDP level impact that came with the exit.
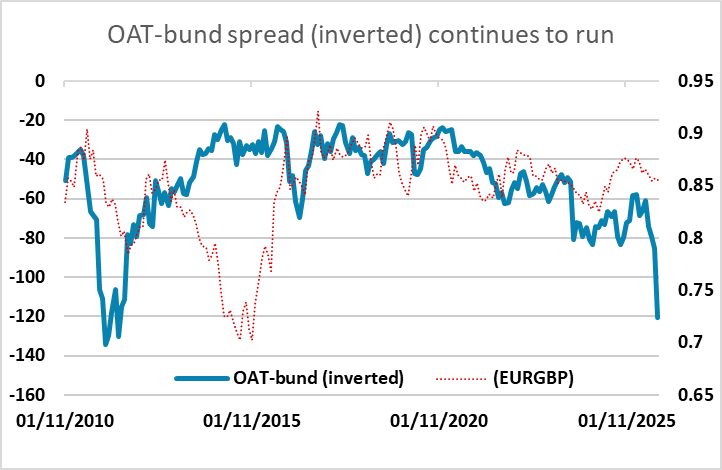
More imminently though, the France situation continues to amplify and could increasingly become the dominant political focus. While the UK has been weighed by caution into the UK Budget, that may prove to be relatively innocuous, while at the same time, OAT-bund spreads continue to accelerate out, pushing on to 120bp~. As noted in the bond outlook (here), there is a real danger of a ‘Truss moment’ for OATs if the market loses control, seeing spreads continue to accelerate into the euro crisis spike zone.
While to an extent this is an intra-euro rotation play, it could start to impinge on overall sentiment especially if the action becomes more impulsive. EUR/GBP could, at a minimum, look to 0.8530 but also extend through there to the wider range floor down at the mid 0.84% if a shift in relative risk positioning and narrative gains traction.
Turning to Thursday, Asia session sees the Japan Tankan, with improved DIs and firm capex plans expected.
In Europe, the market looks for Swiss CPI to rise to 1% from 0.8%, mainly on base effects. Trends remain comparatively sedate here and the SNB remains relaxed about the medium-term outlook at current policy levels and broadly happy to see the CHF giving ground. EZ and UK PMI data is just the final data for Sep.
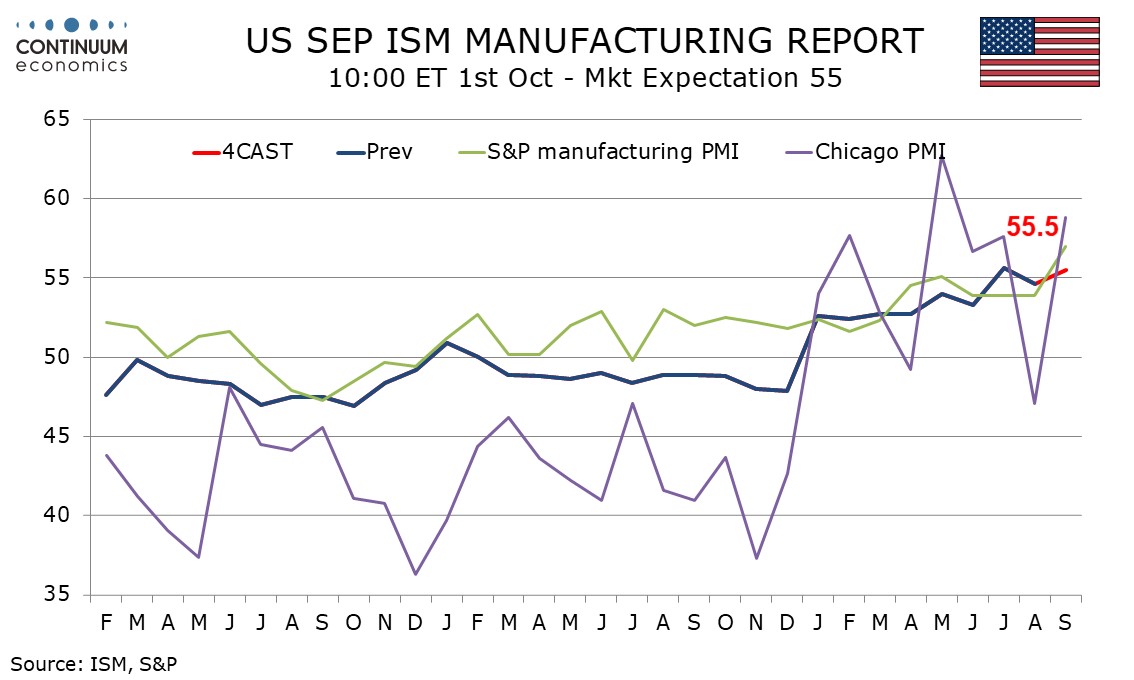
In the US ahead of Friday’s payrolls, ISM provides the main interest, particularly given the impact seen from last week’s high PMI data. We September’s ISM manufacturing index to pick up to 55.5 from August’s 54.6, not quite reaching July’s 55.6 that was the highest since May 2022 but sustaining a clearly healthy picture. So strong but not quite the S&P heights. The usual initial claims are also due. Fed's Barkin and Williams speak again, as well as Logan.