EUR/USD, USD/JPY, DXY flows: back-to-back or election pause could be key $ factor
After Fed hike, whether it goes back-to-back or waits for Dec could be a key factor for the $ near-term
History has tended to favour the follow up moves, but election is the big elephant in the room this time
Oct is heavily loaded symbolically, both in terms of how mkt would price (majority Fed dots only see 1 hike this year) and the political dialogue
Election itself brings potential complex FX implications in some scenarios
At least among the big three, the hawkish lead has rotated among the ECB, Fed and to a lesser extent BoJ, so far containing the net FX impact, if currently leaning the dollar back firmer in range on its latest shift.
If this is to translate into dollar momentum, arguably this makes the October Fed meeting now quite key: back-to-back and the dollar might get more of a lift; wait until a quarterly move in December, for a more programmed move and avoiding the election, and it stays within the expected ECB ‘schedule’.
Looking back, it’s interesting to consider how the start of past tightening cycles (that is, the first hike after the last cut) have proceeded.
Figure 1: How often has Fed gone back to back after 'first hike of cycle', on both modern and reconstructed data
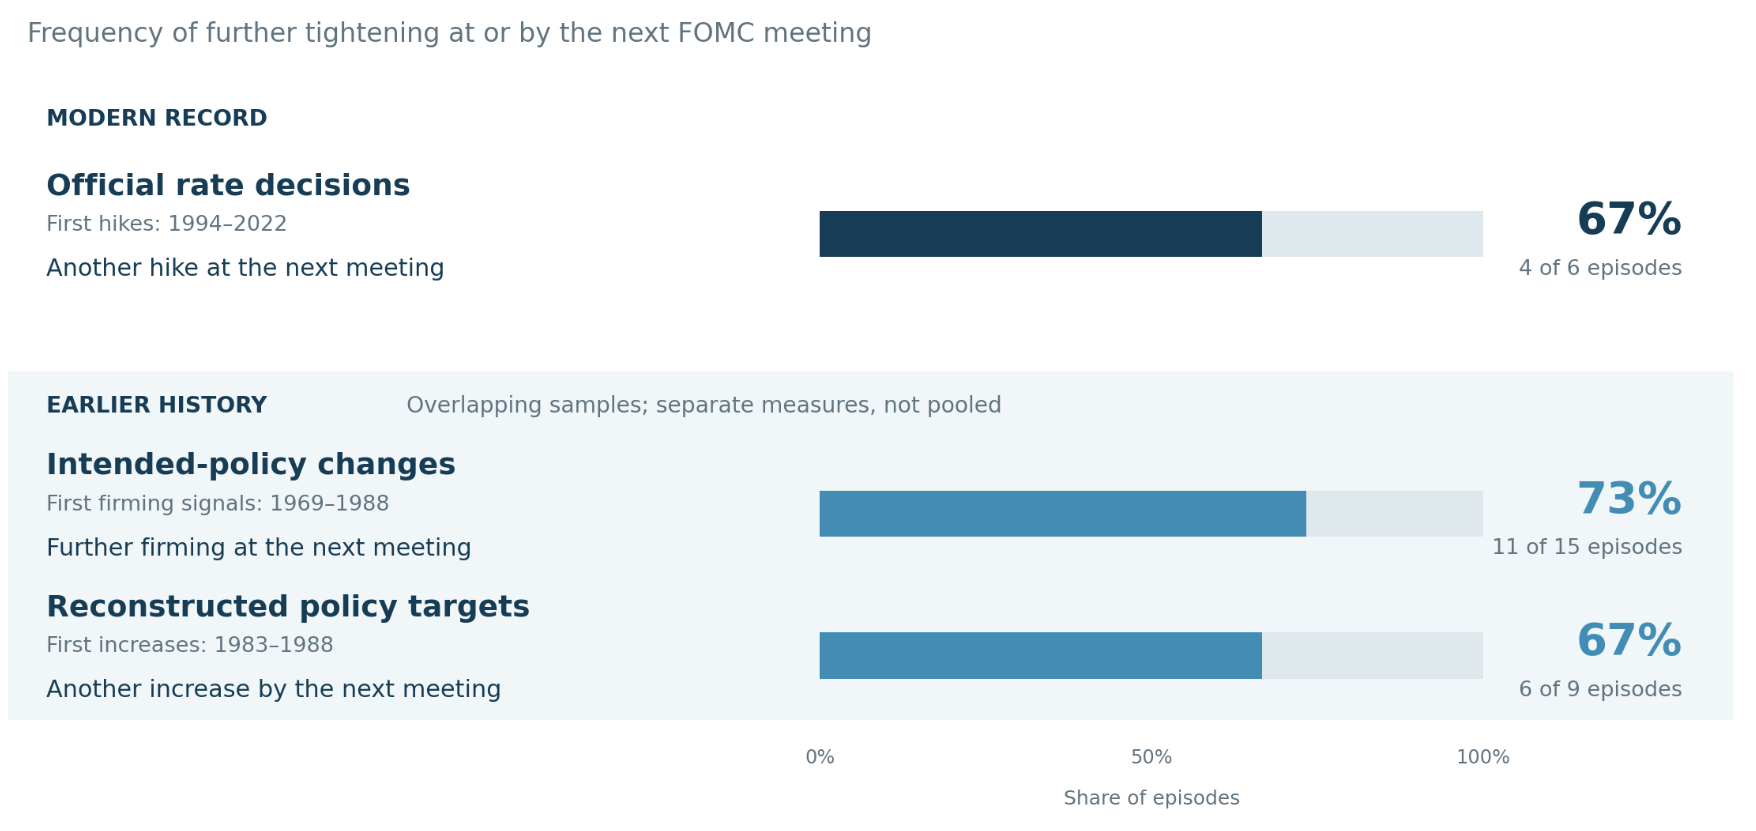
In modern explicit rate announcement times, 4 out of 6 cycles have seen a hike at the following meeting. The exceptions though are 1997, the “orphan hike” when Greenspan explicitly only dabbed the brakes before an extended pause and then the Asian/LTCM crisis. And 2015, the first hike out of the financial crisis. Unless you think that this cycle will end up 1997 style with enough noise and geopolitical resolution to hold off a follow up (in some scenarios, if not currently in play, you might view some parallels), then historically back-to-back has been typical.
Using a reconstructed a longer-term intended Fed Funds rate change series reference, then the next meeting has seen an ‘intended policy move’ around ¾ of the time
The huge elephant in the room of course is the midterm elections, with Trump very vocal on how rates should be lower and that the latest move is a mistake, with political baggage escalating further into the election count down.
There aren’t any exact parallels to this scenario going back (and even if there were they wouldn’t have the Trump context). In more general terms, if you look at whether the Fed hiked again into an election, having hiked the meeting before, it’s a case of 2 out of 3, holding into the 1994 midterms and hiking into the 2004 presidential election and 2022 midterms, though with different context. None of that is likely very relevant (2022 is in theory but a different macro context) and it will likely be more a case of whether the Fed wants to i) allow the market to price in a further hike to Dec as it likely would if it went in Oct and ii) whether it is actively willing to establish credibility as politically independent by a provocative move. Or whether the economic circumstances and the projected rate path (after all, most on the FOMC see just that one hike, with a minority seeing the two) make Oct unnecessarily aggressive and play to anti-Fed-rhetoric. Our assumption is that they wait for December – see (here) for more on that.
Which way the Fed go could be a key factor for the dollar on a trading basis over the next month or so, along – of course – with the election itself. We discuss elsewhere - see (here) - how the election itself brings its own risks and potential complex FX implications.