FX Daily Strategy: Asia, Sep 15
Spec data shows mkt turned long kiwi - often a contrary indicator
Risk sentiment turns weaker, squeezing dollar, as oil catches up with sentiment; AI complications
UK labour market data, followed by CPI, provide the run in to the next BoE meeting
While central bank meetings remain the central focal point on the calendar, the global backdrop is doing its best to gatecrash in the meantime. It’s not that the risks from either the widening energy pinch point pressure (or indeed from fresh AI wobbles) have come out of nowhere. They’ve been building up very visibly in recent days, especially the widening concerns in the Middle East. Some prominent investment bank calls that Brent might move from a <$100 cap to instead returning to $120 have been out there for a number of sessions and current action reflects that re-pricing. It’s not just the Iran deadlock into the US elections as much as the broadening arena into Saudi and the Bab el-Mandeb strait.
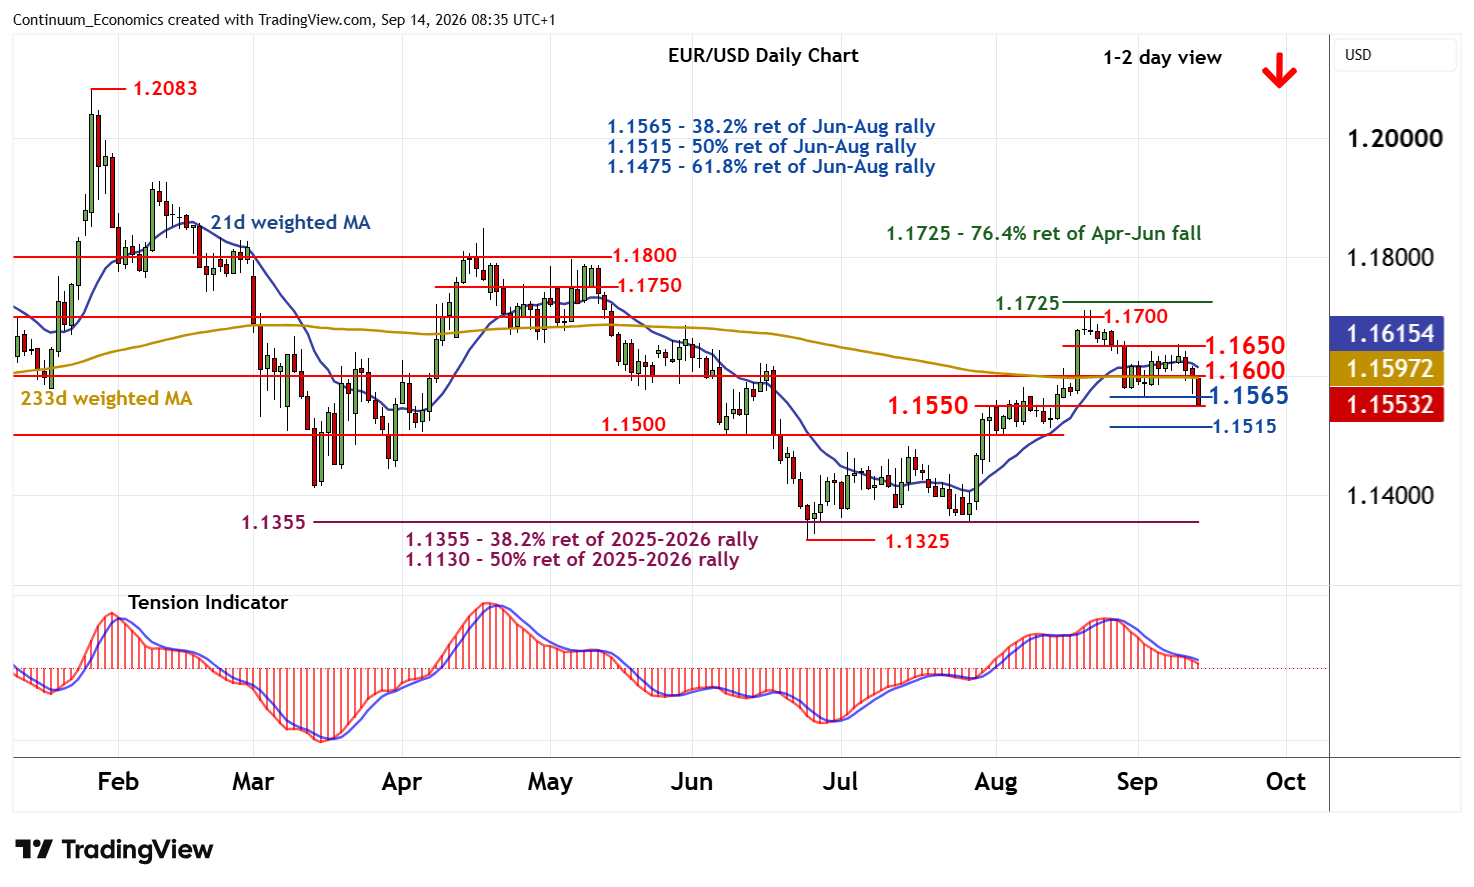
We noted that the trading market keeps finding itself caught offside of late by the range edge feints, and we are seeing it again on the latest shift back to dollar risk-off support. EUR/USD in particular has reversed bias from 1.16+ back to 1.1550- in terms of early week skew, also supported by the shift in expiry profiles. 1.15 is the next lower reference if the move gains traction within the wider recent band. USD/JPY is also being driven into the recent bounce highs in the mid 154s, potentially looking to test out the strength of supply up at 155.00-155.25, albeit still with one eye on the approaching BoJ meeting.
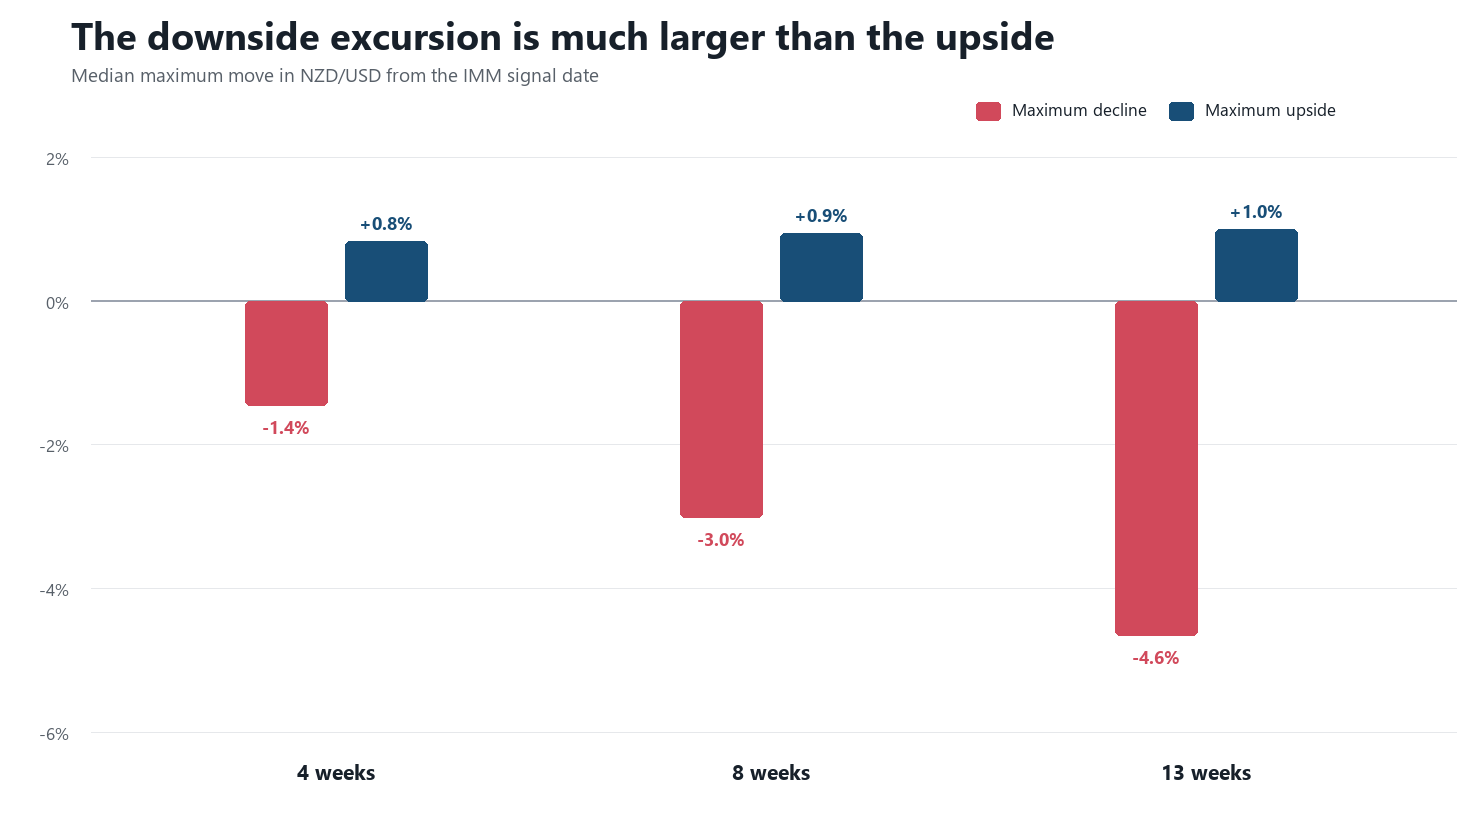
The latest IMM data also brings an interest perspective on this. Not only have dollar longs recede from extremes back into more normal bounds (if still net long overall) but the shift to long NZD catches the eye. We discuss this in more detail in the report ‘kiwi longs as contrary indicator’ (here).
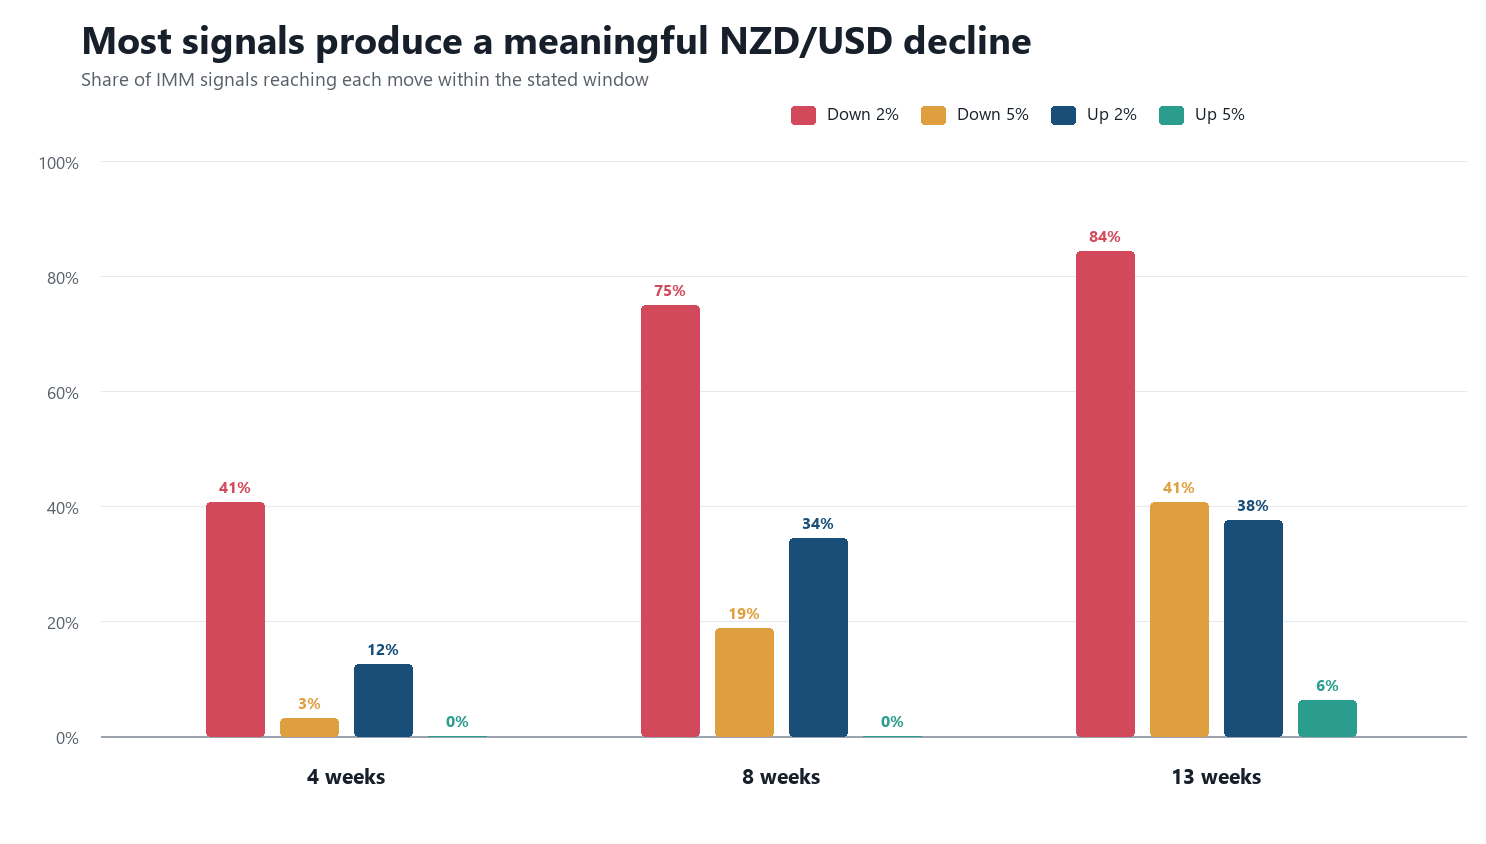
The broad message is that when the market has flipped long NZD over the last 15 years, that has tended to be more indicative of excess than a bullish trigger. There is a strong skew, in terms of both probabilities and scale of moves, towards a subsequent kiwi correction. That’s interesting in its own right, if slightly anticipated by the recent price action, but also perhaps indicative of a broader prevailing risk positioning across wider risk/usd right now.
Turning to Tuesday, the main interest today comes from UK data in the build up to the next BoE meeting, starting with labour market data. Expectations are for the unemployment rate to tick up to 5% from 4.9% and for average earnings to edge down in 3m yr/yr terms to 3.9%, with ex bonus a little lower at 3.5%. Aug payrolls data also to be watched to see if the recent string of modest declines continues, or whether some service driven growth stabilisation in the summer has stopped the rot there. Labour market data has been sufficiently soft in recent months to be one of the key factors helping keep the BoE one the sidelines even with the high headline CPI prints.
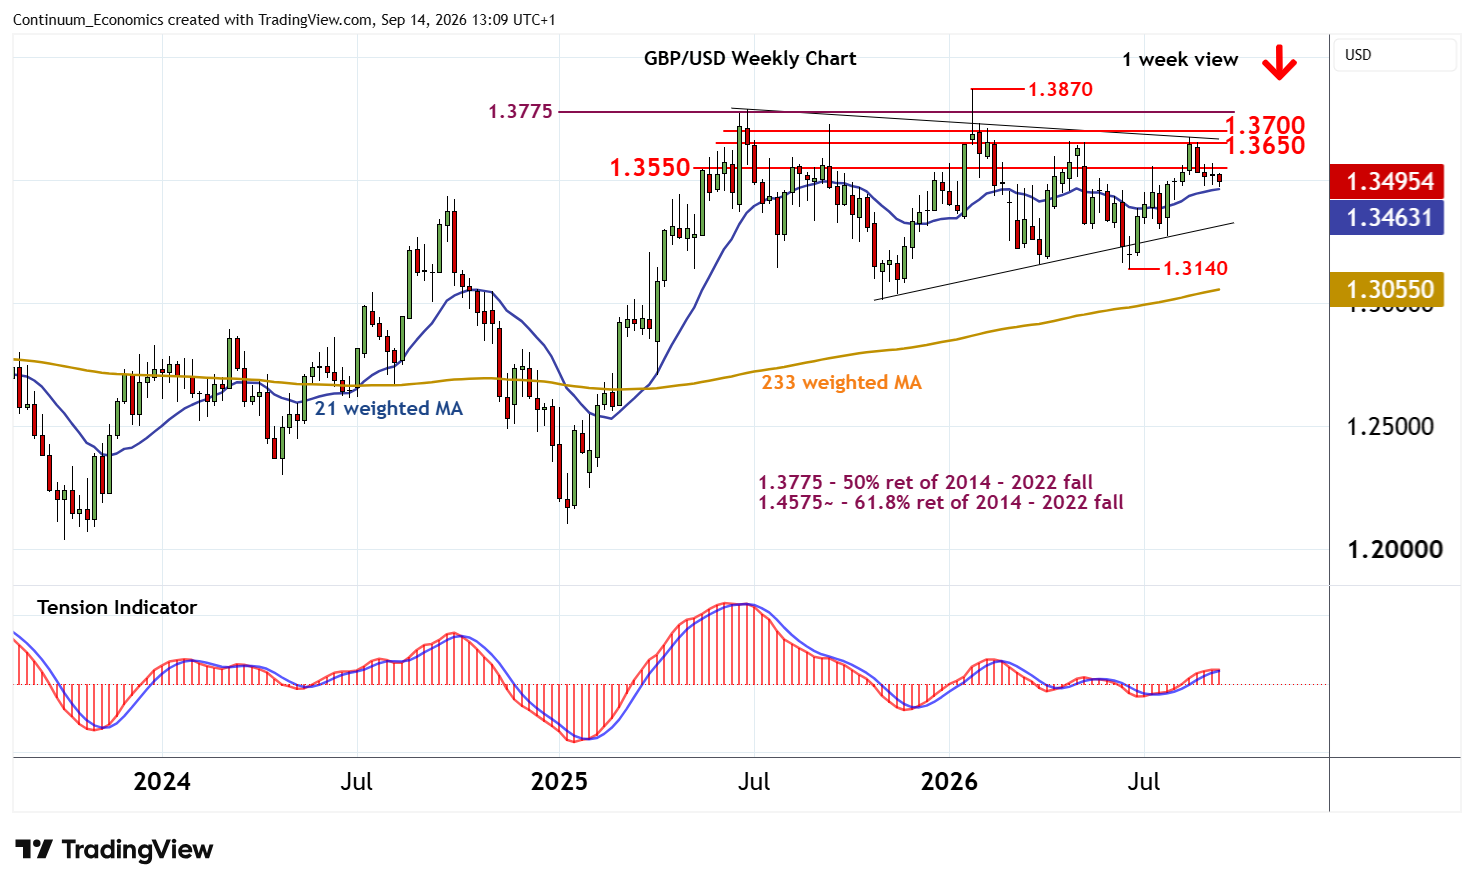
EUR/GBP continues to see range capping hold, notwithstanding the BoE patience compared to other majors, by virtue of renewed energy weight on the euro and the technical trade. Cable is under downside pressure along with most pairs early week, pressuring support at the 1.3475 Fibonacci retracement ahead of congestion around 1.3500.