U.S. Initial Claims, November Philly Fed - Hints of slowing
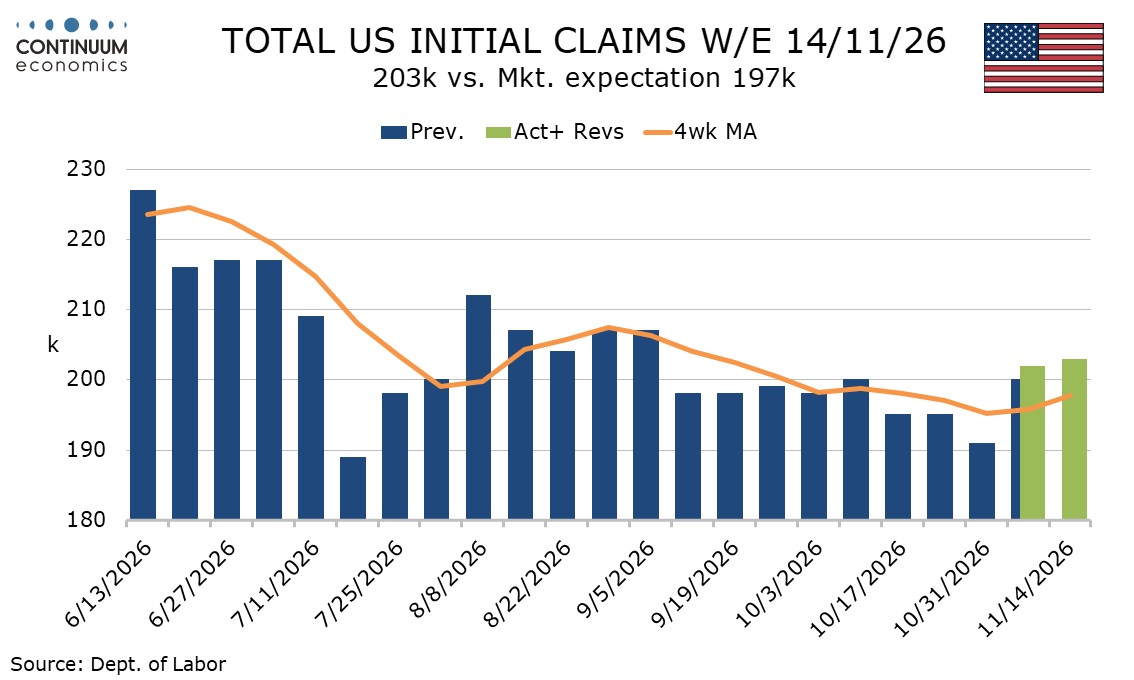
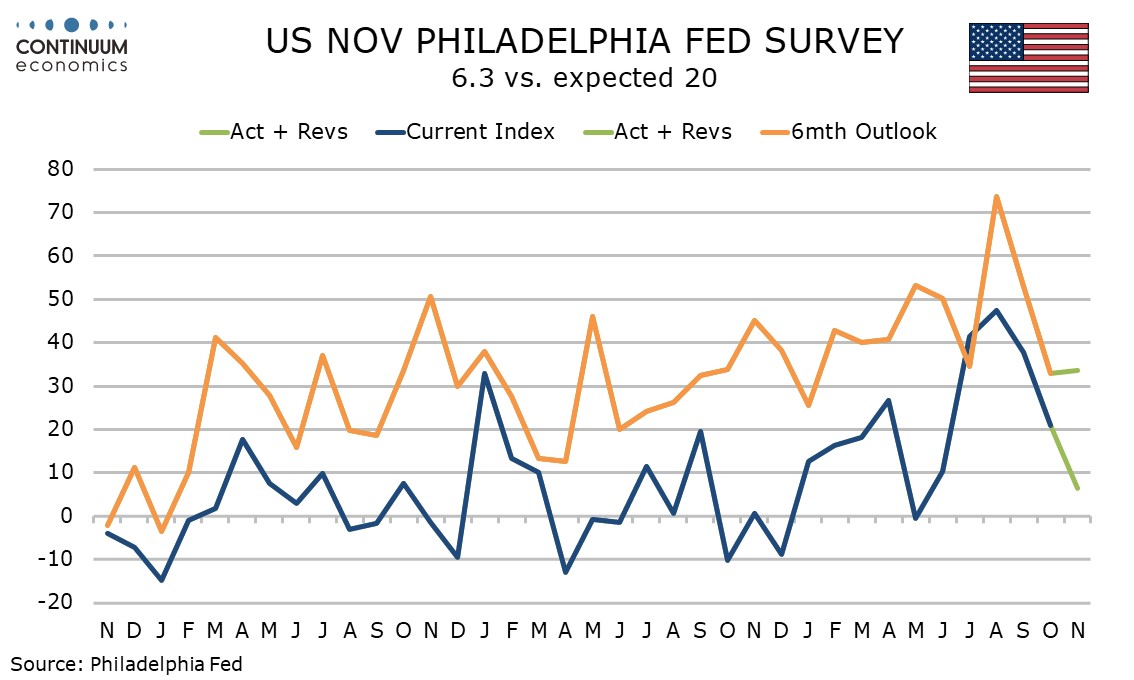
Initial claims at 203k from 202k, while still low, are the highest since September 7, and support our view that November’s non-farm payroll will be slower than October’s with a moderate rise of 95k. November’s Philly Fed manufacturing index, at 6.3 from 20.9m, is also weaker than expected.
The latest initial claims data covers the survey week for November’s non-farm payroll. While the weekly data may be moving slightly higher, the 4-week average is almost identical to the 198k seen in October’s payroll survey week.
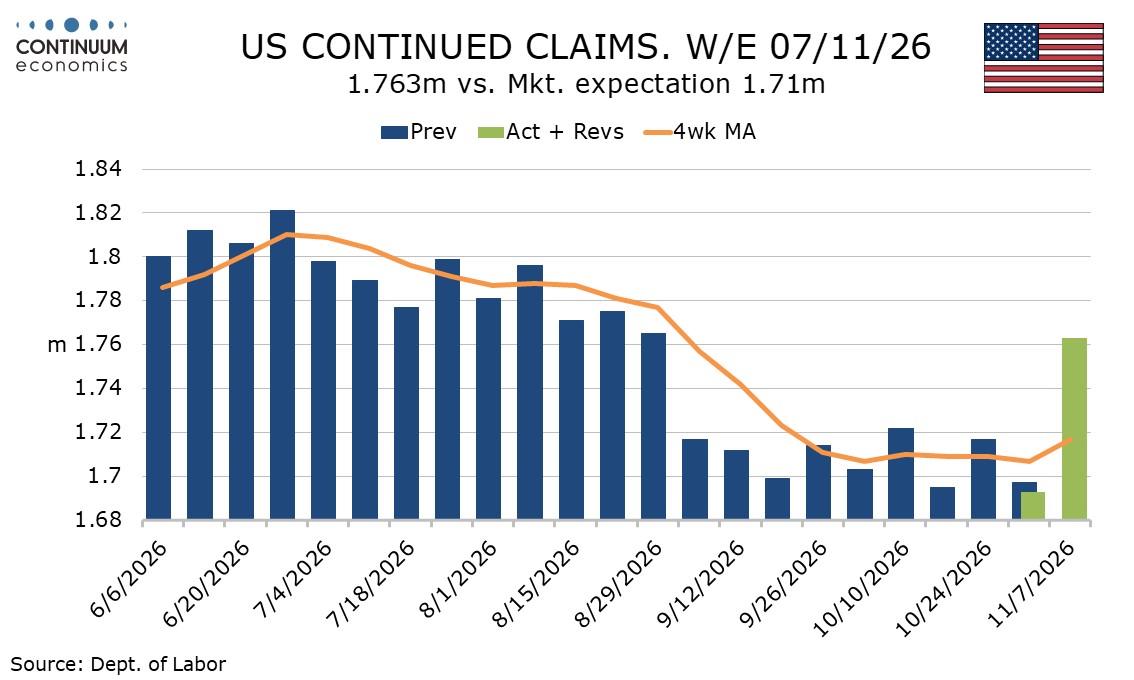
Continued claims cover the week before initial claims and saw a sharp 70k increase to 1.763m, the highest since August 29, following preceding figure that was the lowest since March 2023. It is too early to call a change in trend but if the rise is sustained it would suggest that more people are losing jobs in a change from the low hire low fire picture we have got used to.
November’s Philly Fed manufacturing survey is the weakest since what proved a brief dip below neutral in May. New orders at -0.4 from 4.3 actually did fall below neutral in November, for the first time since December 2024.
The data is broadly consistent with a weaker Empire State manufacturing index released on Monday, of 7.8 versus 25.5 in October.
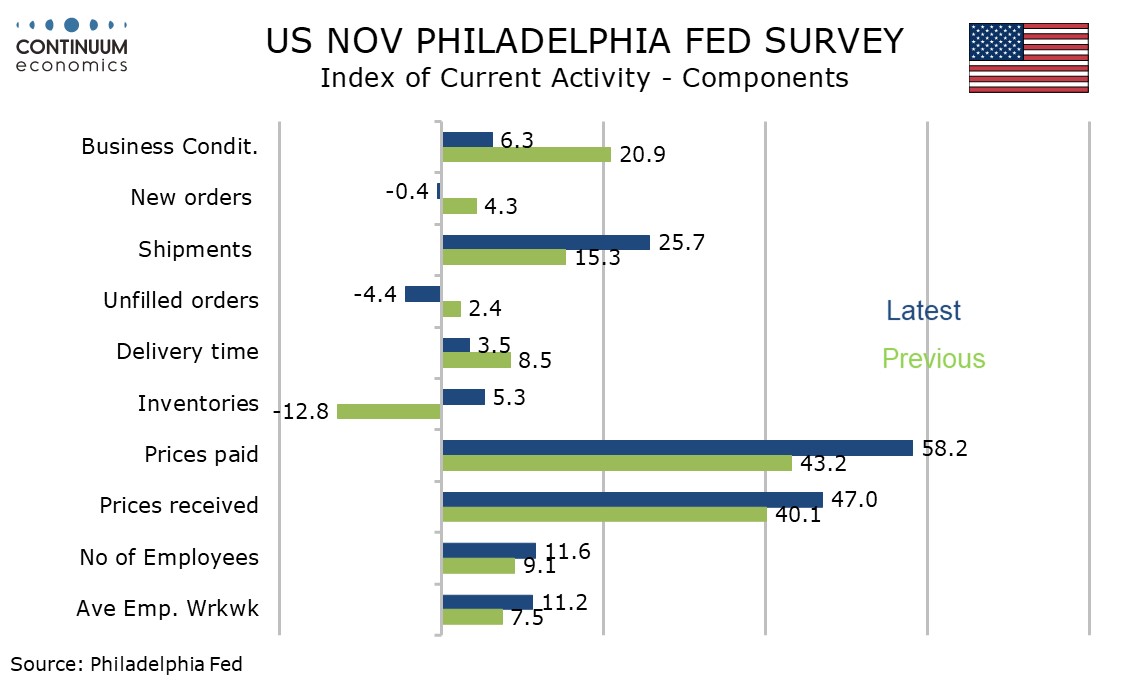
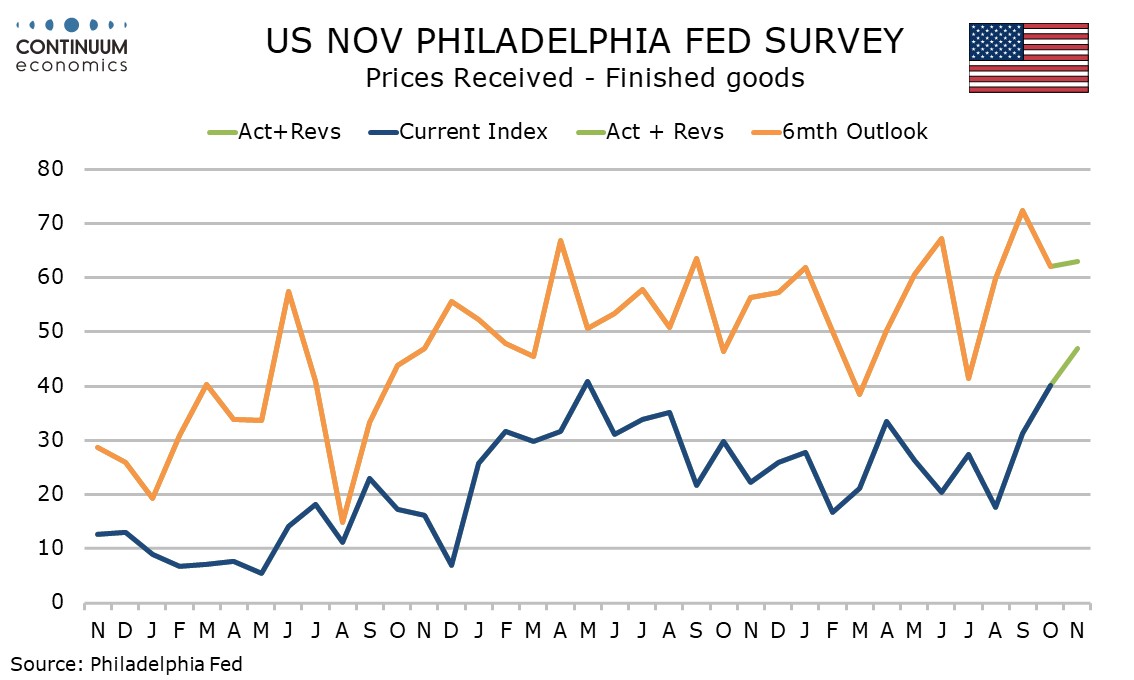
Philly Fed price data contrasts generally slower Empire State prices data, with prices paid at 58.2 from 43.2 and prices received at 47.0 from 40., the highest since April and more worryingly June 2022 respectively.
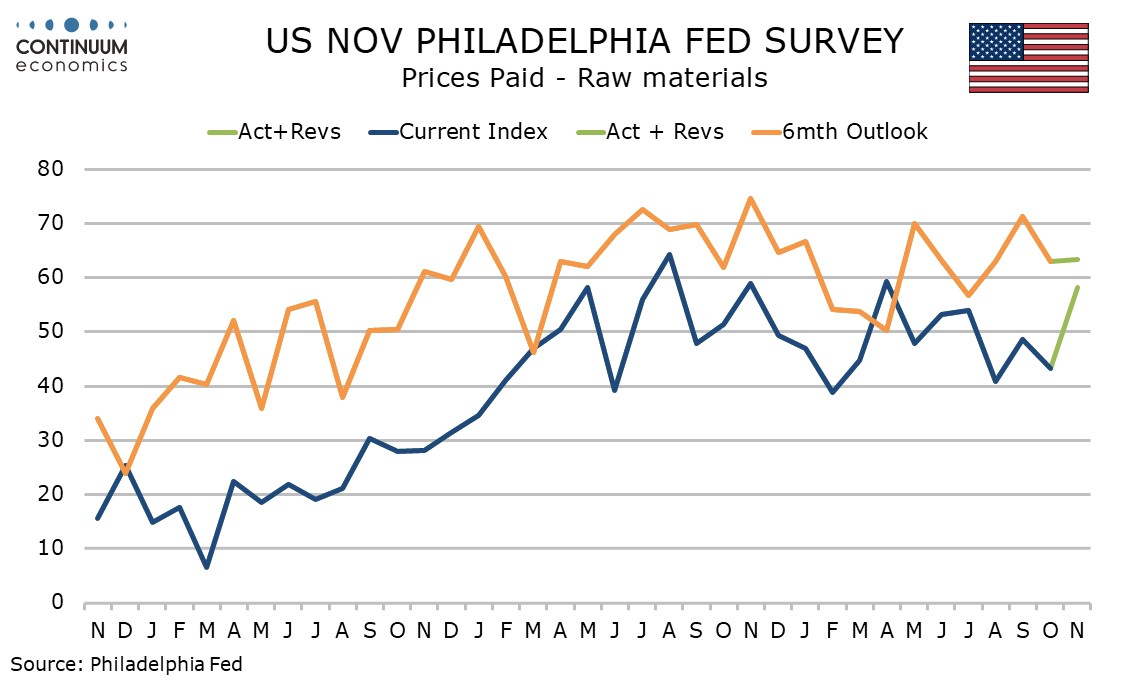
Six month expectations in the Philly Fed survey, for activity, prices paid and prices received, were little changed from their October readings.