U.S. Q3 GDP strong outside net exports
There are no major surprises in the latest US data, but it is generally healthy, with Q3 GDP slightly stronger than expected at 3.4%, with the details strong outside net exports. September personal income rose by 0.2% with spending up by 0.5%, both slightly slower than expected. Core PCE prices rose by 0.3% as expected and by 2.5% annualized, also as expected. Initial claims at 194k from 195k remain very low indeed and imply the economy remains close to full employment.
September’s core PCE price index rose by 0.32% before rounding. August was revised to 0.3% from 0.2% but before rounding the revision was marginal. To 0.26% from marginally below 0.25%. Yr/yr core PCE prices at 3.1% from 3.0% are at a 4-month high as are overall PCE prices at 3.6% from 3.4%.
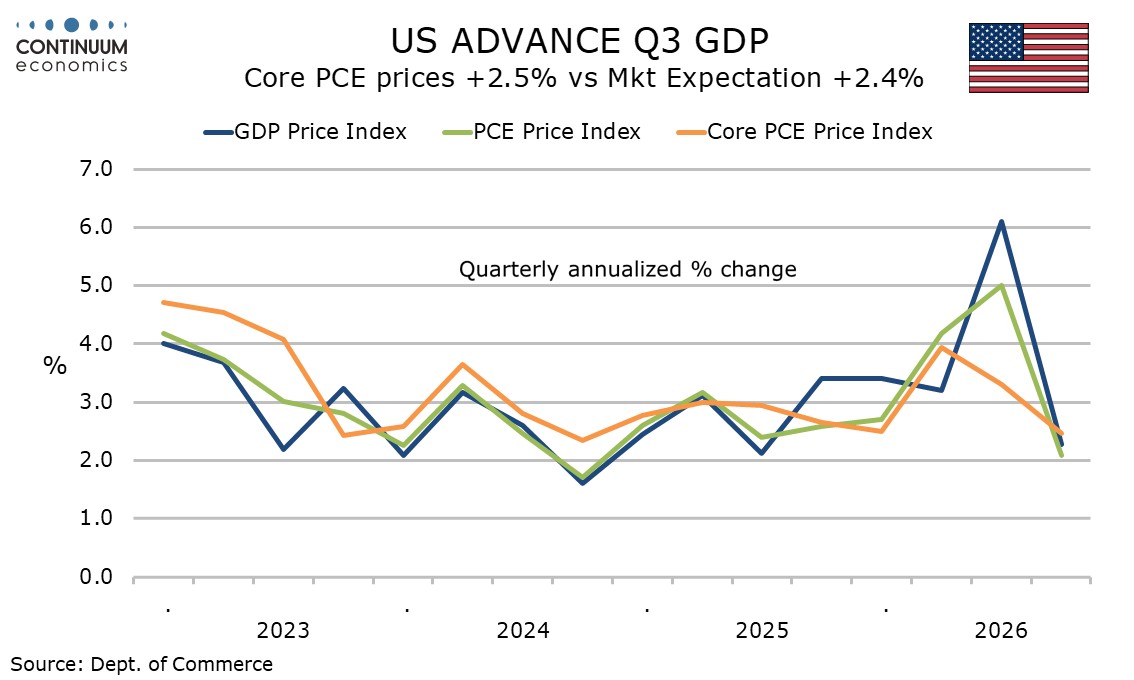
For Q3 the core PCE price index of 2.5% annualized is down from 3.3% in Q2 and 3.9% in Q1 but still above target. Overall PCE prices met the 2.0% target on an annualized basis as energy prices came off their highs, but energy prices saw renewed gains in September, which will get Q4 off to a firm start.
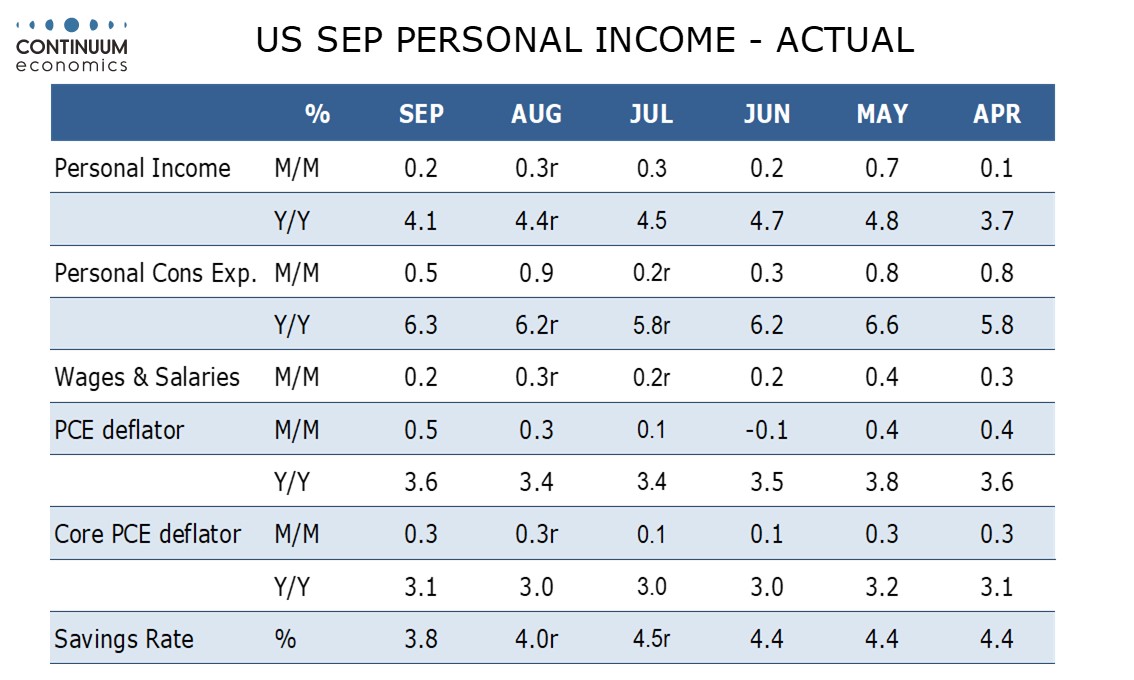
The 0.2% gain was consistent with wages and salaries which have lost momentum given limited employment growth and slowing wage gains. The 0.5% rise in spending saw services also up by 0.5% while retail was not quite as strong as retail sales data implied. The savings rate of 3.8% from 4.0% is the lowest since October 2022, Real disposable income rose by 2.3% annualized in Q3, but only 1.0% yr/yr.
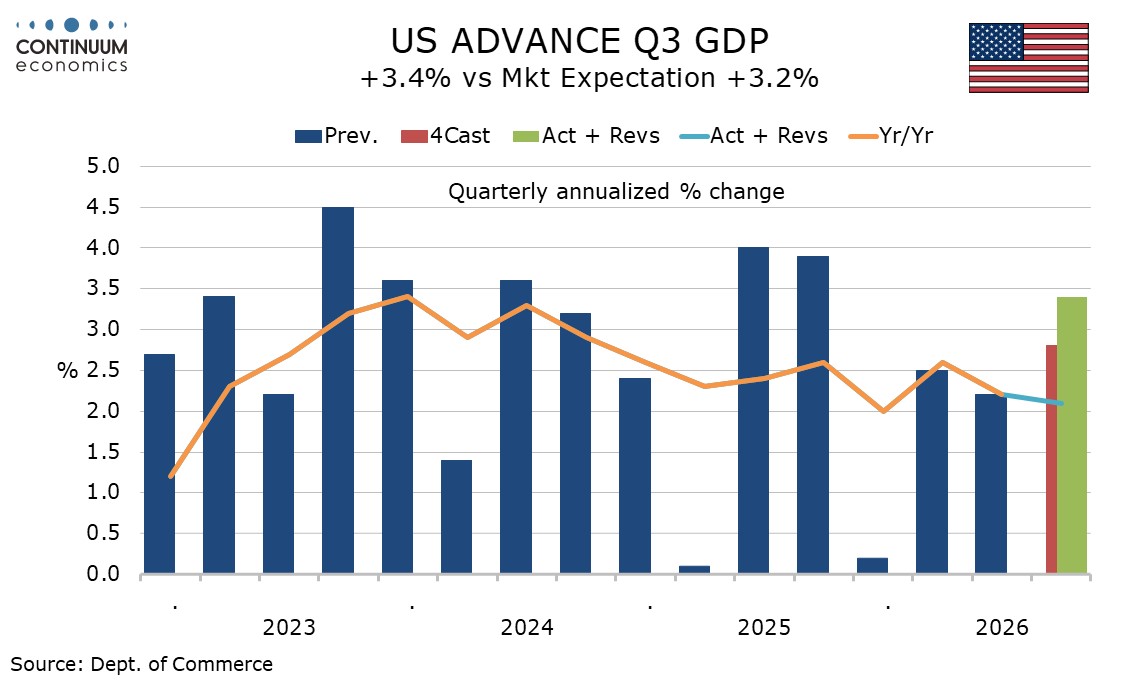
Consumer spending rose by a strong 3.8% annualized in Q3, matching its Q2 outcome with both quarters up by 2.5% yr/yr. Business investment at 12.7% was very strong indeed and the highest fastest since Q3 2020 corrected a plunge during the pandemic. Housing investment however slipped by 3.3%, after increasing in Q2 for the first time in six quarters.
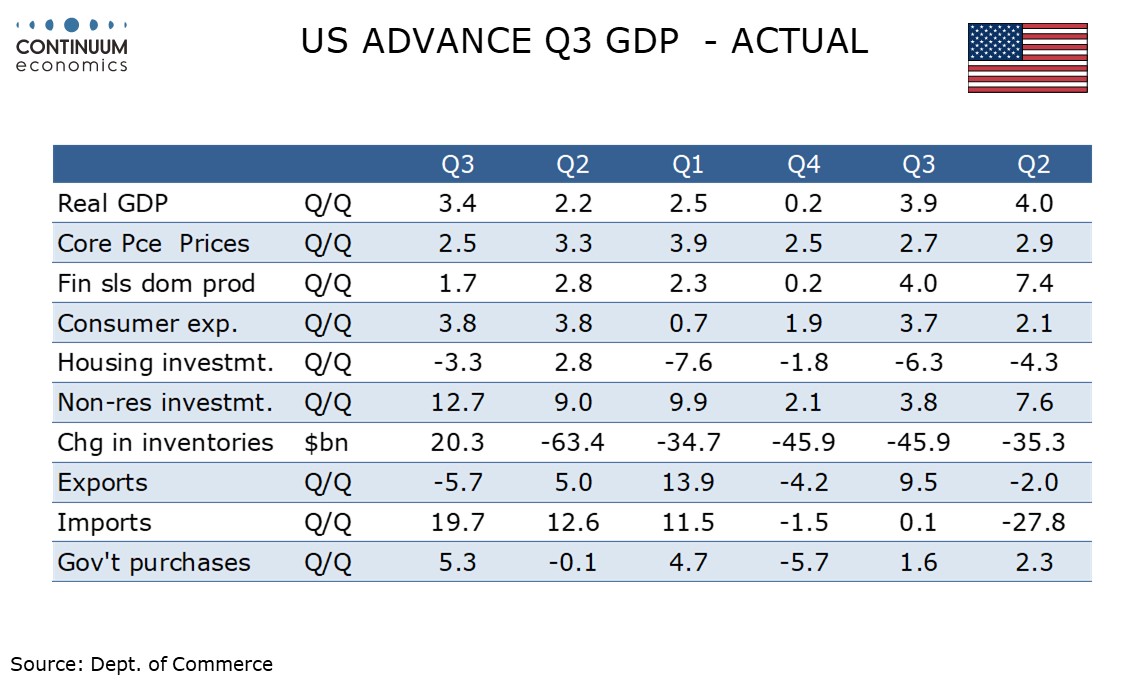
Government was strong, up by 5.3%, led by strength in Federal spending, which was surprisingly not confined to defense. State and local government saw a fall of 0.1%. All this saw final sales to domestic purchases up by an impressive 5.0%, the strongest increase since Q2 2021. Domestic demand looks very strong.
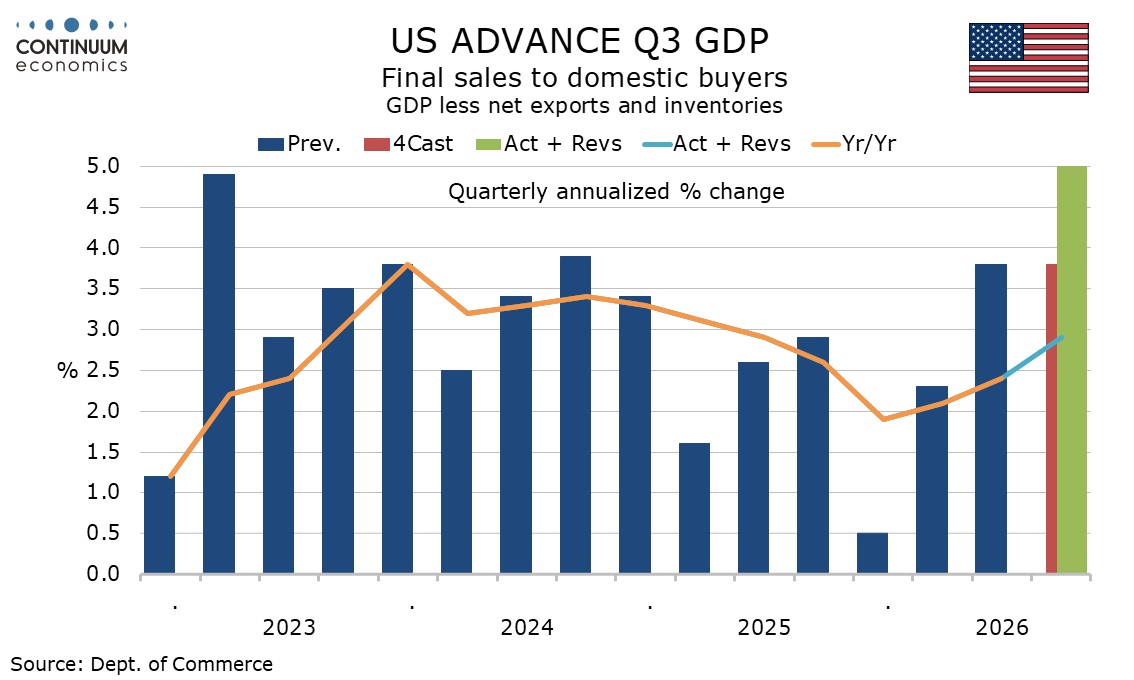
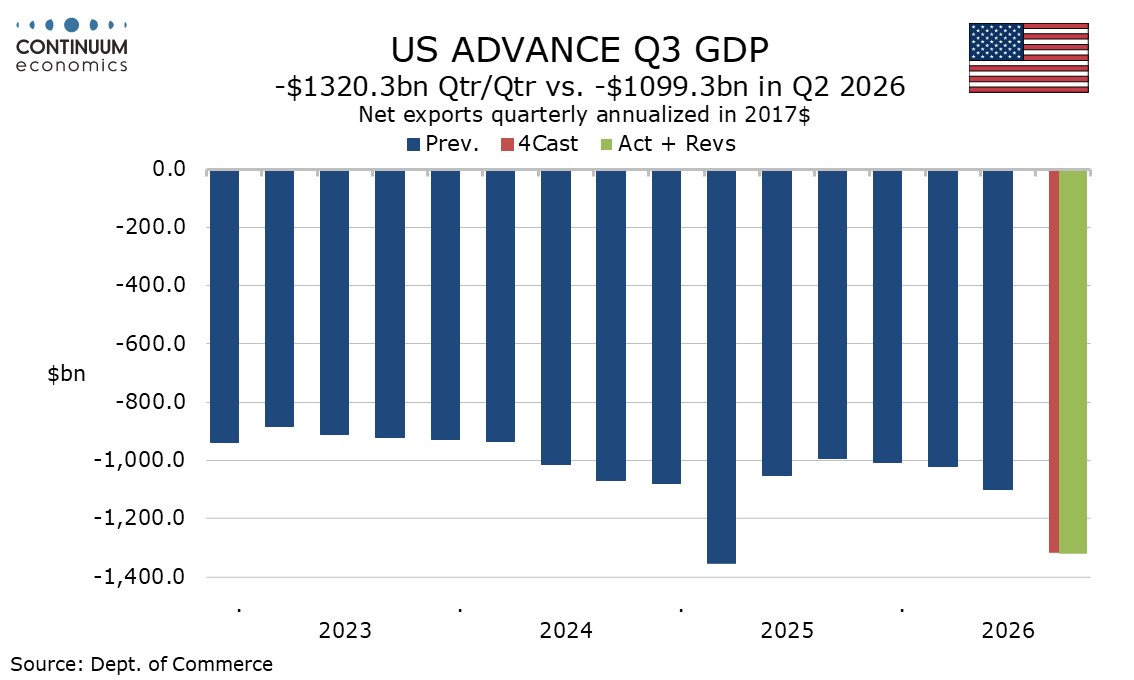
Inventories saw their first increase since Q1 2025’s pre-tariff surge, explaining half of the rise in GDP. The 1.7% rise in final sales (GDP less inventories) is unimpressive at first glance but the only negative in this was net exports, which took a very large 3.4% of GDP. Imports surged by 19.7% fueled by the strength of US demand, particularly for investment goods. Exports had a weak quarter, falling by 5.7%. The post-tariff narrowing in the trade deficit is clearly over.