U.S. October Retail Sales - Continued underlying momentum
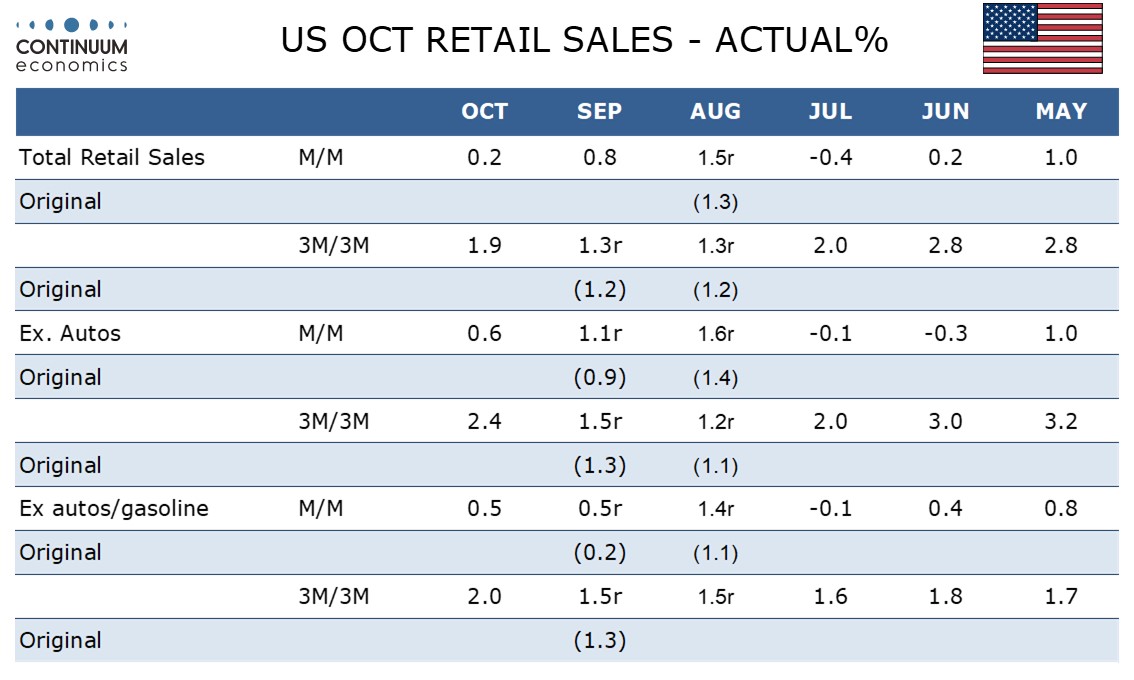
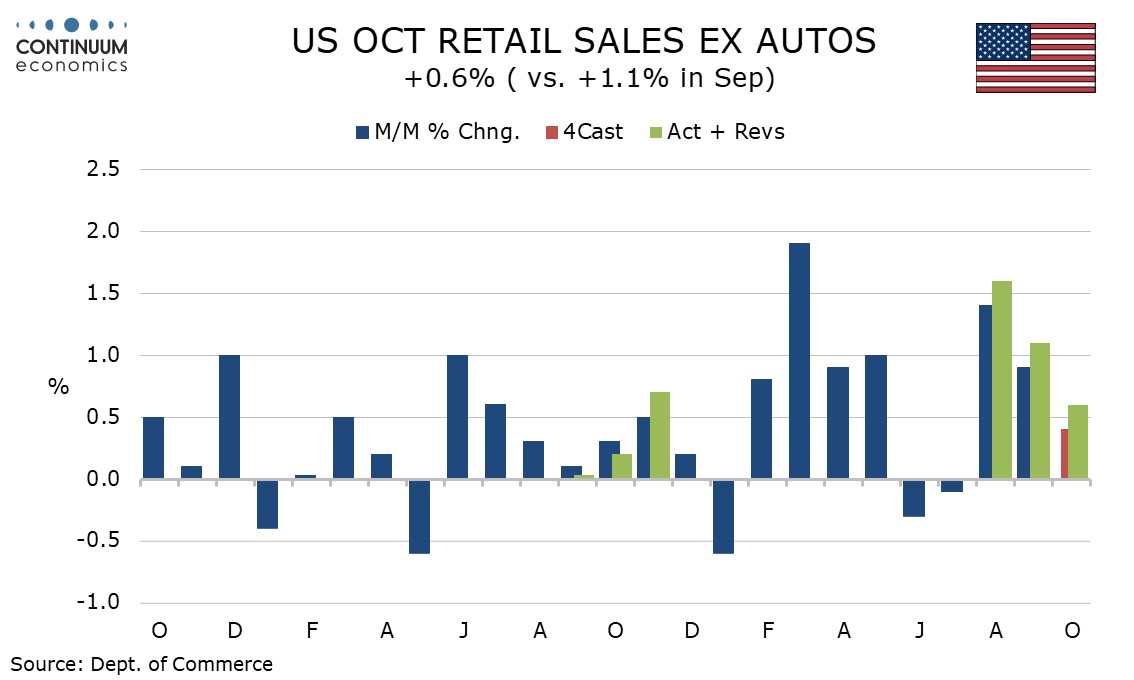
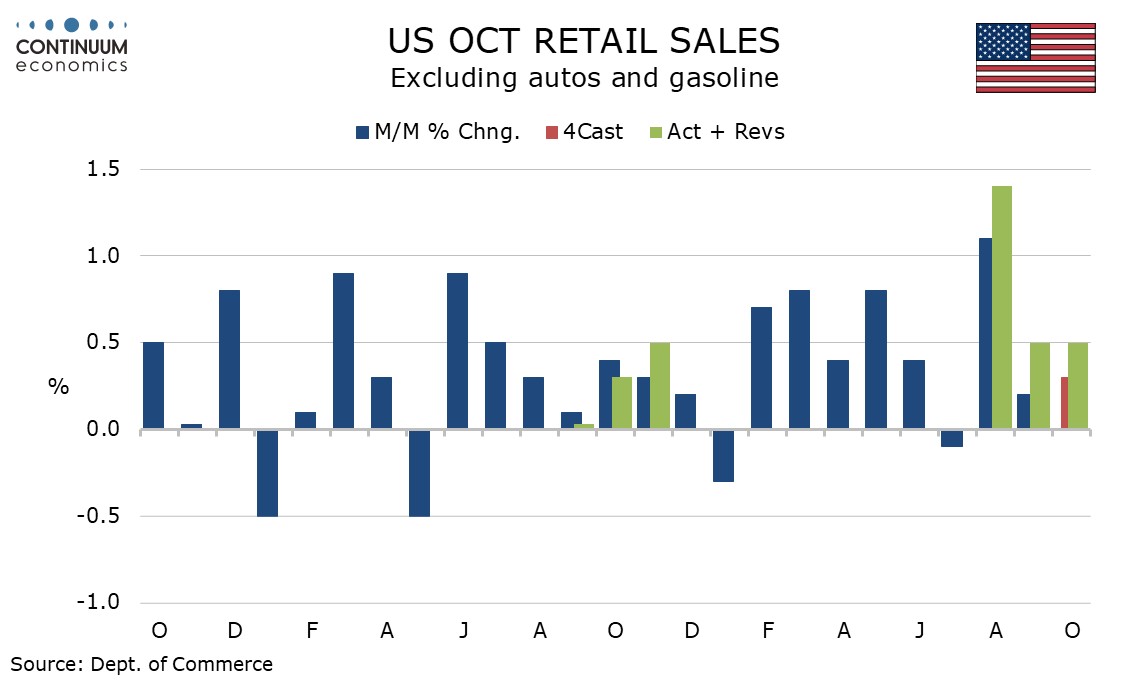
October retail sales are weak at 0.2% overall as autos see a soft month, but in line with consensus. Ex autos the rise is respectable at 0.6%, with the control group that contributes to GDP rising by the same amount. Sales rose by 0.5% ex autos and gasoline.
CPI showed prices of commodities up by 0.4% in October, so that suggests a subdued month for real retail sales, but with commodity prices ex food and energy up by only 0.2% there still seems to be respectable momentum outside a weak month from autos, which had been signaled by industry data.
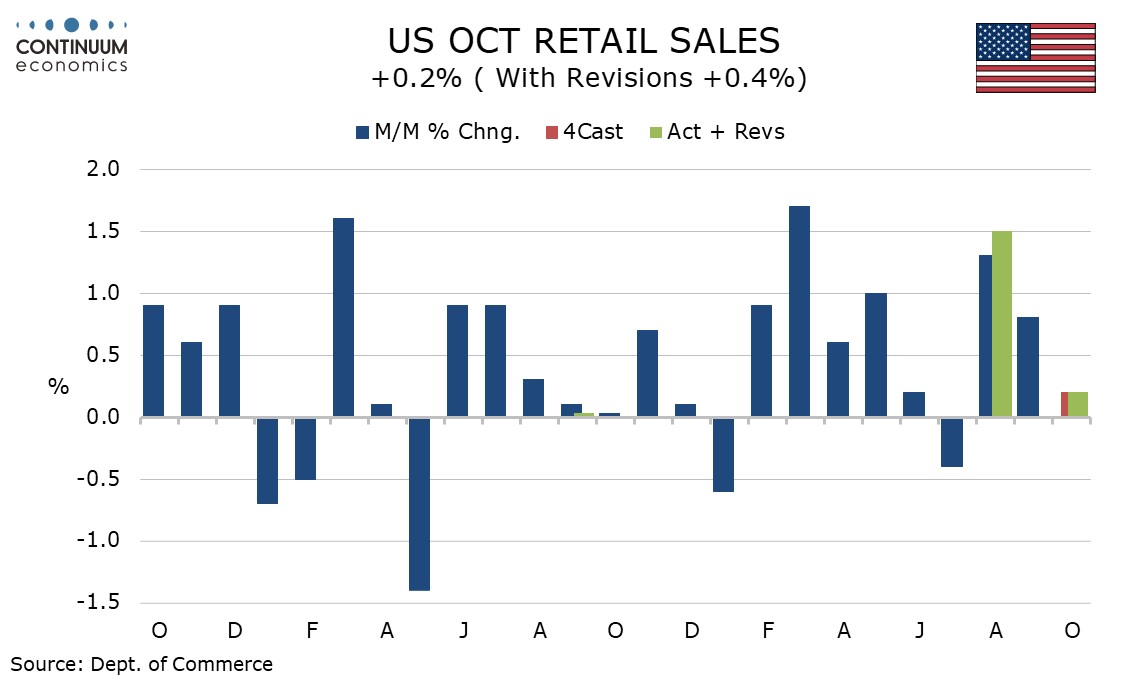
The resilience of retail sales comes despite the headwind of spending outpacing real disposable income, and more recently rising interest rates. Equity strength has been supportive but may be fading now. That October saw a broadly strong employment report is supportive for spending.
Back month revisions were minimal overall, with September unrevised at 0.8% and August revised up to 1.5% from 1.3%. However they were more significant ex auto and gasoline, with September revised to 0.5% from 0.2% and August revised to 1.4% from 1.1%.
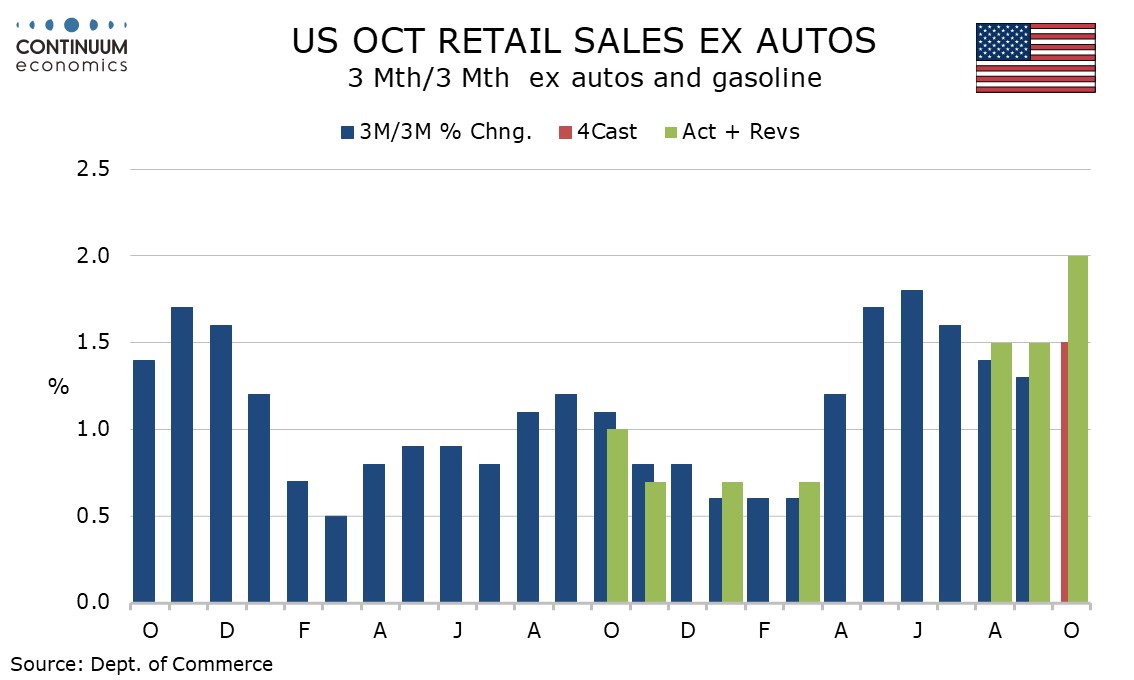
3 month/3 month data looks firm with gains (not annualized) of 1.9% overall, 2.4% ex autos and 2.0% ex auto and gasoline, the latter the strongest since June 2022. The other two series are at 3-month highs.
The main areas of strength ion October were a 4.7% surge in miscellaneous stores, a 1.5% rise in health and personal care, and a 1.2% rise in non-store retailers. A 1.5% rise in gasoline was price-related.