Preview: Due November 17 - U.S. October Retail Sales - Momentum solid but some risk of slowing
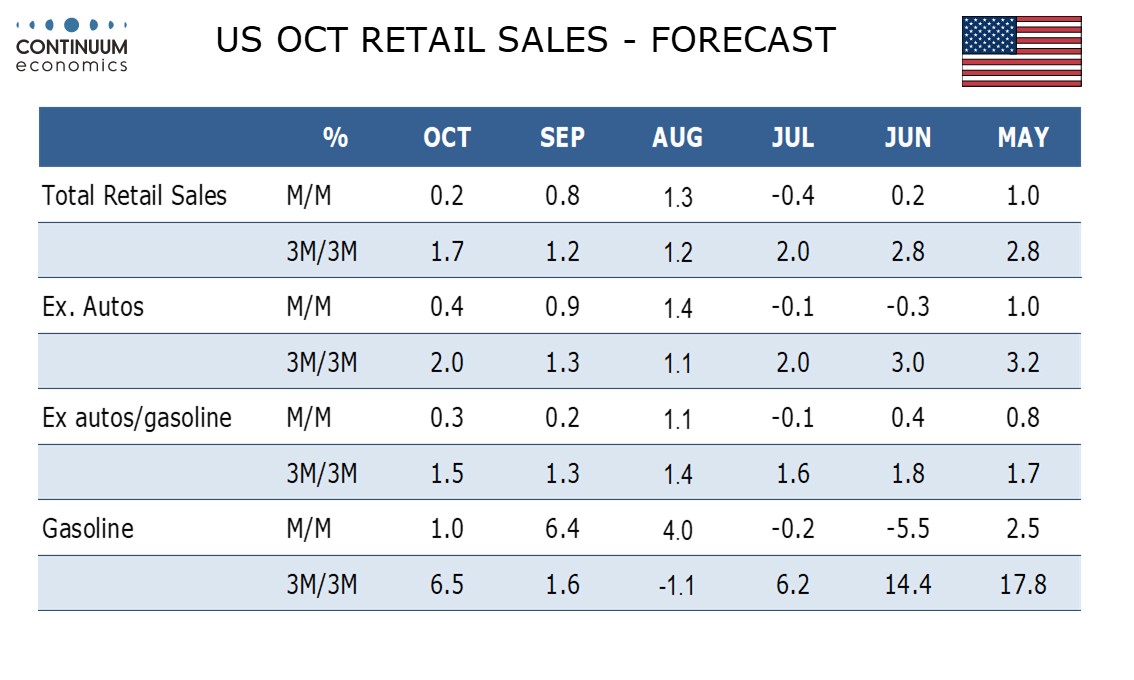
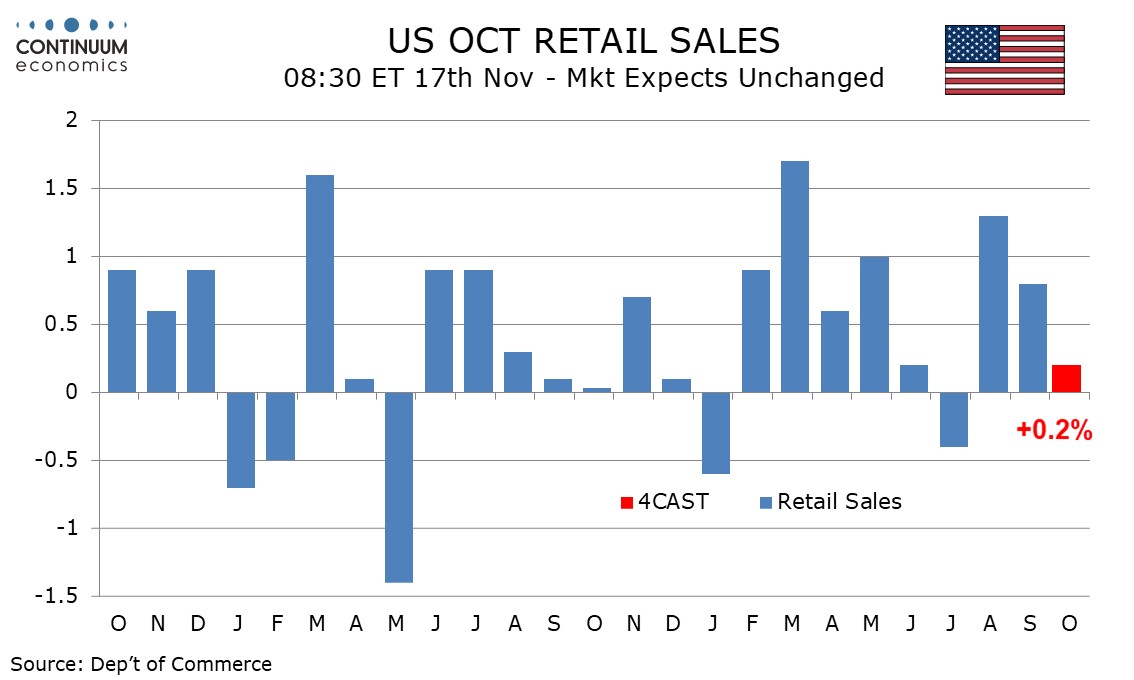
We expect October retail sales to rise by 0.2% overall and by 0.4% ex autos, with a 0.3% increase ex auto and gasoline. There is some risk that Q3’s impressive resilience in retail sales will fade in Q4, but we do not expect October data to give any strong signals of that.
Consumer spending has been running well ahead of real disposable income, with equity strength the most obvious explanation for that. Jitters in equity markets do increase the risk for a slowing, but a strong October employment report is supportive for consumer spending.
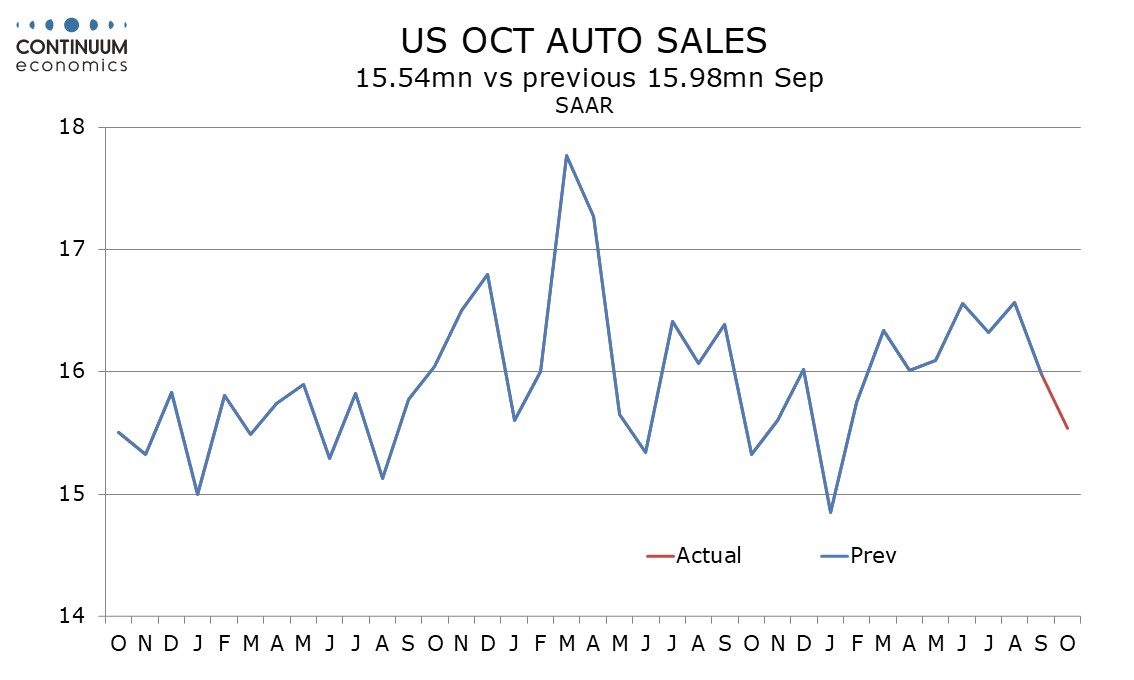
Industry data suggests that autos will see some slippage. CPI data suggests prices will not provide much support to autos, though overall prices were firm in October.
Gasoline prices will be a modest positive as will those for food. Overall we expect underlying momentum ex autos and gasoline to persist but eating and drinking places are vulnerable to a correction after two strong months while weakness in housing may weigh on building materials.
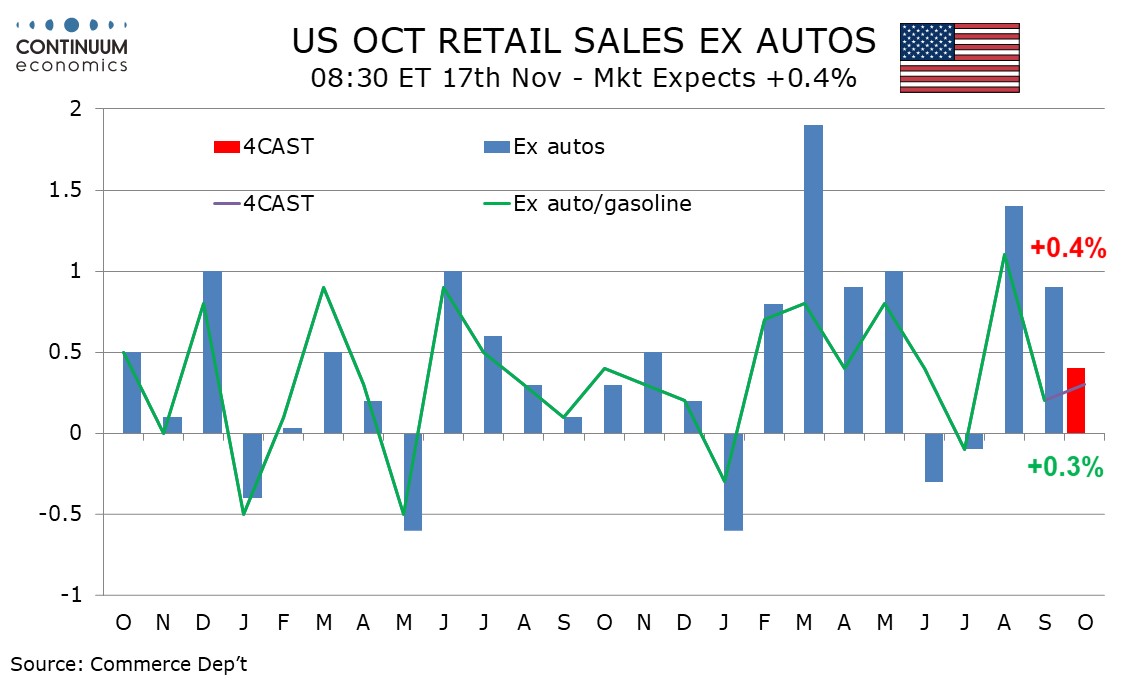
This will be a second straight subdued month ex autos and gasoline but after a strong August the 3-month/3-month pace will still look stable and solid entering Q4.