FX Daily Strategy: Asia, Sep 17
Fed pivots to catch up with the curve on inflation, dots see 1 (to 2) more hikes
Swift turn does enough to bolster dollar, cable especially pressured unless BoE changes tune
USD/JPY runs into supply up here, with the BoJ Friday now critical, even more important it matches the pick up in pace
The Warsh-Fed is certainly going to keep the market on its toes, with the Sep meeting proving to be quite a significant hawkish pivot. The clear message from the meeting was that the Fed is now very much taking inflation being elevated seriously, with no qualifications, or certainly determined to signal so, perhaps chastened by recent market action.
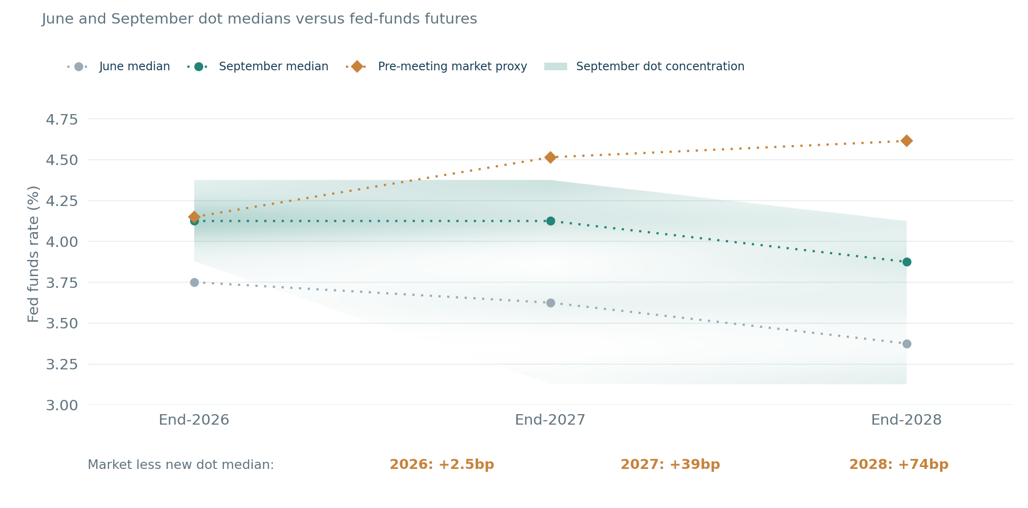
The projections reflect this perceived greater need to quite swiftly recalibrate policy tighter. Dots suggest the majority probably favour one more hike this year and one possibly even early next, based on current projections at least. A minority prefers both additional hikes to come this year. The general message is a quick catch up move to try and get back up to the curve on inflation and get policy to a less apparently accommodative position.
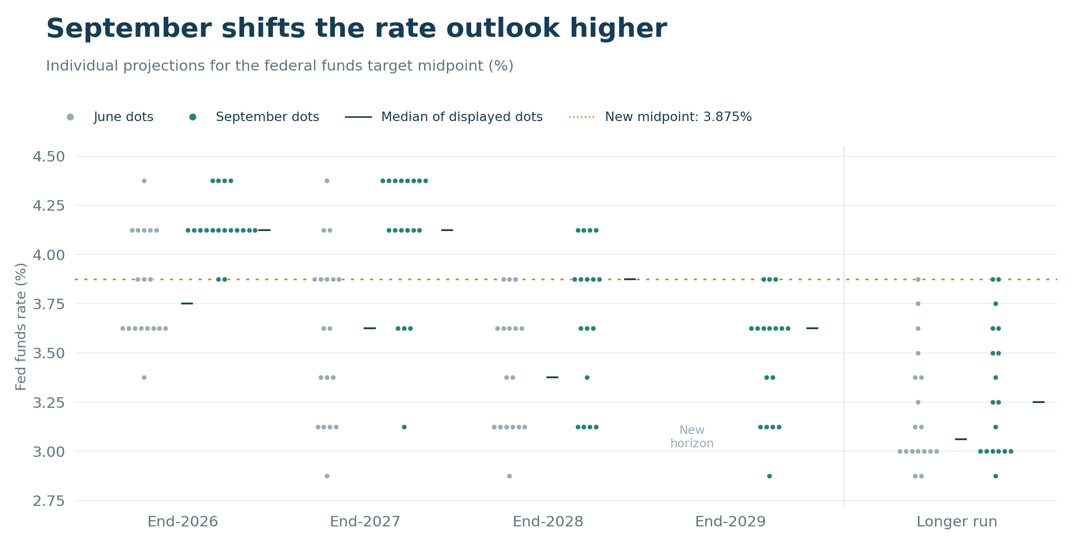
The update fully validated the market shift for this year - with the skew actually on the hawkish side - to then not quite meet the fullest market pricing (at least including policy uncertainty premium) thereout. The shift in tone and front-loaded move to favour follow up has been enough to give the dollar a fillip, notwithstanding the market already having more backed in further down the track.
This pivot may actually prove a U-turn too far later into 2027 if geopolitical developments do surprise positively into next year compared to now and households prove unable to fully sustain their current resilience - see 'FOMC - Further tightening likely if data holds up' (here). For now though, the meeting ands its extra urgency and speed up has bolstered market expectations and with it the dollar.
EUR/USD’s break down takes it initially to around 1.1475~, 61.8% retracement, with 1.1420 below.
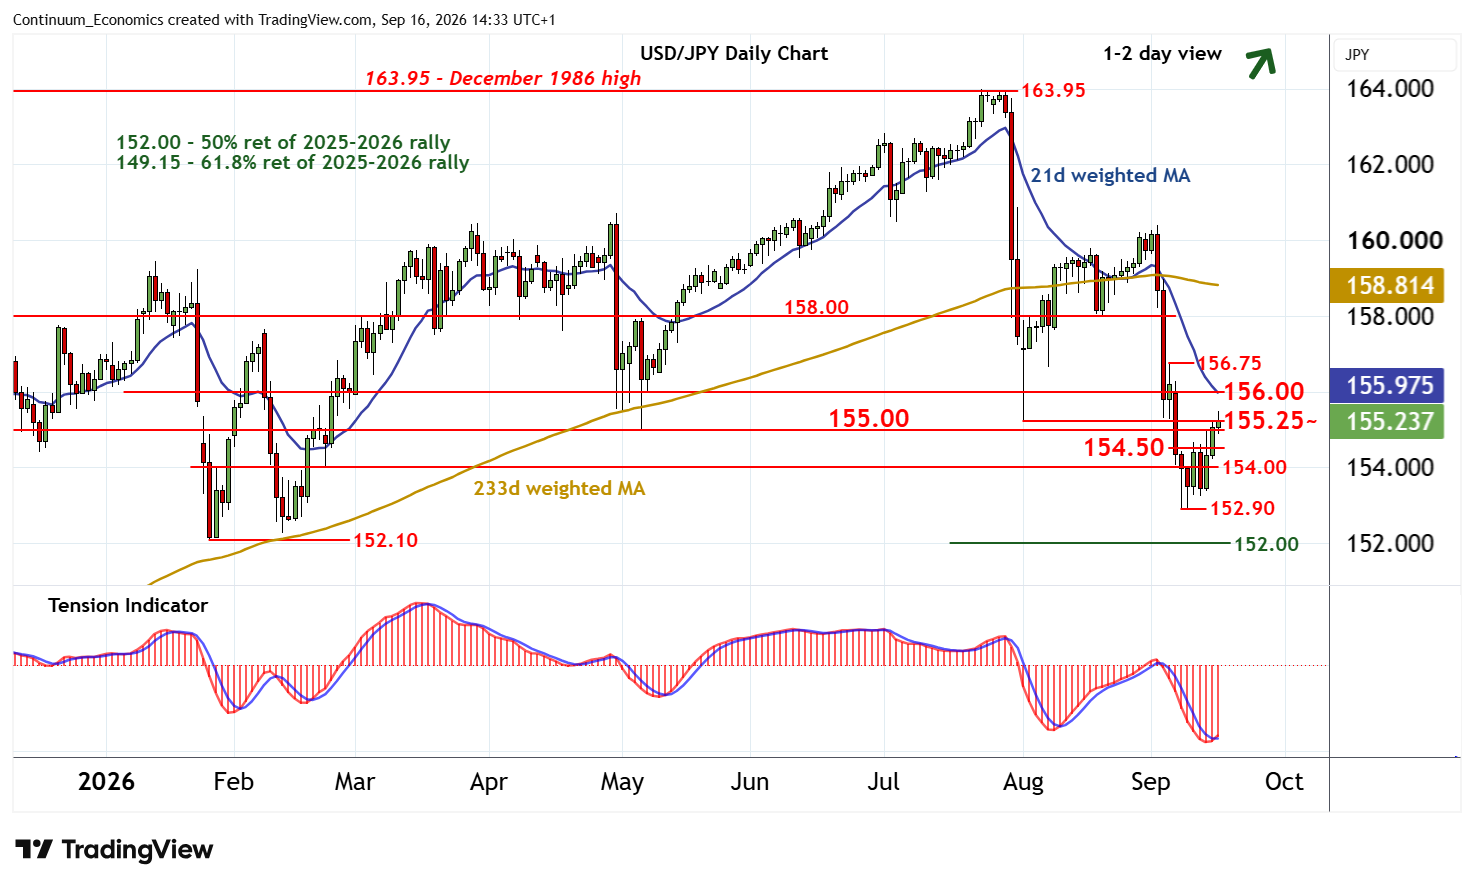
USD/JPY squeeze extends, though runs into potentially heavier supply now at 156~. Key on this pair of course is the BoJ now and it really needs to step up Friday to more explicitly validate the market too on what it has priced in near-term (the move to quarterly pace with another hike in Dec), if it is not to disappoint and not keep up with the Fed.
Action in the last couple of weeks has continued to leave the UK MPC as the comparative laggard of the pack when it comes to further tightening, and cable has therefore been particularly pressured.
A close below 1.3475, so far held, would add weight to sentiment and extend towards the 1.3425 retracement. Just lower is congestion around 1.3400.
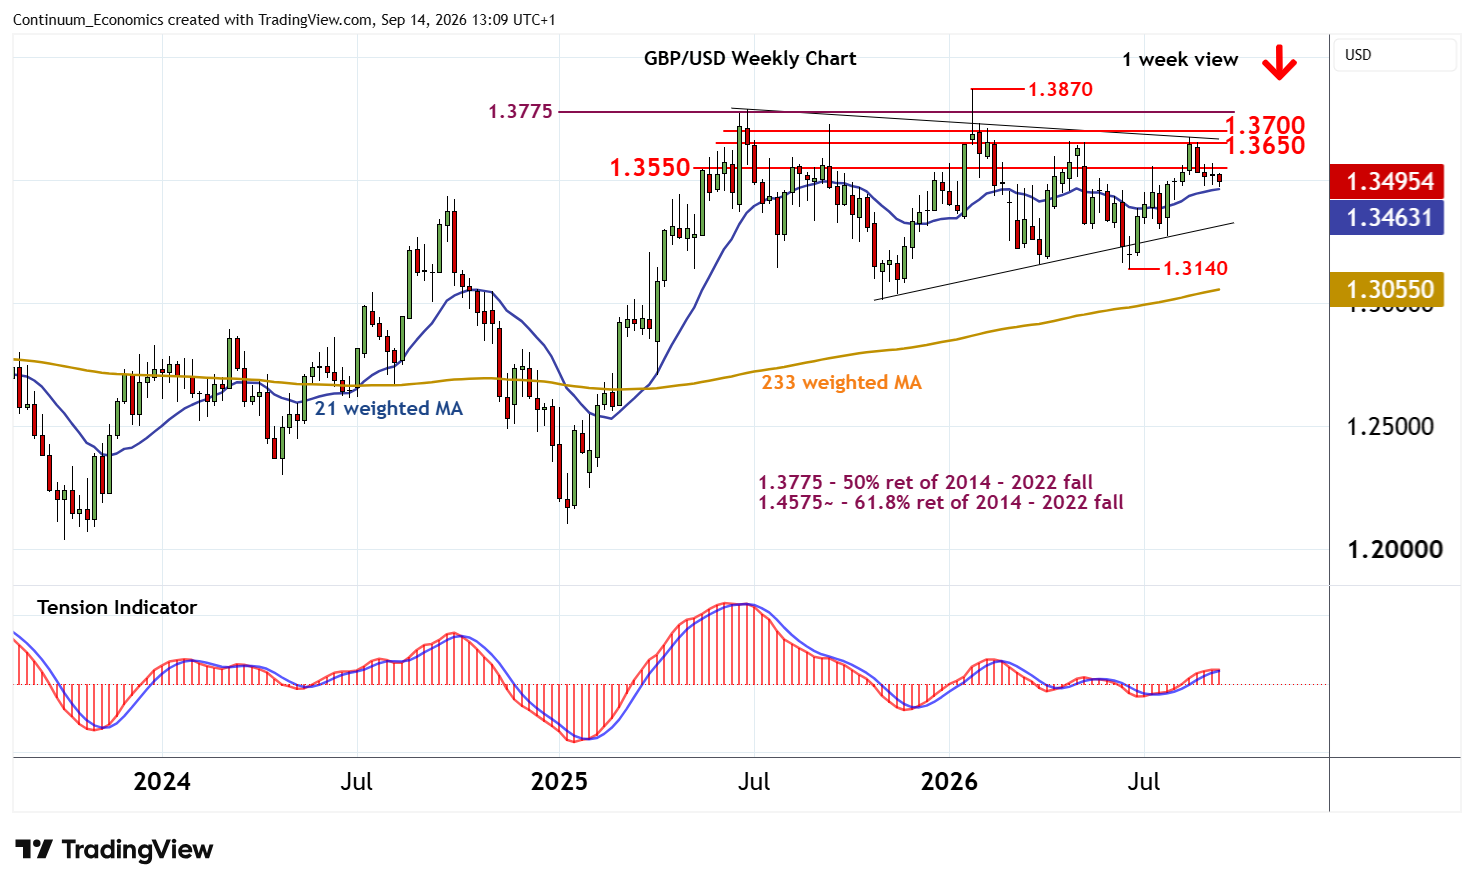
Focus shifts to the BoE next and the Bank is expected to remain on hold. The details from the vote balance and the commentary will be scrutinised closely though for any change in stance from the prevailing ‘time to wait’ approach adopted thus far on the back of lack of second round effects and the soft labour market. For the BoE, the November quarterly report month may well be more the critical D-Day in terms of whether it will stick to its guns here and continue to look through an energy driven lift toward 4% for headline inflation into early next year.
The other main interest from the BoE is the bond purchase vote, where it is widely expected the BoE will slow the pace of quantitative tightening, with press reports already suggesting that the Bank will halt selling 20yr and 30yr bonds. Rather than a reactive move, this just seems entirely sensible in light of the amount of long end tightening being delivered and of course the cost of the action. If the BoE comes across as more dovish than priced in, sterling, that has so far held in, at least other than against the dollar, could feel a bit more weight.