FX Daily Strategy: Asia Oct 13
Dollar stays bolstered into US CPI; defensive of upside risks
GBP retaining some better support, as political risk pricings rebalance
EUR/AUD still holding around key medium-term support
A relatively slow start to the week with the Japan and US (partial) holiday, albeit with the dollar generally retaining a solid lean, skewed somewhat defensively firm into the week’s key event, US CPI data on Wednesday. Build up to that is likely to keep the dollar well supported, even with various pairs somewhat overstretched and still within their consolidative zones from last week.
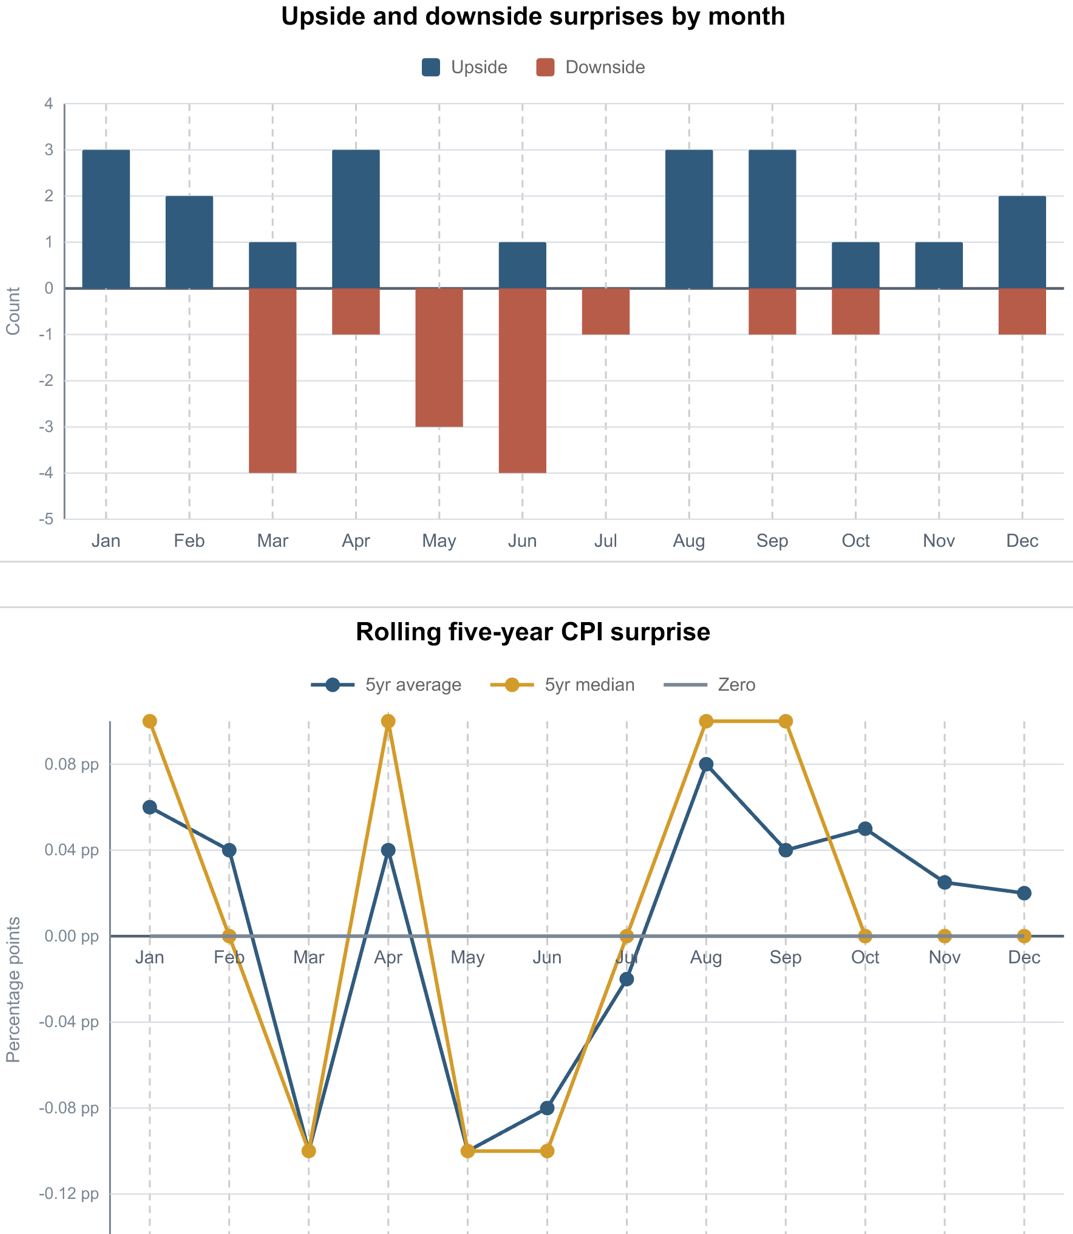
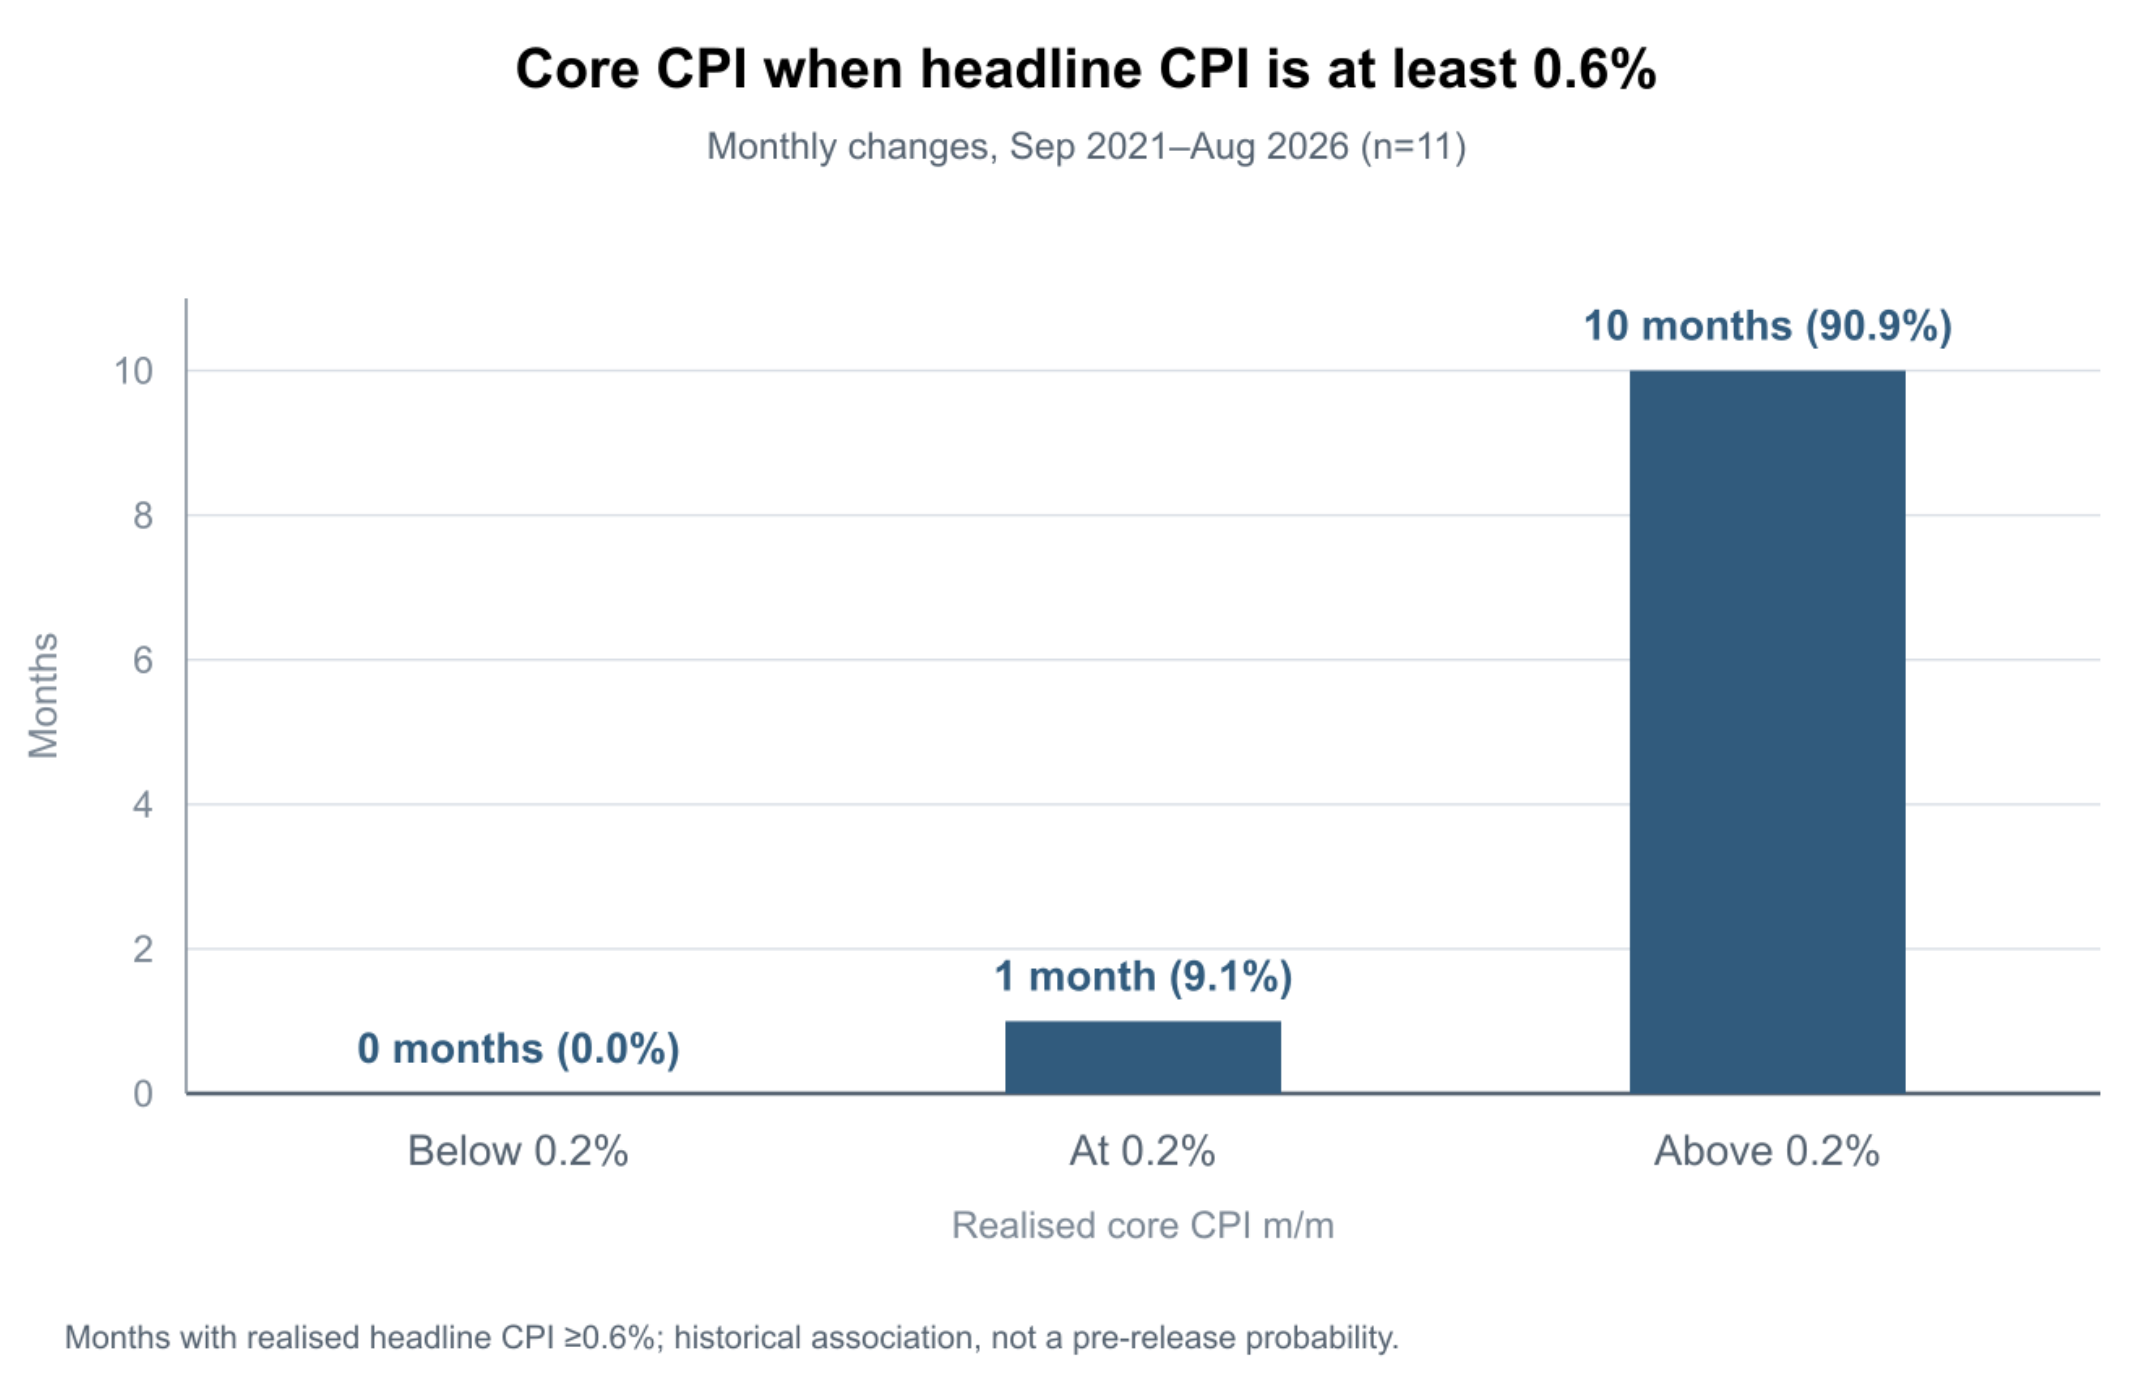
Focusing on the latter, while we do look for core US CPI to come in on market at 0.2%, as discussed elsewhere (here), there are some grounds for being somewhat on guard against the upside risks. In short, both the seasonal skew and the headline-skew both tend to play to some upside bias, in generic terms. Maybe not something to overstate, but nonetheless suggesting the market will tend to be positioning itself more for upside than downside risks. Were the number to surprise high, it would certainly ask some awkward questions at an awkward time.
In terms of the positional backdrop, IMM data highlighted that euro shorts had picked up pace and now stand at the most-short since 2020, tending to play to the consolidate slow that kicked in over recent days after the fast step-down. While that does highlight the stretched speed of the move, this is actually not that extreme big picture however, at around -1 standard deviations, with 2015 seeing positions more than double, for example. Spread and outright action has slowed since Lagarde engaged in some mild verbal nudging with the ‘tools to act on disorderly moves’ remarks, but euro bounces are remaining capped. It’s worth keeping in mind however that the more likely nearby influence is for the bond pressure to act as an inhibiting factor for ECB tightening and thus, from relative policy angle, to keep that alternative euro-negative aspect in play.
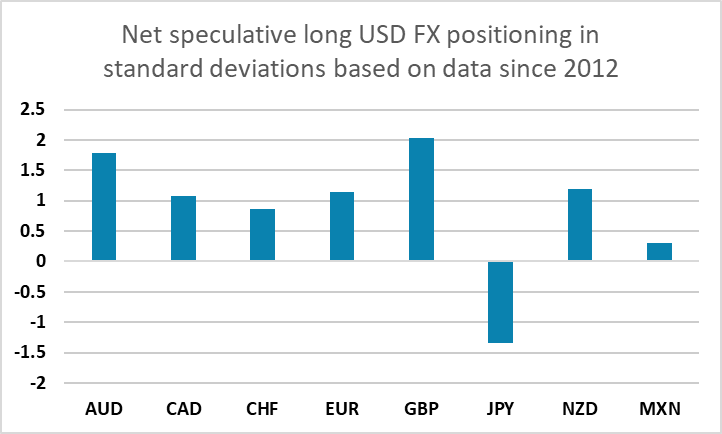
Among the pack, sterling looks like it is doing its best to try and find a base versus the dollar and pushing towards outperformance on the crosses. Not only does it remain over-short (the most in fact compared to other majors), but continues to look over-discounted for political risk, relative to other majors after a period in which UK politics and budgeting was dominating the focus.
EUR/GBP has already managed a good reversal run and moving into firmer support areas, but potentially has more room to run yet nearby - a close below 0.8447 will add weight to sentiment and extend broad November 2025 losses towards congestion around 0.8400 and 0.8403, (GBP/EUR 1.1900). The continued positive overtures towards potential Bre-entry, while a very long-term play out and with many political obstacles in the way, is also tending to offer sterling some psychological support too.
AUD was also noted abruptly shorted into last week and this too might continue to play positionally to the grind in EUR/AUD, at least until and unless wider volatility and risk off sentiment picks up (we continue to watch US election risks in that respect). EUR/AUD has major monthly support at 1.6~ (and 1.5845 below) and this zone remains critical support in terms of any range fade or stop-in to longer-term extensions.
On the calendars, Tuesday is another slow one, seeing NAB confidence data from Australia and final inflation prints from France and Germany.
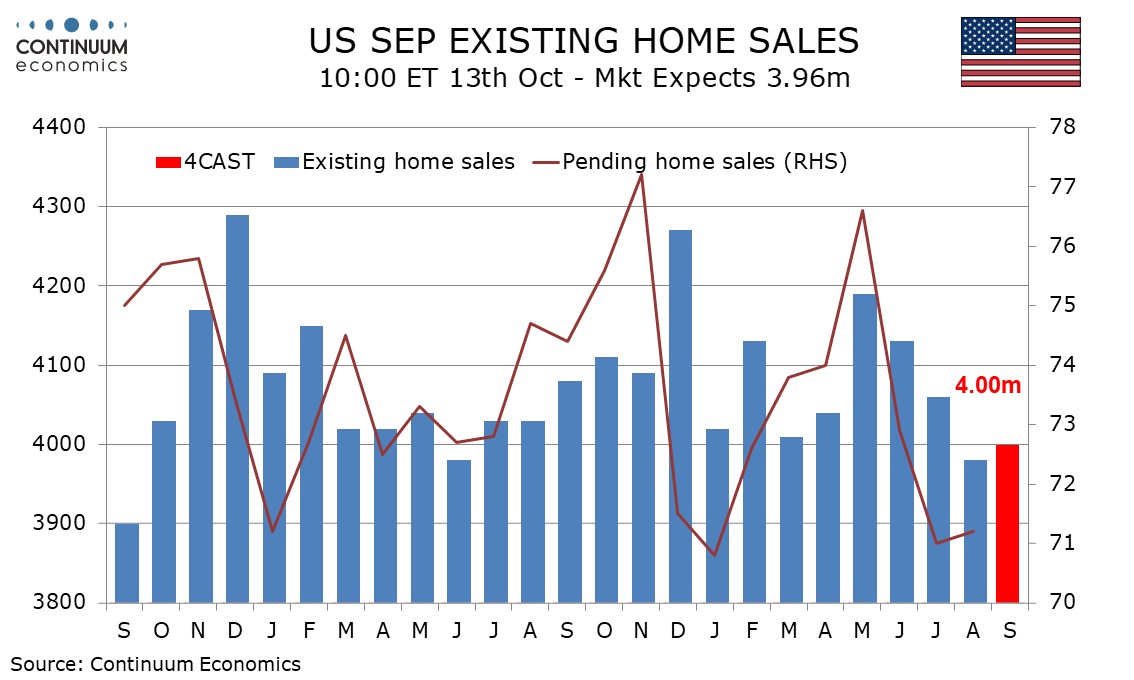
In the US, we expect a marginal upwards correction of 0.5% in September existing home sales to 4.00m. September’s NFIB small business survey is also due, while Fed’s Collins will speak.