US Sep CPI in focus – upside risks persist?
While we look for a consensus 0.2% core CPI, background trends do suggest some risks
Both seasonals and high headline CPI months bring some generic upside skews
Along with French/euro developments, CPI prints are the major focus for the week, dollar defensively supported prior
In an otherwise fairly quiet one, US CPI is the key focus this week, at least on the dollar side of the equation. The big question prior then is whether there are any reasons to see upside risks to the 0.2% core consensus. In very general terms, you could argue that there could be.
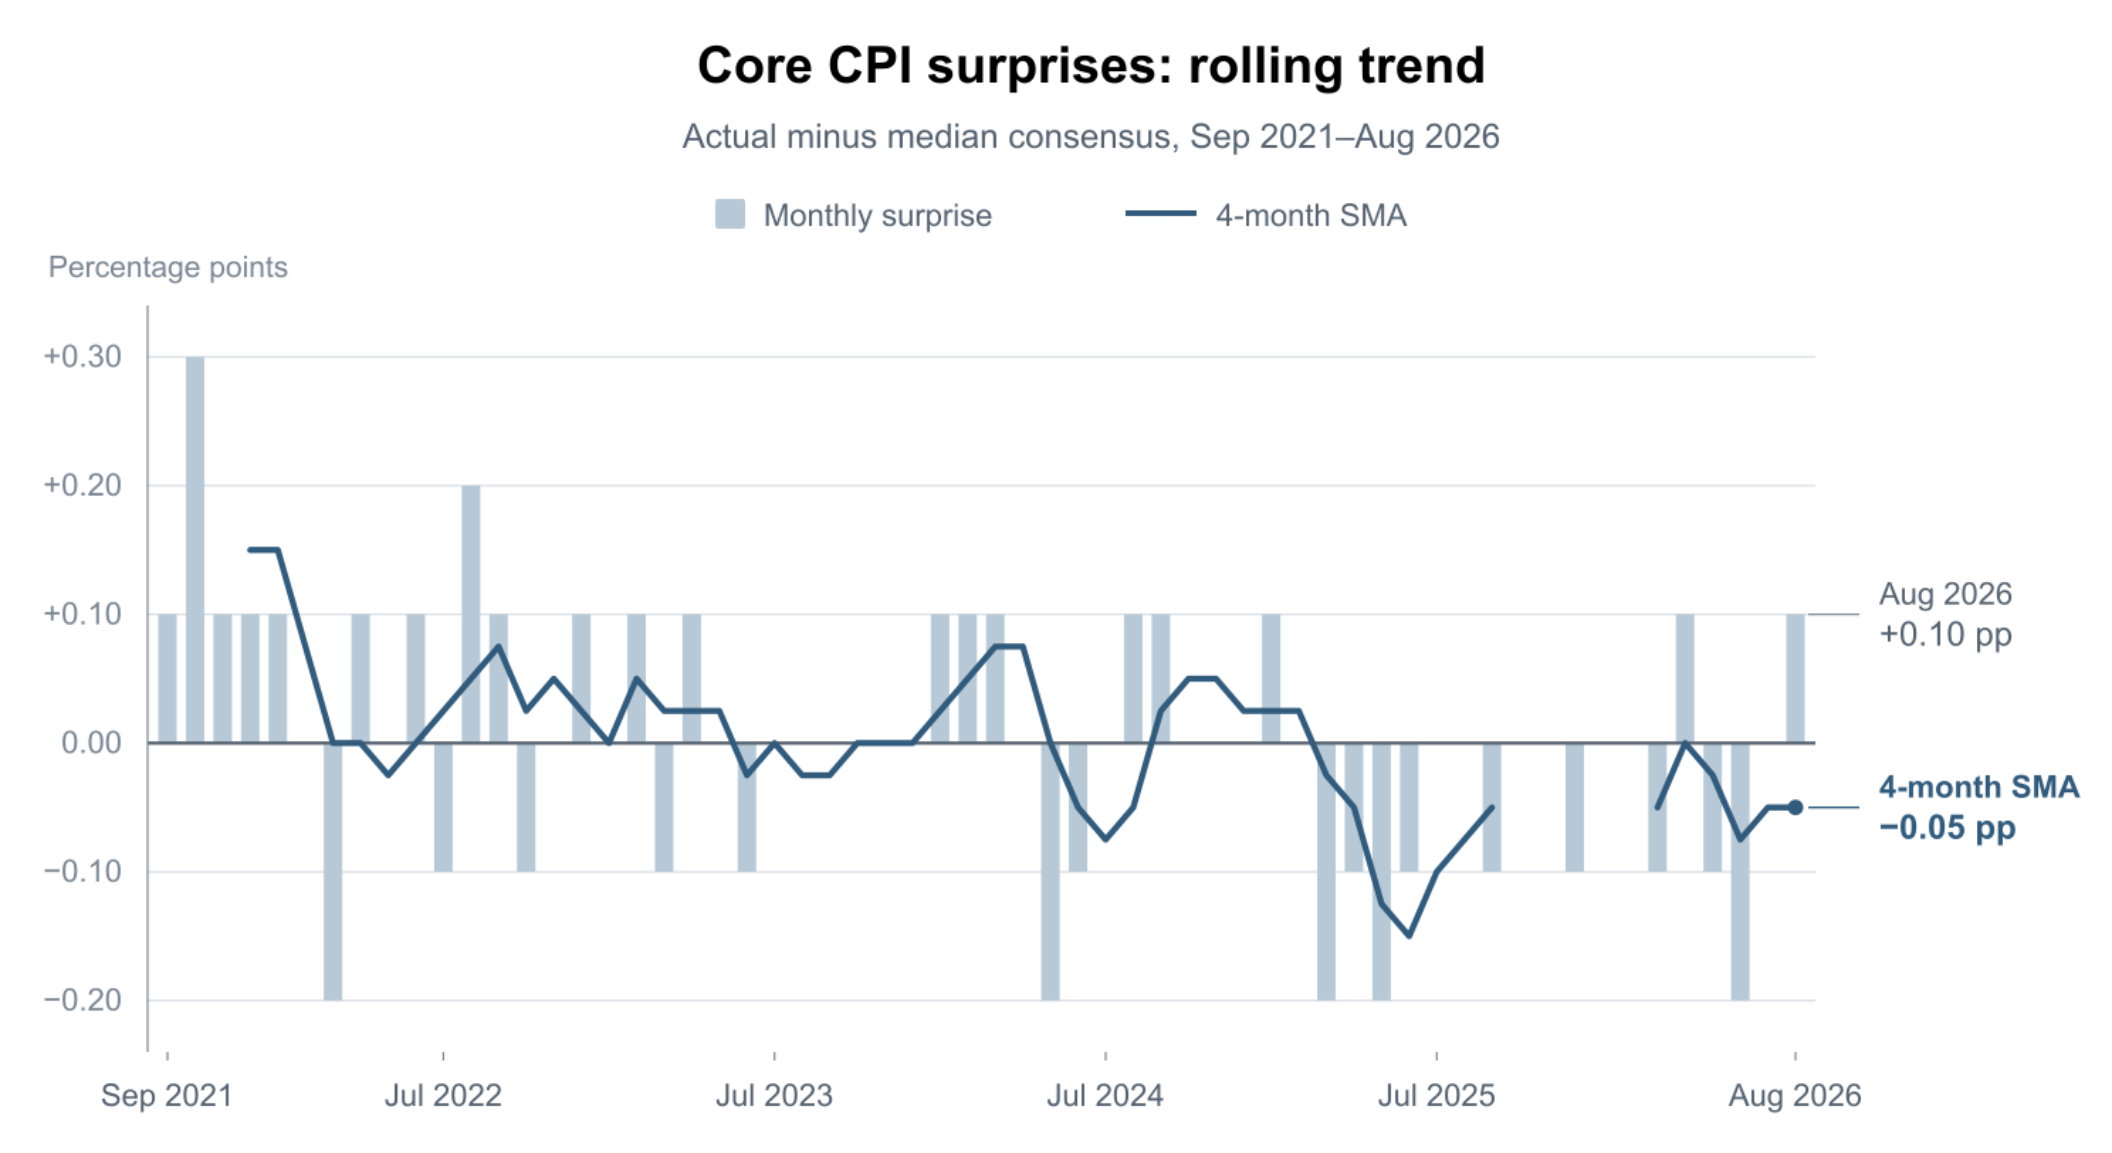
Looking at the recent trend, after early year acceleration was not maintained, the market then ‘over-adjusted’ to upside surprises and in fact the subsequent trend moved to the downside. On the back of that, the consensus is now more conservative, reflected in the trend-like 0.2% market assumption going into the release. That, mechanically at least, does increase the risk of unexpected firmness.
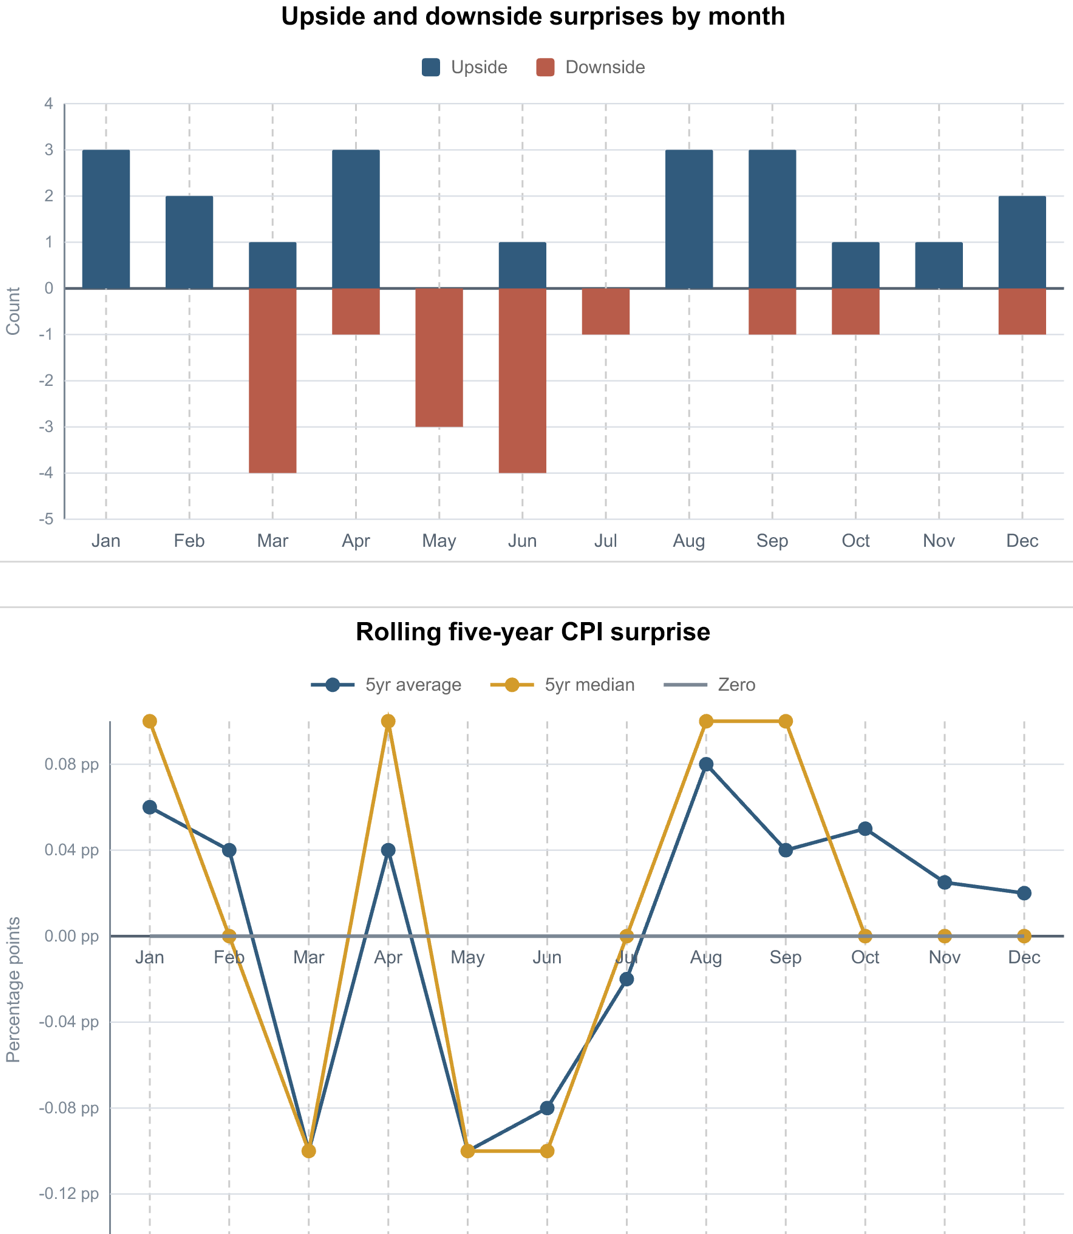
Looking at the seasonal trend, while perhaps not as distinct as January in particular, the upside surprise skew that was in play in August remains in play in Sep, albeit not unequivocally. Such patterns should not be overplayed, and residual seasonal quirks themselves will be adaptive, but recent data has continued to conform to a generic pattern of downside skew in early summer and then upside in late summer and early autumn, which was reflected in the August upside surprise.
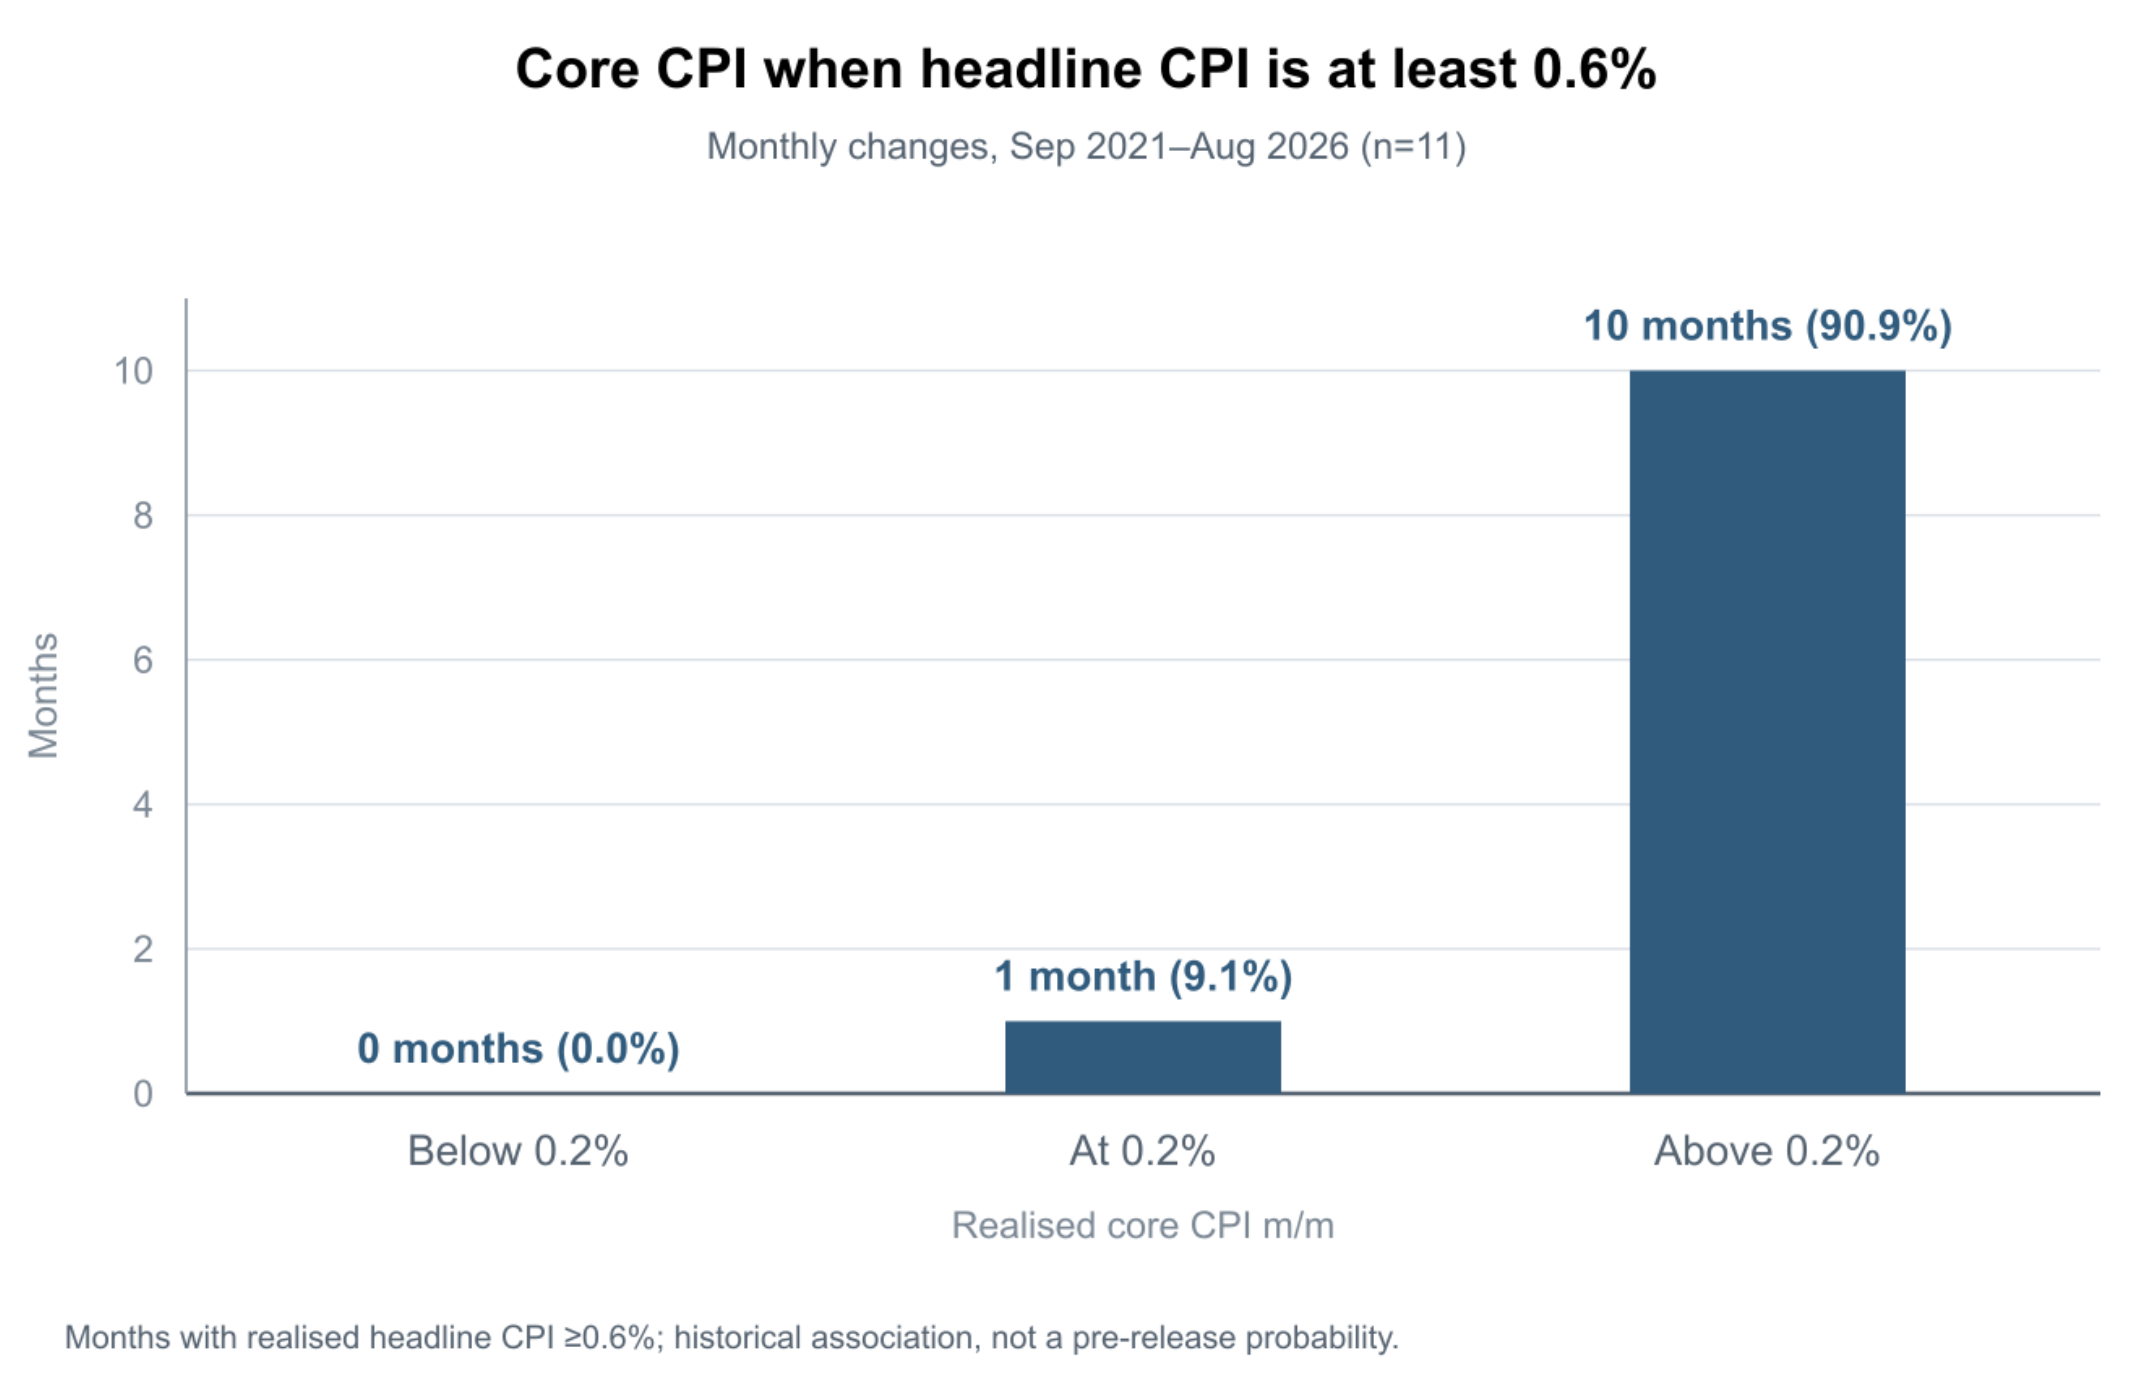
There is also some risk of ‘headline contagion’ too, it could be argued. The market is looking for a headline print of 0.6%, and in recent years, such months have been heavily skewed towards probabilities of core exceeding, rather than undershooting, a 0.2% baseline. Now that ≥0.6% result is also heavily influenced by 2021–22 inflation surge period. After 2022, only two months had realised headline CPI of at least 0.6% - one produced core of at least 0.3%, and one produced an upside core surprise. So again, perhaps not to be overplayed on a skewed (and post fact) sample, but a factor to keep in mind.
Our forecast for Sep core is actually a consensus 0.2% (and a tame 0.2% unrounded), with August in fact heavily influenced by a one-off in the telecom component that is not expected to be extended. Still, in terms of risk positioning, were some generalised patterns of recent years to persist, there might be some grounds for being defensive on the upside. An upside would certainly raise some interesting questions...