U.S. September S&P PMIs - Sharp gains in Manufacturing and Services back improved Q3 GDP signals
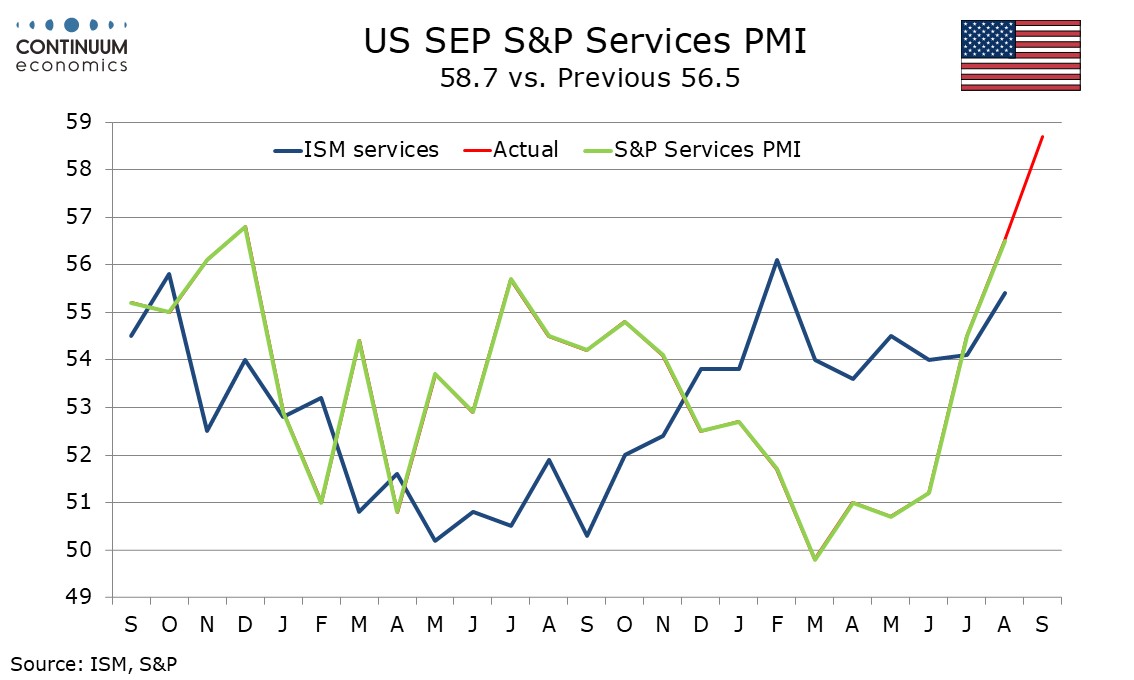
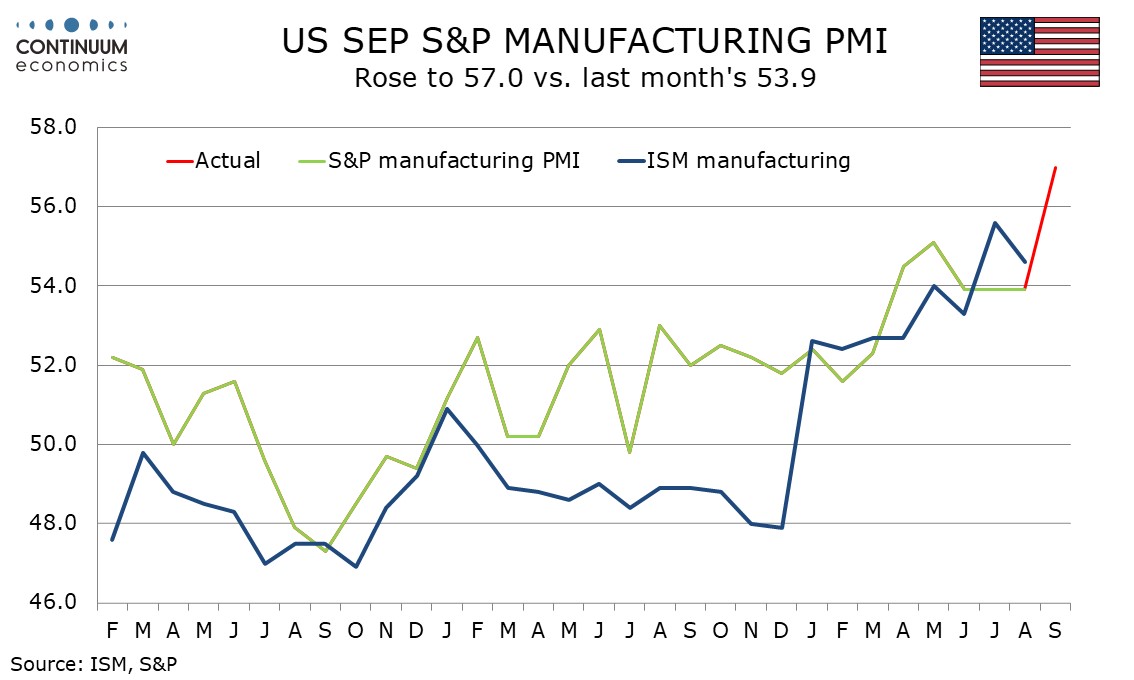
September’s preliminary S and P PMIs are startlingly strong, manufacturing at 57.0 from 53.9 and services at 58.7 from 56.5. The composite increased to 58.4 from 56.0. The numbers are consistent with a Fed view that the economy has strengthened recently, with recent data also suggesting that Q3 GDP will deliver a strong quarter.
The manufacturing index is the strongest since May 2022 and marks a reacceleration after a pause in the last three months. Manufacturing surveys are mostly positive but have been mixed with the September Philly Fed manufacturing index still strong if less so and the Richmond Fed’s turning negative. August manufacturing output saw a surprise fall. We doubt September’s ISM manufacturing index will rise as strongly as the S and P’s but August’s dip in manufacturing output is unlikely to be repeated.
The services index is the strongest since October 2021 and has accelerated significantly in each month of Q3 after hovering close to neutral in the first half of the year. This is consistent with GDP signals but difficult to explain with consumer sentiment and real disposable income restrained by elevated inflation. The S and P services index is not well correlated with the ISM’s, which has had a steadier profile at a moderately positive pace through the year to date, though August’s 55.4 reading was on the firm side of the range. Again, the ISM services index is unlikely to look as strong as its S and P counterpart, but the S and P data is too strong to be ignored.