FX Daily Strategy: N America, Oct 20
France remains in focus, even if positioning and expiries help to cushion
USD long positioning was back to the extremes pre-CPI-reaction; euro crosses still struggle
A political winter of discontent asks FX questions of who comes out on top - CHF? JPY?
While relent from positioning extreme, particularly on the USD and US bond side, continue to offer some prop on EUR/USD (as do expiries early week in the 1.1265-1.13/15 zone) - and indeed keep alive general dollar squeeze risks - the euro more generally remained weighed to start the week against the backdrop of disorder at the weekend.
France remains the centre of that after the mass protests and in places violent disorder, though there were pockets of wider spillover in Italy and Portugal too, suggesting some need to guard against ‘reverse contagion’ from semi-core to periphery too.
Against this backdrop, real fiscal consolidation remains all but impossible (Macron was forced into billion-euro concessions in fact after the last Yellow Vest protests) and that continues to exert medium-term pressure, even if intra-euro spread widening so far remains within the bounds of the last couple of weeks to date.
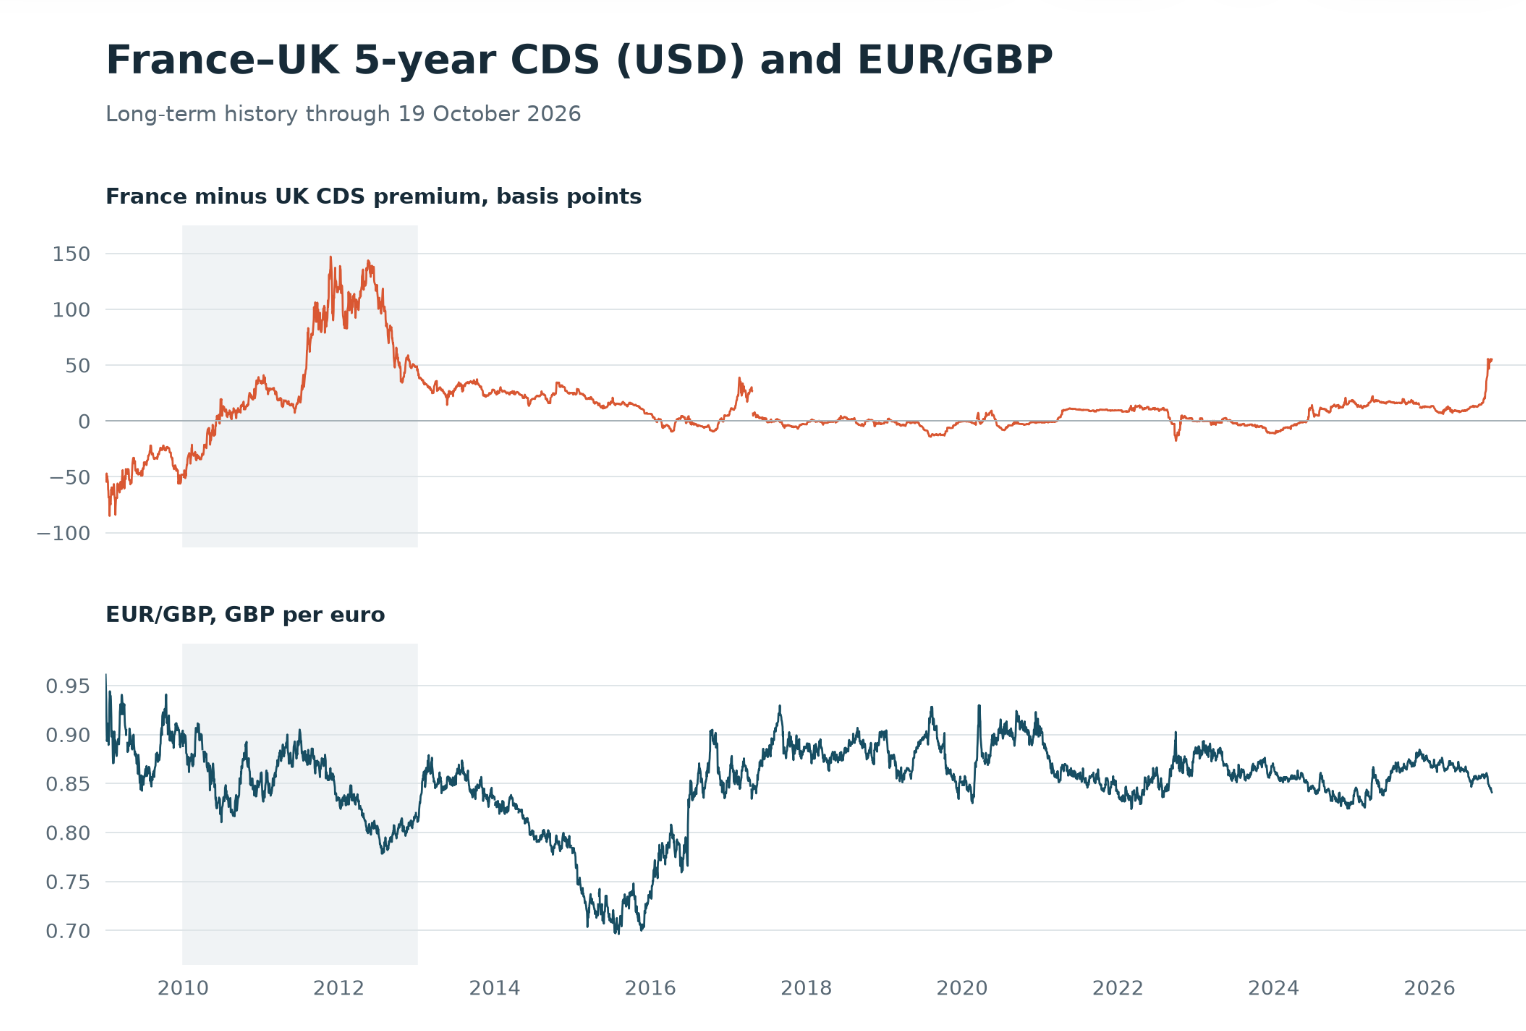
Moody’s next France rating evaluation is on Friday 23rd and although current spreads already imply a downgrade is more than priced in, psychologically a negative assessment could also add to the sentiment pressure on the FX side.
Wider spillover also comes through the monetary transition channel with ECB’s Lagarde at the IMF at the weekend already suggesting the bond pressure has a downward impact on forecasts versus Sep. So while the ECB will not directly intervene there can be secondary impact through the ECB rates outlook. 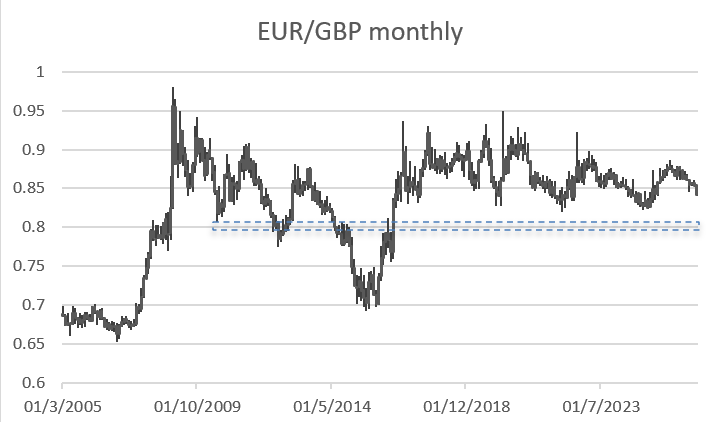
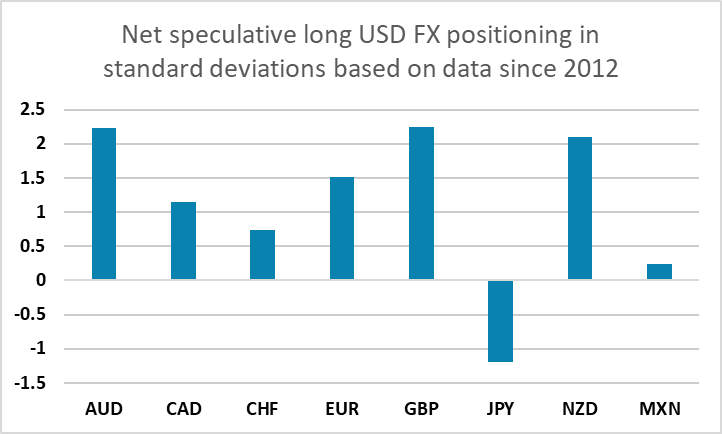
Positioning is a challenge for outright shorts at present. But shorts vs the dollar are as large, or larger, for a number of counters, cable especially, so that does not prevent potential for bigger picture euro (choppy) underperform on the crosses even in the squeeze scenario. EUR/GBP is finding support into 0.84~ and is somewhat oversold on the near-term charts. The longer-term pull could still be into the multi-year base (below recent 0.83~ is the zone either side of 0.8).
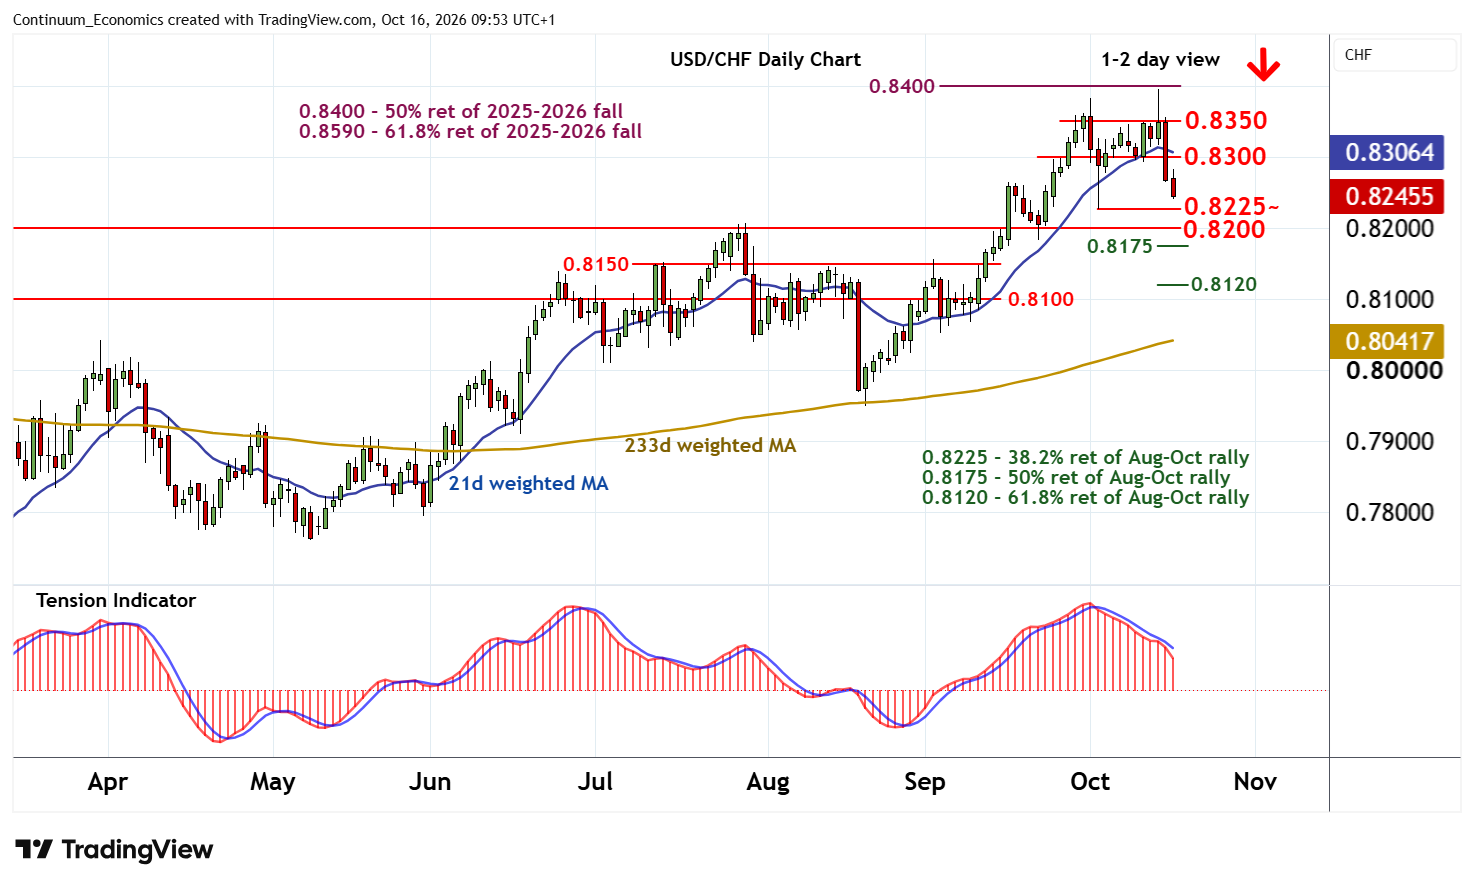
If discontent and political eruptions become a lasting factor in coming weeks and into a winter of discontent, then relatively protected Switzerland starts to come further back into its own, superseding its stand-out carry appeal enjoyed in the breezier summer months. EUR/CHF remains in significant retracement mode. US politics, centred around the midterms, remains a wildcard and in some circumstances CHF political/fiscal/social considerations could become more prominent still in the FX market’s weighting matrix.
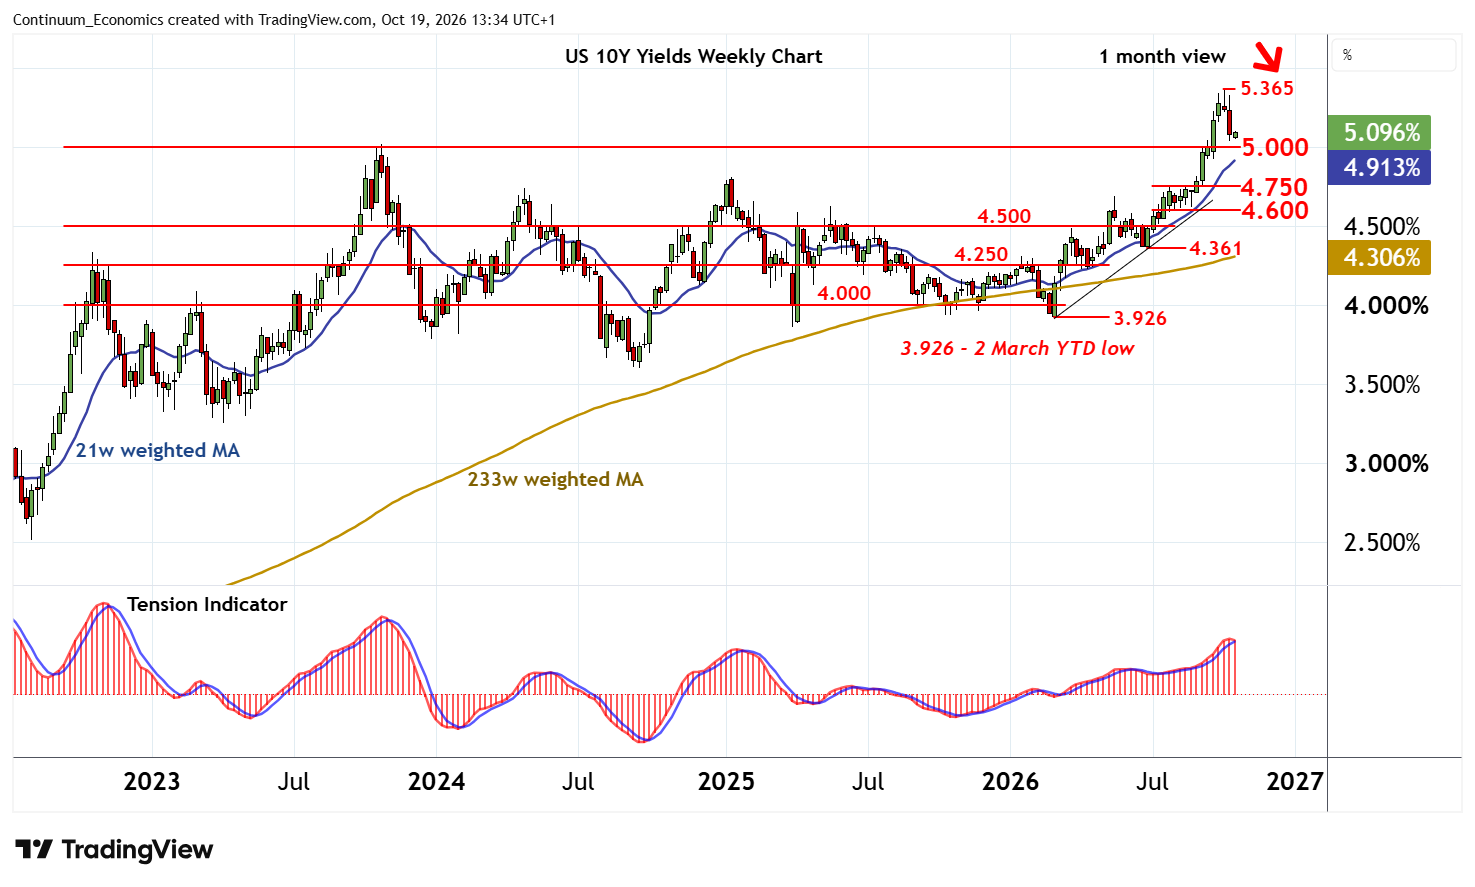
Yen also fits into that camp and continues to show signs of strong, persistent background dip buying interest into weakness, with progressive capping into the 158-9 to 160 area. USD/JPY may therefore remain top heavy with room to extend lower if the US bond yield correction extends in coming week.
Turning to Tuesday, UK labour market data was the main early calendar interest and generally shows some improvement, coming in on the firmer side of expectations with earnings ex-bonus up to 3.7% (mkt 3.6%) and HMRC payrolls up 13k in Sep, with Aug notably revised also to +1k from the prelim -26k. Aug ILO unemployment also down to 4.7% from 4.9%, with the Sep claimant count (+30k) the only exception to the better prints. Data goes with the grain of Nov hike expectations and also with the grain of the cable lift from its recent oversold selloff, with GBP also showing extreme short positioning. Break above 1.3370 bounce high still needed to extend the rally.
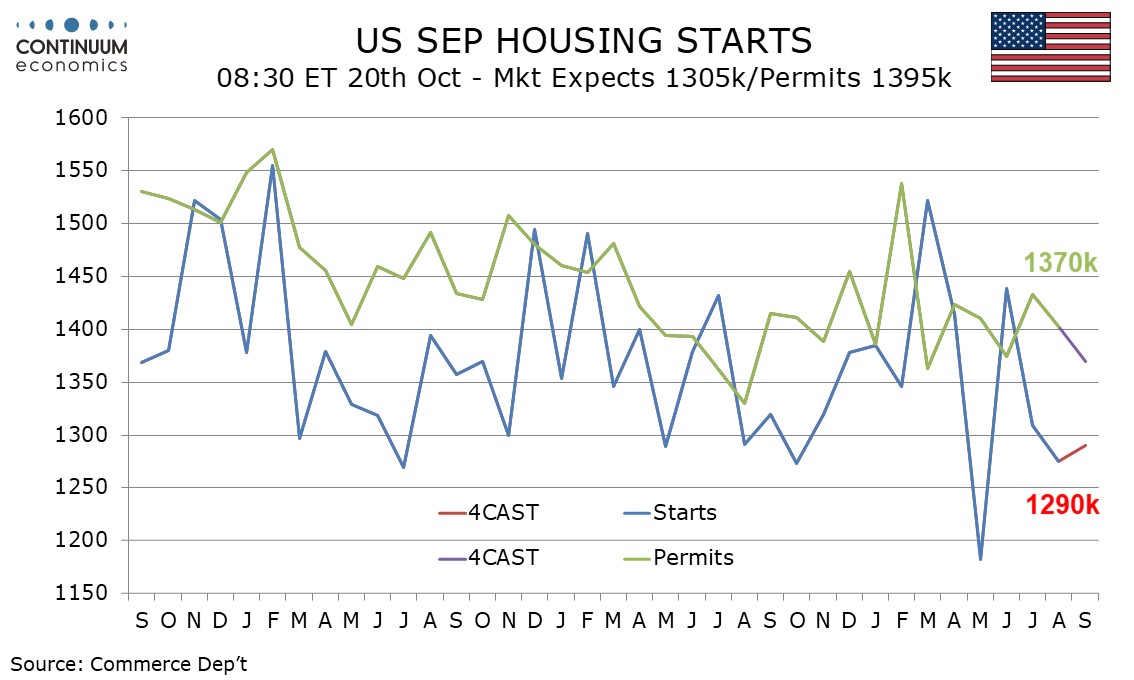
In the US, we expect September housing starts to rise by 1.2% to 1290k but permits to fall by 2.6% to 1370k.
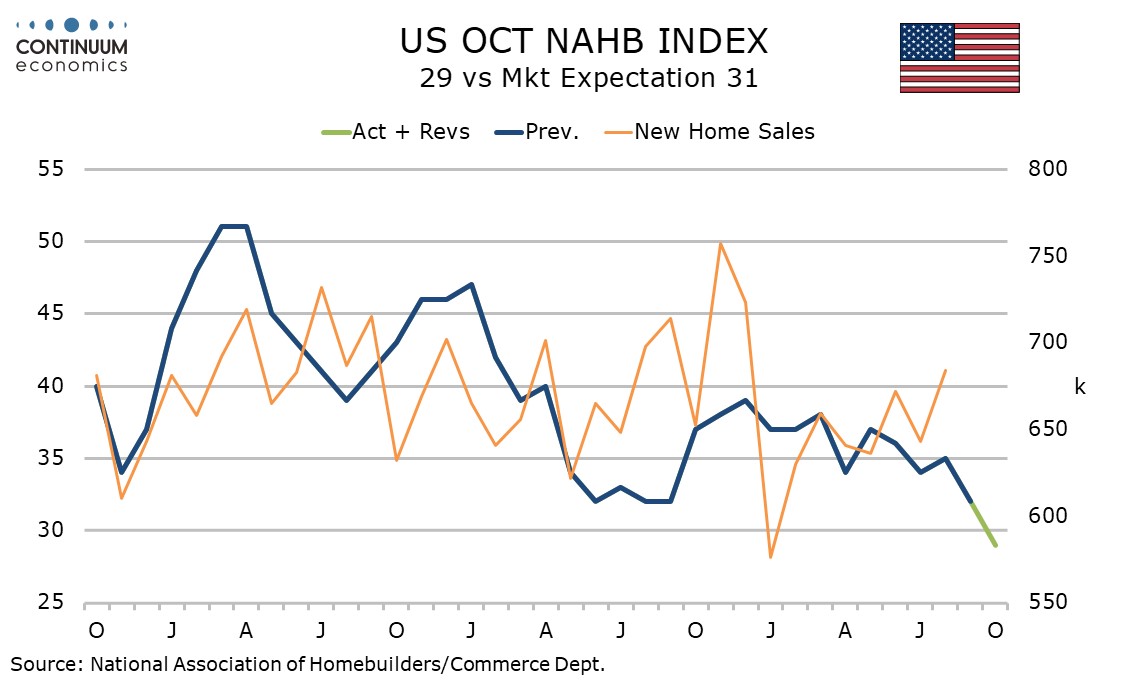
US NAHB data, dropping to 2012 lows, highlights how recent yield surges and impact on morgage rates have impacted demand in the sector. Signs of that negative feedback and AI-crowding out has been helping to draw buyers into the oversold US bond market and stem the overbought dollar charge.