Published: 2026-10-19T08:13:56.000Z
IMM Commitment of Traders Reports - $ longs were back to the extremes, prior to trimming
2
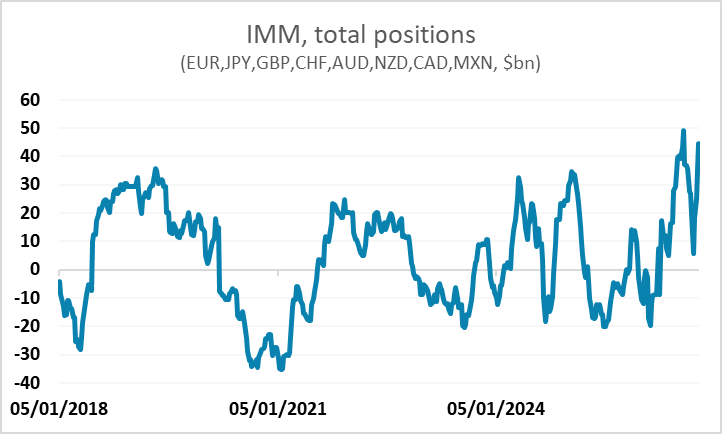
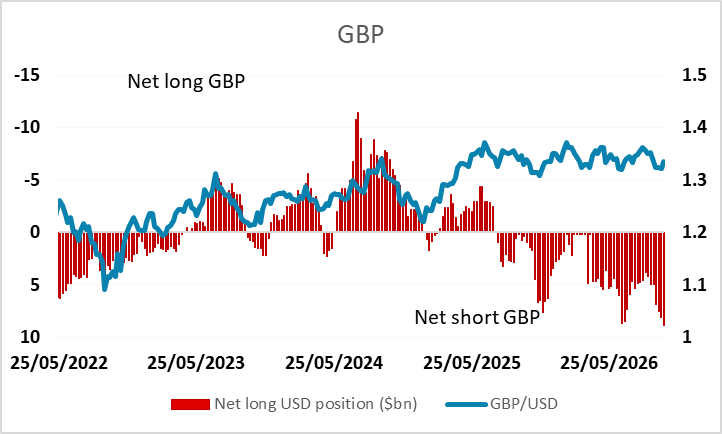
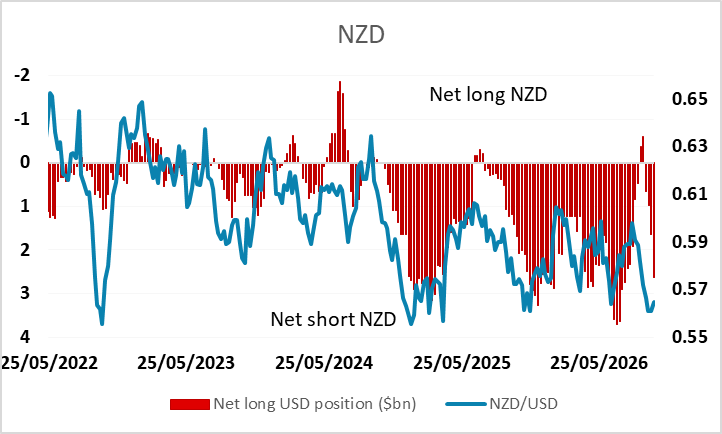
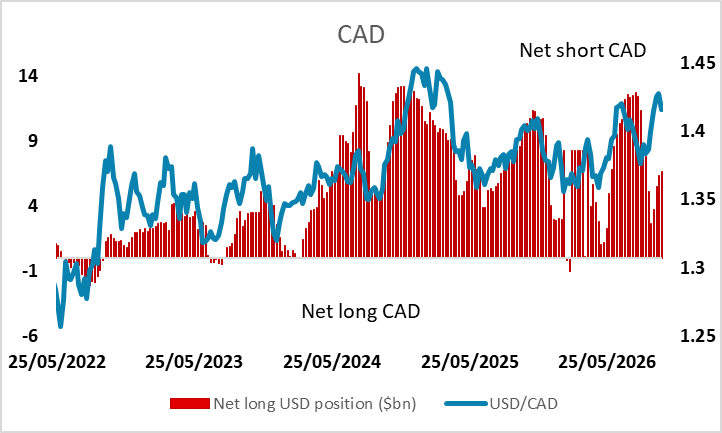
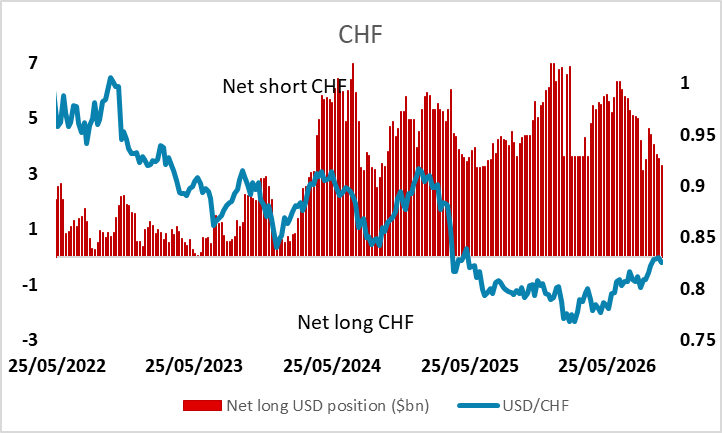
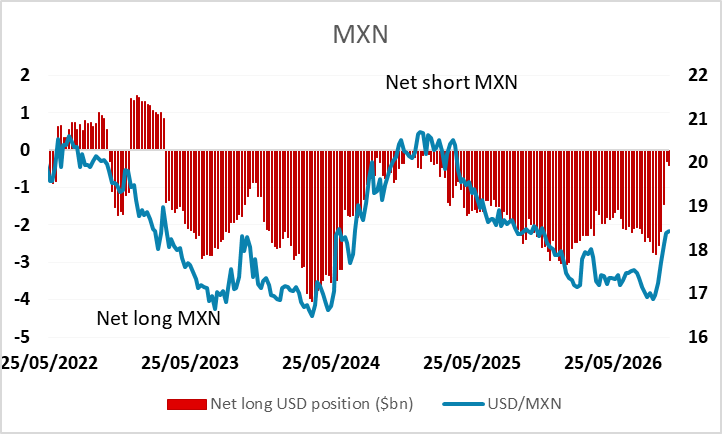
IMM data underscores that aggregate $ longs were back to near June extreme before profit-taking pullback kicked in
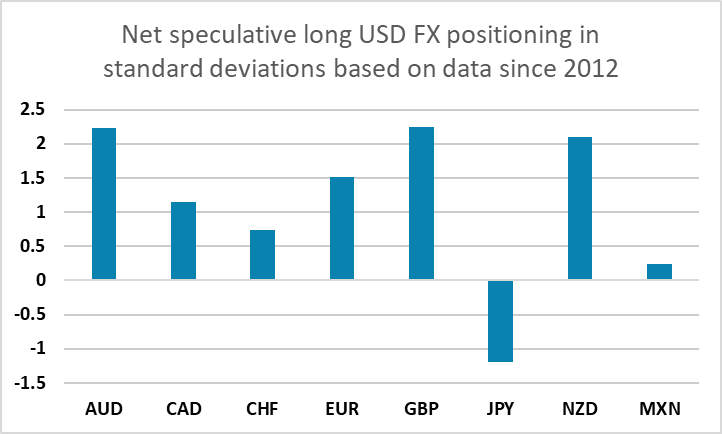
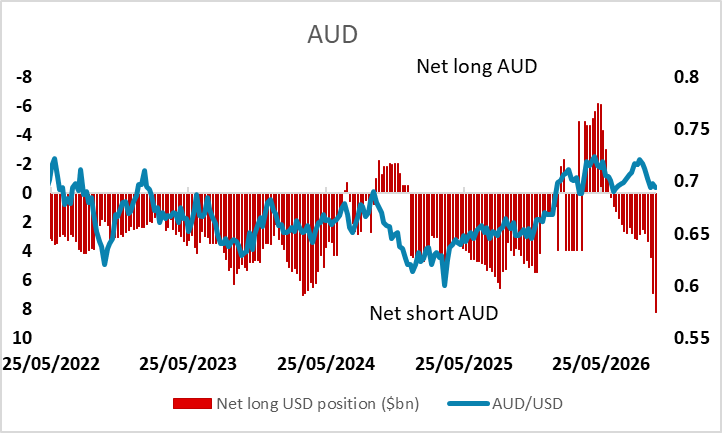
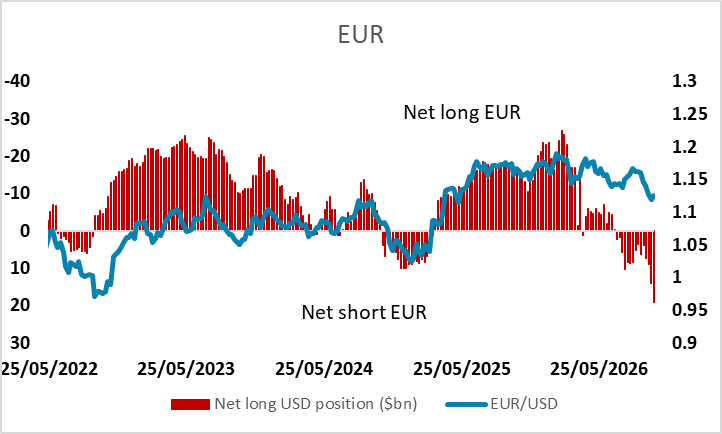
AUD, NZD, GBP were all a 2stdev+, euro a little less at 1.5 if still most since 2015
So positioning $-centric, not particularly euro (France) skewed
$-wide positioning reflected in the post CPI price action and still the n/t positional overhang
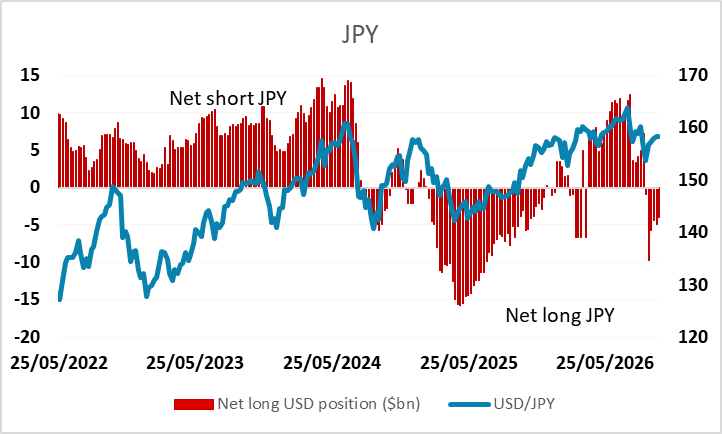
JPY remains the biggest exception as it retains its sentiment shift