FX Daily Strategy: Europe, Nov 3
Oil back in focus and with it NOK's exposure to positive scenarios that are less hedged; news remains chequered
RBA delivers hike and may be done now, market pricing in a flat outlook
US still waiting for midterms then payrolls
While Belgium is vying with France for attention in the Eurozone bloc, and tech still waiting to see if the early week bounce is a dead cat one to re-test the break or another spike move, oil very much forcing its way back into the centre of cross-market action.
This comes against a backdrop where IMM data once again underscored how overall long the market remains overall long of dollars, especially on the antipodean pairs, with AUD extending the all-time extremes.
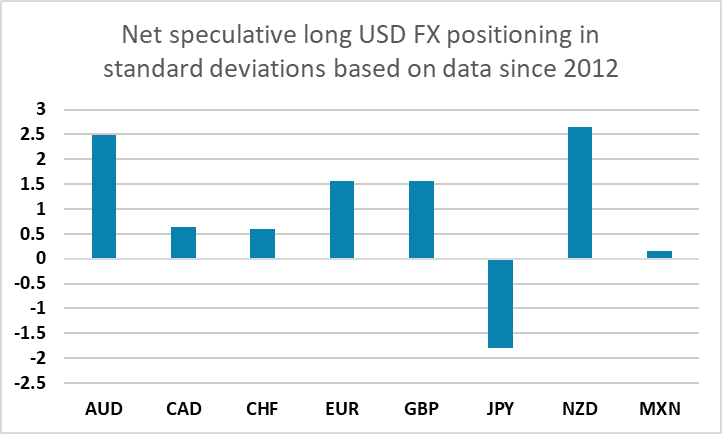
Other pairs also attempting still to trace out near-term bases and bounces, though the likes of EUR/USD still struggling to gain huge traction, let alone move into squeeze territory - especially while equity and technical chart picture looks soft near-term.
The backdrop to the oil action picks up on the threads discussed in recent outlooks, both the broader framing of US and Israel domestic politics around elections, and the recent stance-shift signalled some days back by the reported letter sent by VD Vance. Without overreading into the media feeds, there does seem to be at least some shift towards positive instigation on the US side, in place of the prior hawkish positioning and preparation for post midterm strikes.
The market has heard and seen many variations of the current mediated talks and floated Strait opening proposals many times over of course but the current version seems to have a little more intent to it and perhaps more importantly hitting a market more heavily positioned away from incorporating positive scenarios into its risk-adjusted pricing.
All that said, the latest if low key "defensive" strikes on Qeshm Island overnight have checked market optimism for now, oil bouncing $2 and after holding the 21st lows. Action seen as reactive to surface-to-air missile launches and to avoid trouble on eve of midterms perhaps, rather than escalation and indeed Trump also making comments Monday rowing back on post-election resumption threats. A reminder nonetheless that any positive scenario is just a positive scenario, given recent history.
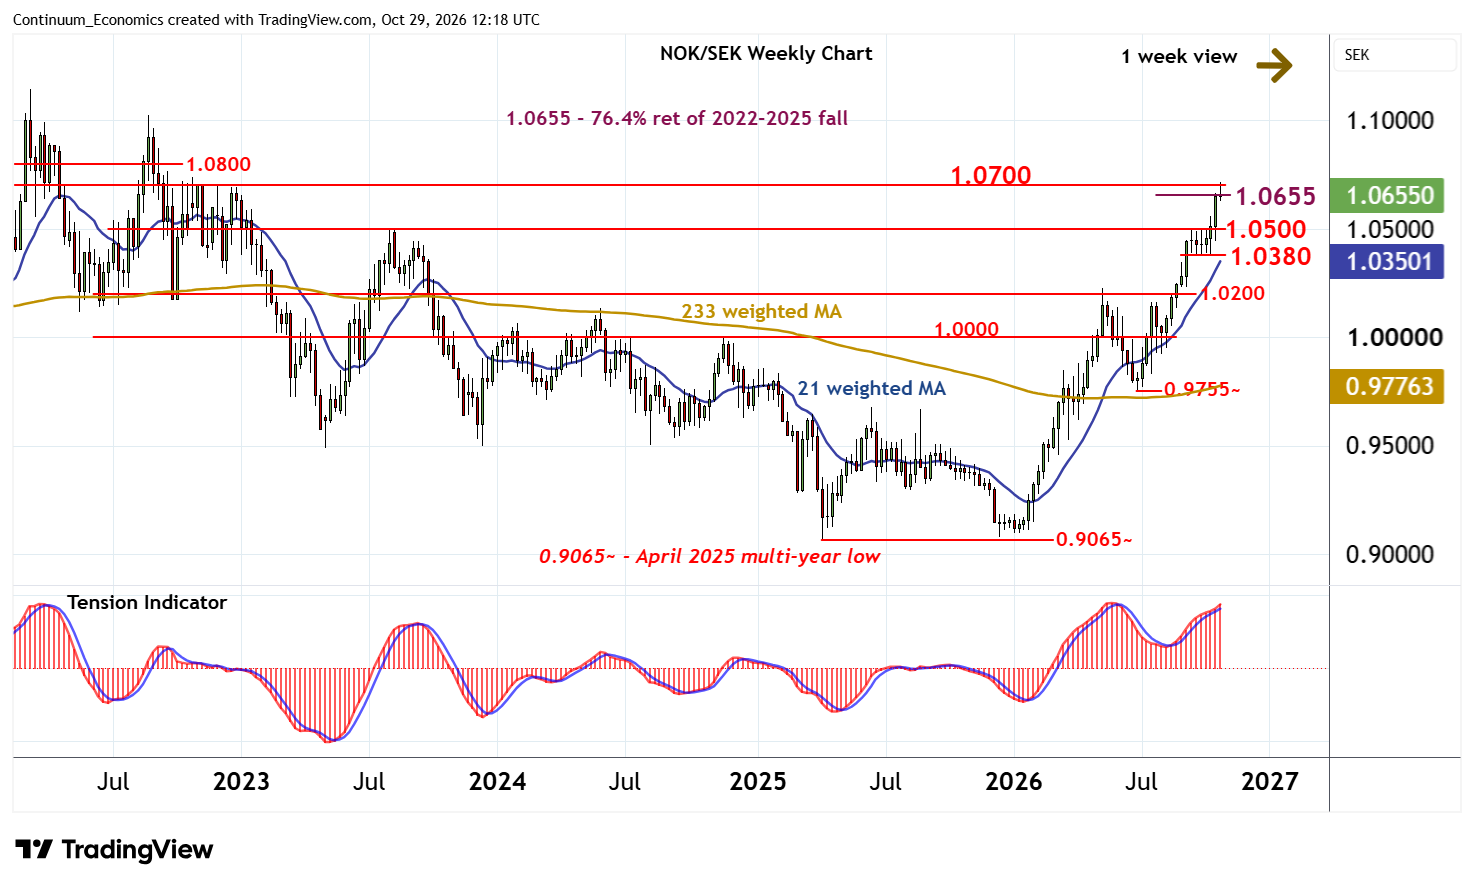
NOK of course remains the counter most exposed to such a positive scenario surprise here, or even the reintroduced possibility of such a positive surprise. EUR/NOK breaks its ultra-consistent trend-down action of the last month, and around 10.5~ would be a round figure and about 38% back of the last leg (also 23% of the bigger leg down). NOK/SEK also highly responsive especially if oil can retreat further and influence risk sentiment with it – prior recently cleared tops of 1.04-480 are the first very close pullback support and back sharply through there does then look more toppy still. Risksbank and Norges bank meeting also feed into this but to an extent secondary to the oil led driver.
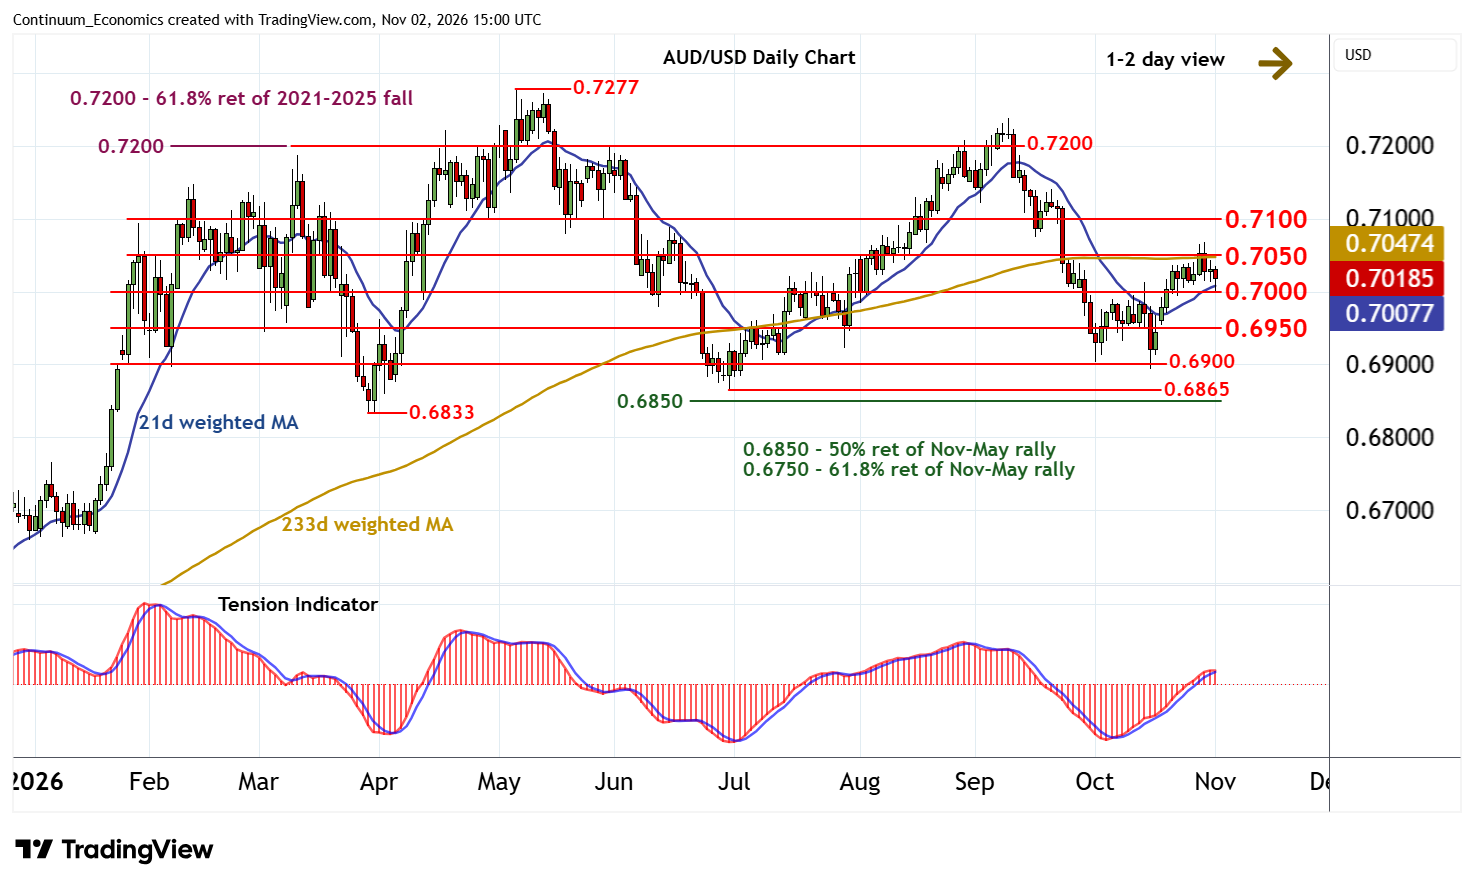
Turning to Tuesday, RBA was the main event, though the hike had largely been fully priced in and overall the result was seen on the dovish-hike or at least neutral-hike side rather than hawkish hike end. The vote was split 6-3, with the 3 favouring no change, while the statement dropped any references to further increases instead saying it would 'do what it considers necessary to bring inflation sustainably back to target'. Bullard also added it was time to pause and assess, while it was unclear what the next rate move would be.
All this fits with the notion that the RBA is reaching the limit of what it needs or wants to do, in an environment where domestic conditions especilly employment are already facing pressures. Markets nudge further towards pricing in a flat outlook from here, with only a slight hedge towards on last hike that could be largely covered by premia. AUD edged off a fraction but this does come against a backdrop where the market is already in places positioned net short, even after some 'buy the fact' recovery post CPI.
Not a huge amount on early in the European day. French budget figures would ordinary be a complete ignore, but might currently be viewed as more topical.
Otherwise, Swiss CPI data is seen nudging up to 1.3% from 1%, but still very much the outlier in terms of being low and sub target. Broader risk and carry much more critical for CHF performance, in the context of its ongoing low inflation, low rates standout feature.
US focus remains on the midterms and on payrolls, with JOLTS data today in the buildup.