FX Daily Strategy: N America, Nov 17
Dollar still edging it in uptrend - if with tech and JPY caution, and approaching various big pair levels
Earnings, IPO to feed into tech sentiment
UK labour market data and US retail sales the calendar interest
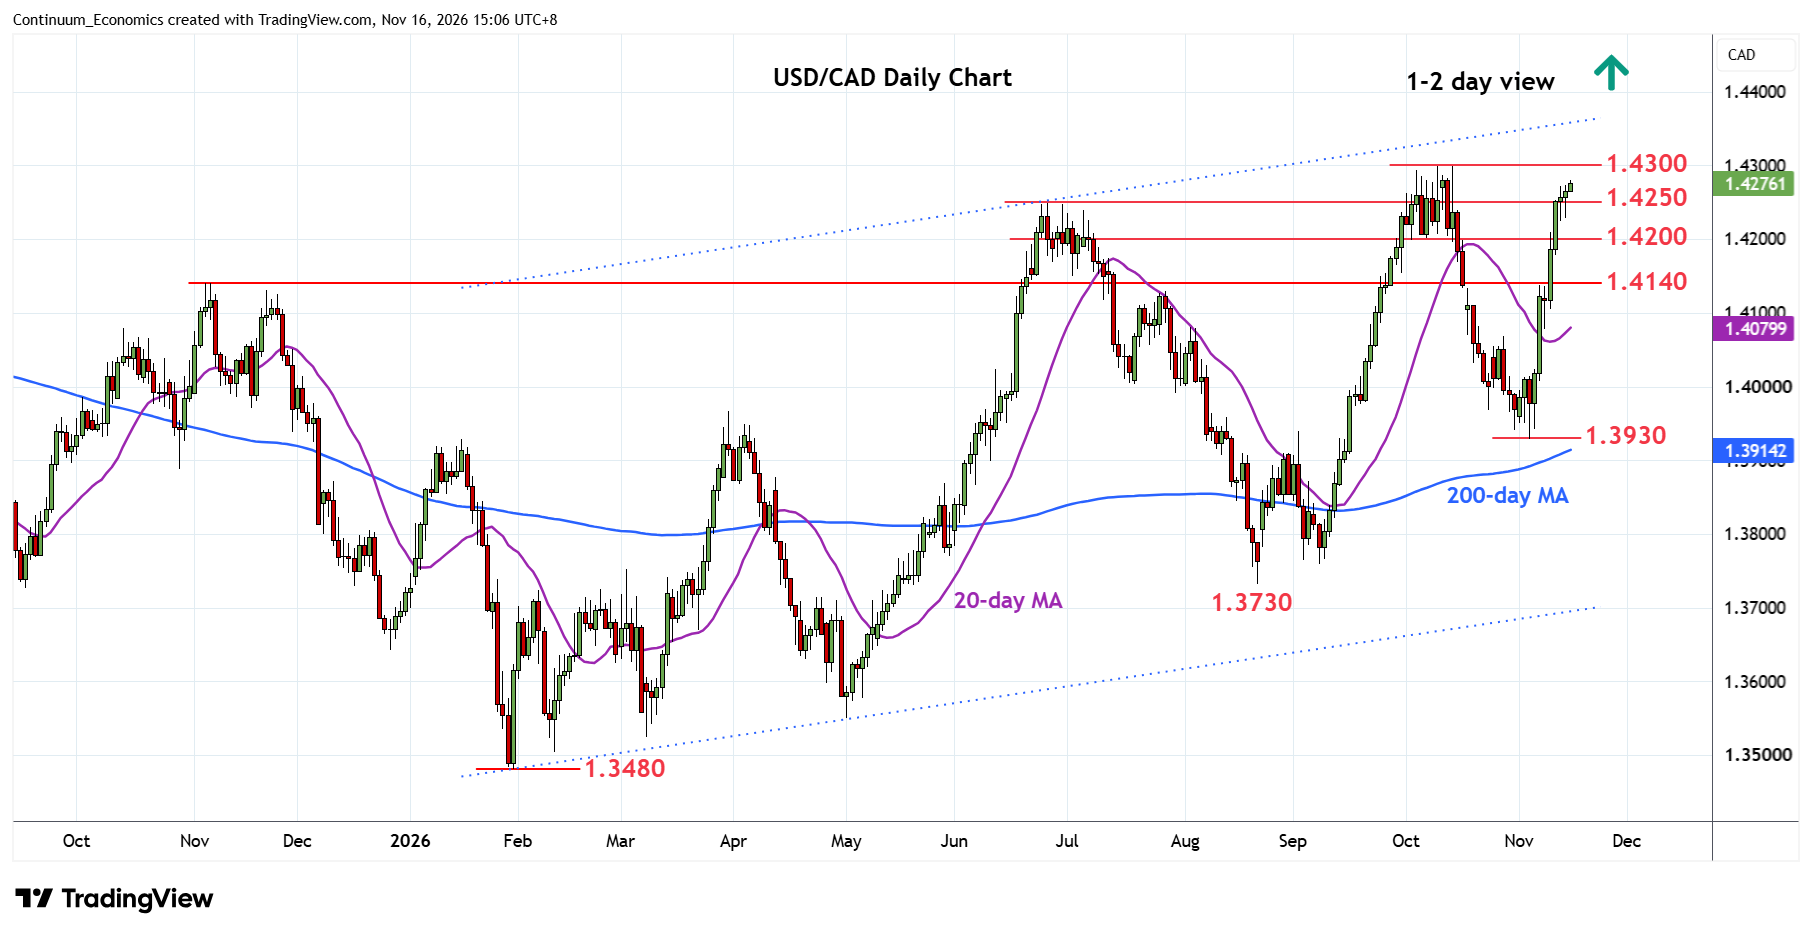
Still a dollar edge in an uptrend, though also still running into some notable recent levels across a number of pairs that will decide the scope for profit-taking consolidation or speeder further step follow-though.
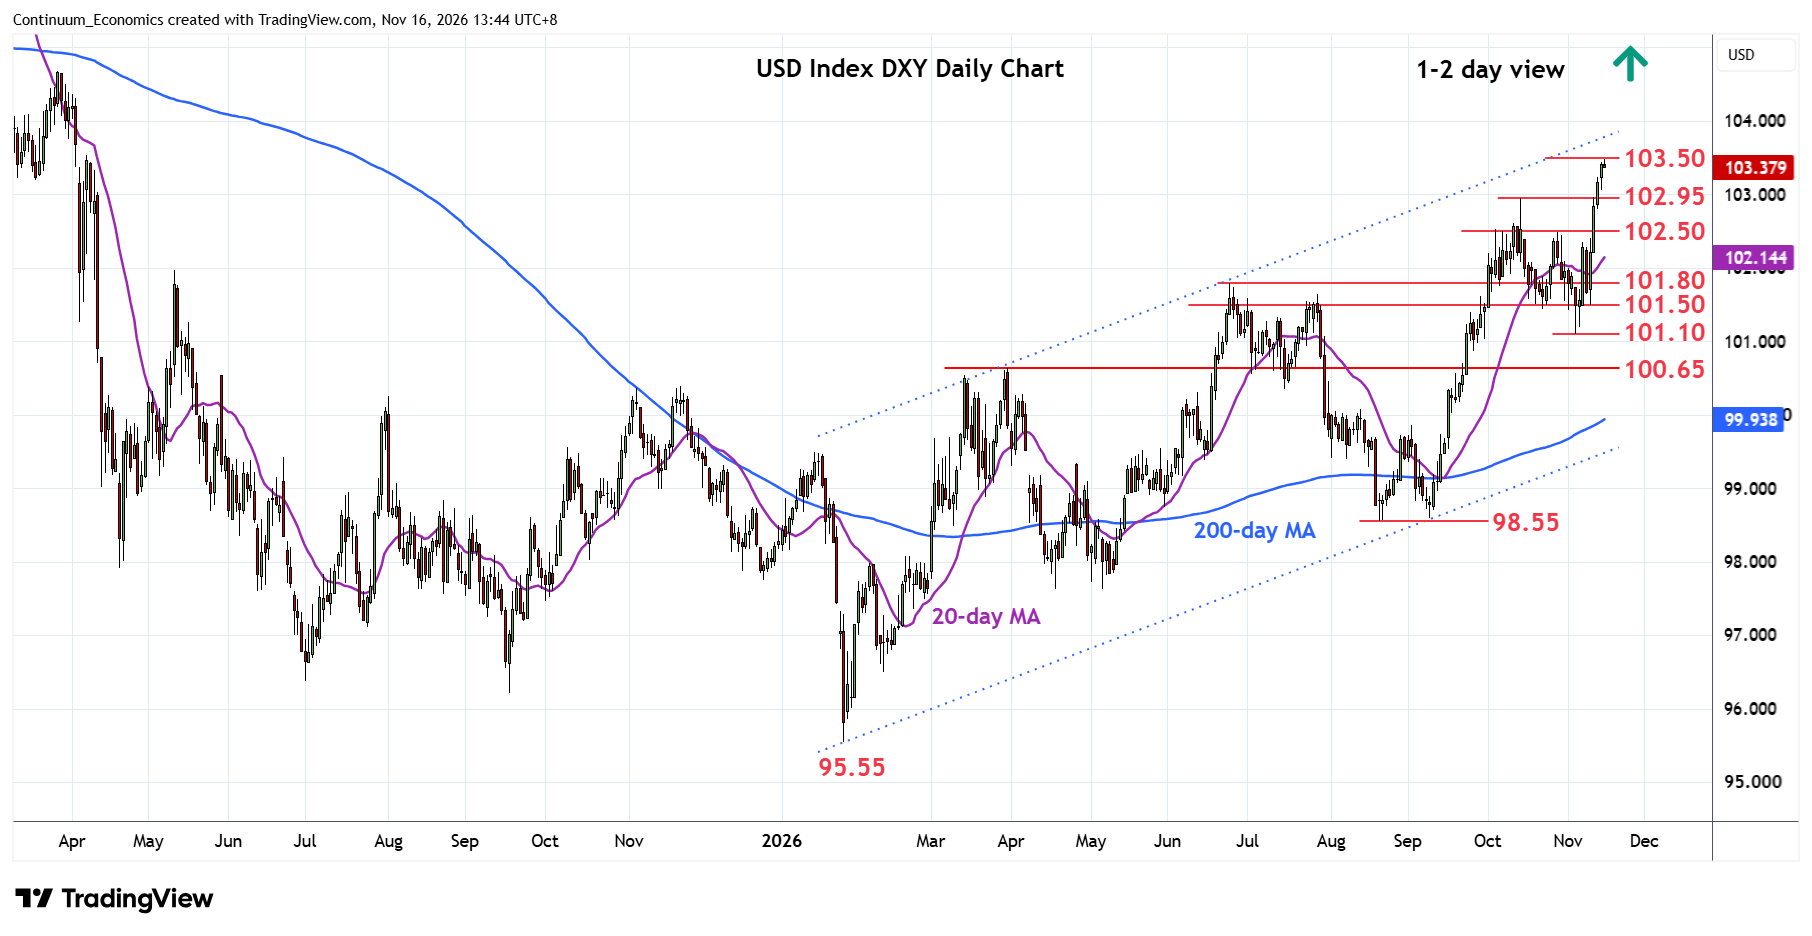
On commodity/oil pairs, the early Oct highs are the level, in Canada’s case marginally aided by a relatively restrained set of CPI number. The pair is running into the 1.43~ range high, which held the Oct rise. Any break above that has some air before it gets to the next band up to 1.45~ from the spring. Likewise, NOK still remains on some retreat as one of the more profitable thematic trades of recent weeks attracts profit-taking to adjust to recent cross-asset performance, even with its still favourable fundamentals particularly on the fiscal side as medium-term factors.
EUR/USD is similarly running into and just through the big 1.10 round figure level, a little less impactful as options position is deemed to have levelled out in anticipation, reflected in the lack of fanfare, but still a major round figure reference and, as noted in the weekly, one that probably has been reached with euro shorts not so far from 2015 extremes. 1.08~ is the next step down if it is taken out though this does require fresh selling interest being drawn into the market from here after an oversold move at this point in time.
Yen meanwhile continues to respect the winning strand from current cross currents outlined in the Weekly, as CHF/JPY makes its way back further to 190~ ahead of the recent 187.50 as some safety margin from 160 is respected for now and a tech feels some caution with Nikkei with it. Big level considerations though do also feature for USD/CHF at this point too at 0.84~ so any extension would need more deliberateness and commitment - somewhat less ‘easy yards unless another FX wide dollar breakout is triggered.
Tech remains in focus too and some big events here to guard against over the next couple of days. Nvidia earnings Tuesday, with as much focus on the guidance around the governance recovery attempt as the numbers, and Anthropic PO the major focal points there this week. On the latter, SpaceX’s example looms as one precedent (pumped through the launch and then heavy dump), although the former was viewed with a lot more suspicion at least before the Cursor acquisition.
Main data this morning from the UK, with average earnings growth nudging down to 3.5% (mkt 3.6%) from 3.7%, and a slightly mixed unstable recent picture remaining on the jobs side: into Sep employment growth outperformed at 156k with the unemployment rate ticking down 0.1pp; with the more timely but volatile Oct data, payrolls moved back to decline at -34k, though the prior month was revised up again to +20k from flat. So data and recent trends can be hard to read. Net story still seems to be one of recent growth holding up with areas of strength, but a very uneven and unstable story under the surface. Scope for labour-driven inflation pressure still looks limited against this uncertain and choppy labour market backdrop.
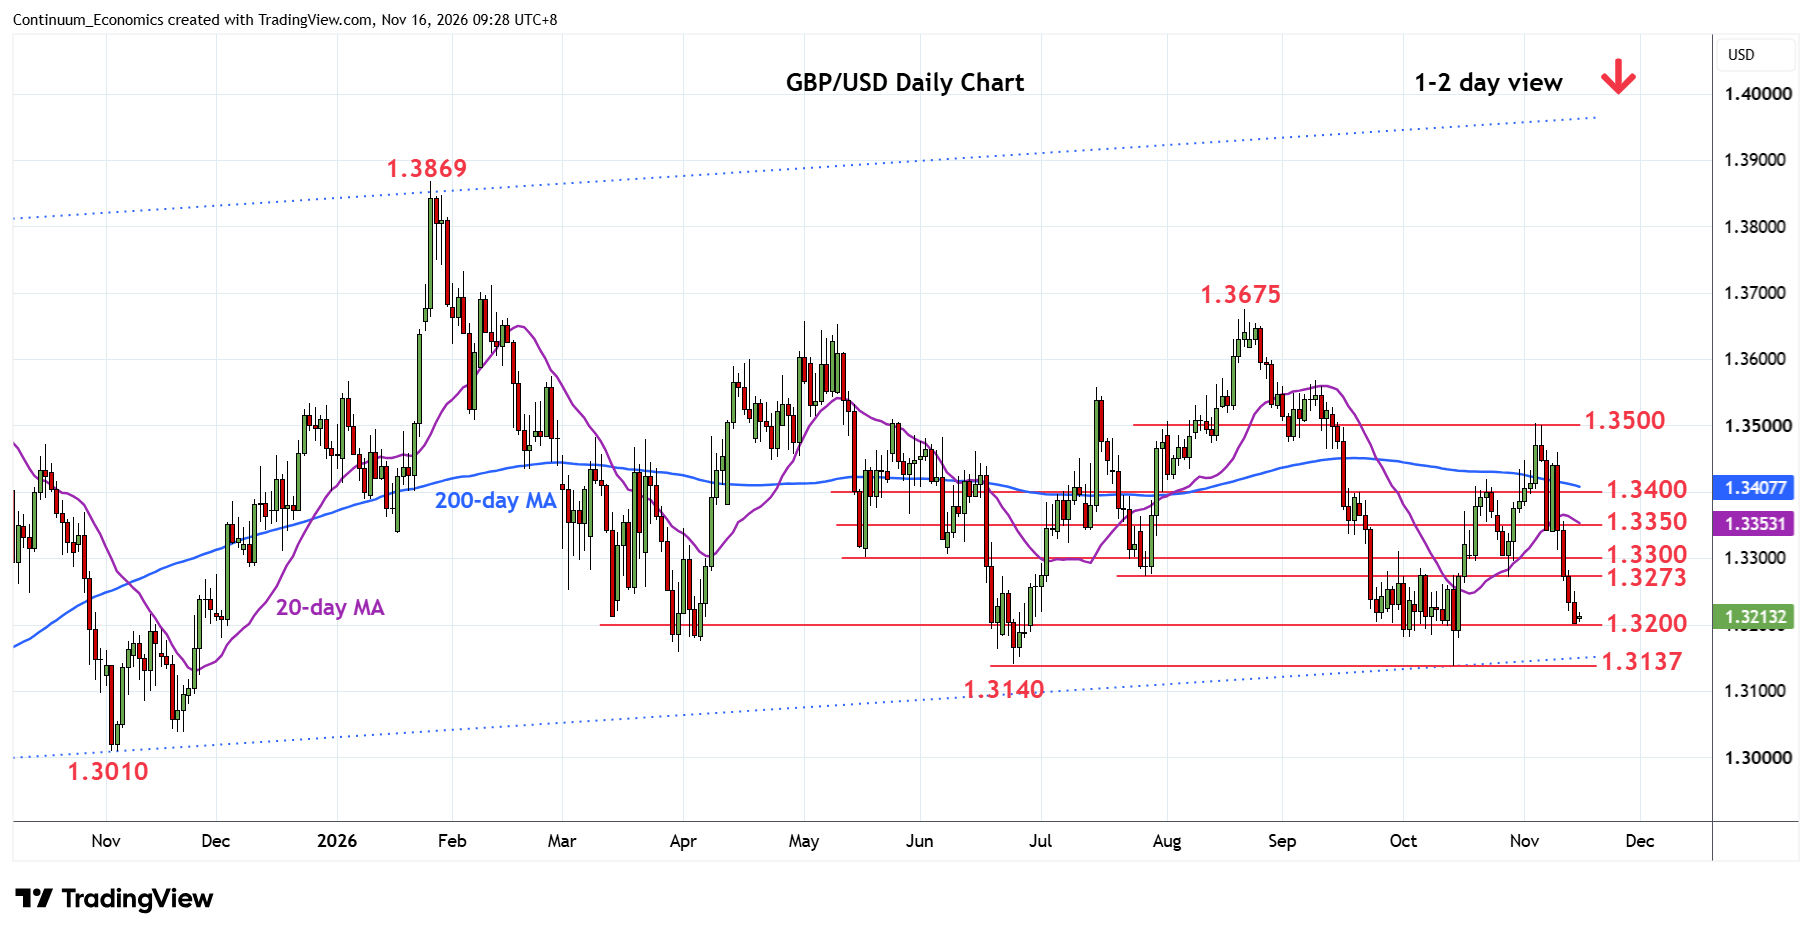
Cable is also entering its own similar reference areas – testing below the 1.32~ test area, where it does have those spike lows to 1.3130 as areas of excess, with potential to overrun into and fill out.
In the US, Fed speakers continue as the market looks to assess the extent and speed of ‘catch up favoured, with Musalem, Hammack and the influential Williams all due on Tuesday
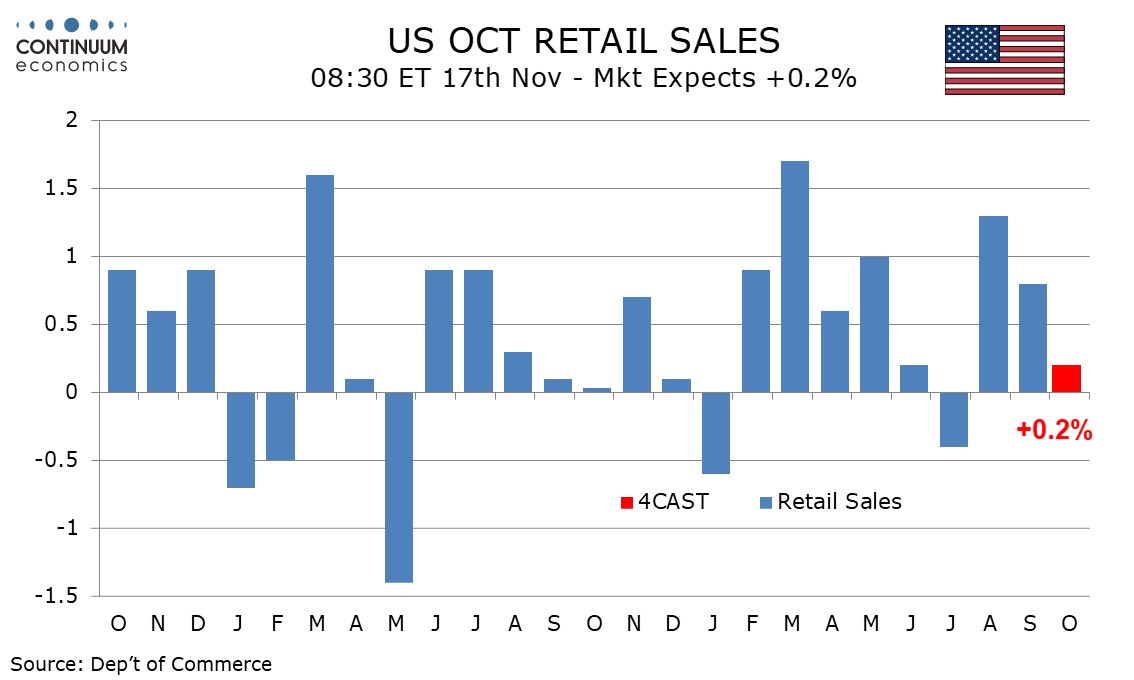
US also sees the most notable data of the week, with October retail sales, where we expect moderate gains of 0.2% overall, 0.4% ex autos and 0.3% ex autos and gasoline. Also on Tuesday, we expect a 0.1% decline in October industrial production, but with a 0.4% increase in manufacturing.