Preview: Due October 29 - U.S. September Personal Income and Spending - Four-month high for core PCE prices
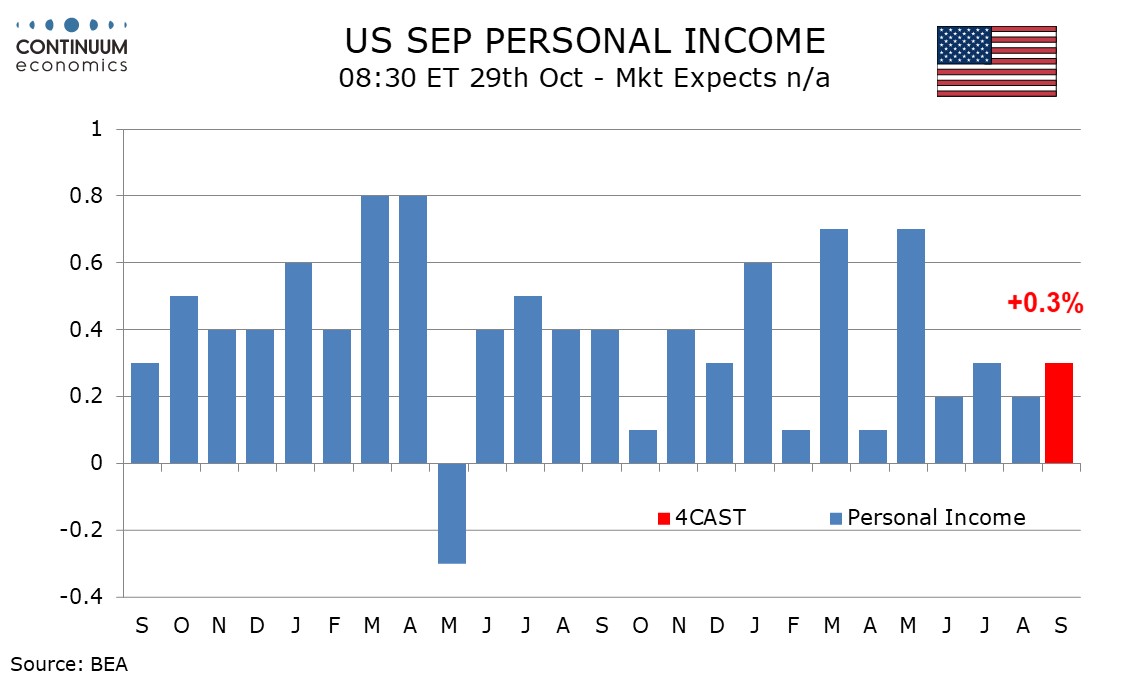
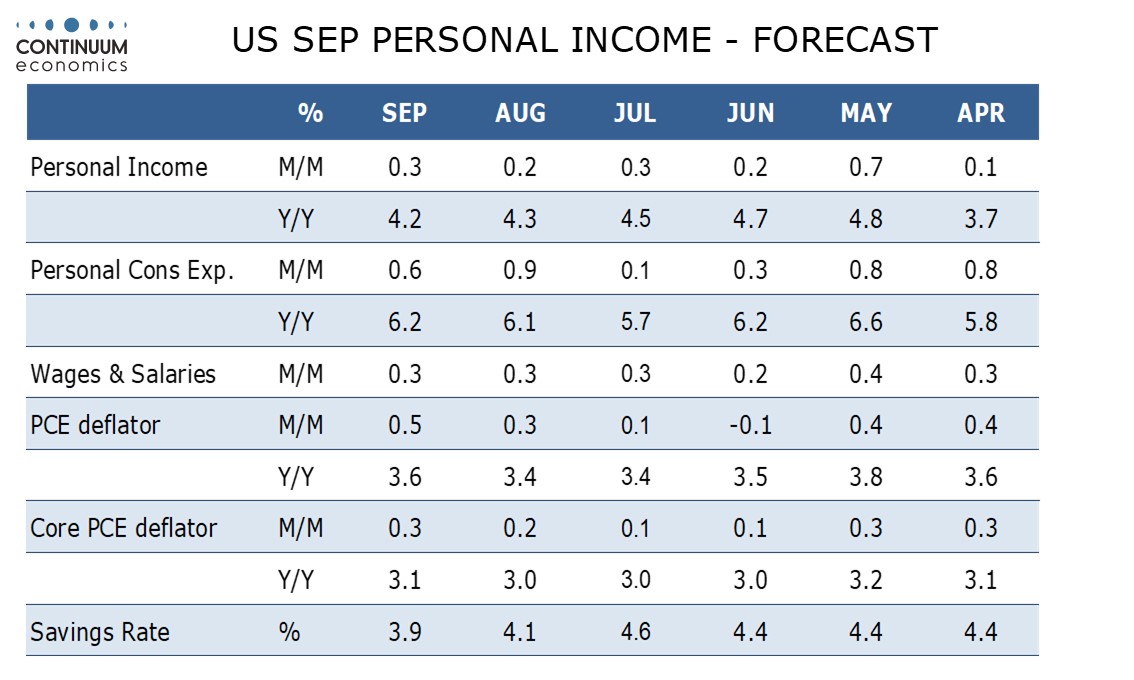
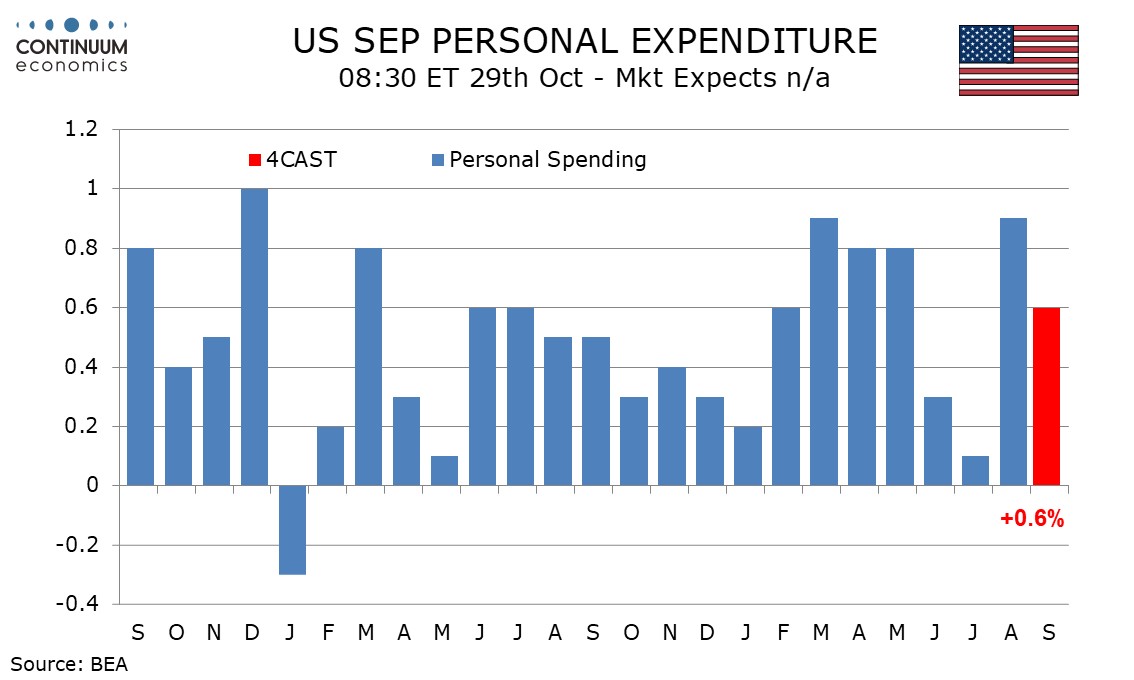
September’s personal income and spending report may be overshadowed by the Q3 GDP release which is due at the same time and will include Q3 totals for each of its components. We expect a 0.3% rise in personal income and a 0.6% rise in spending, with overall PCE prices up by 0.5%, exceeding personal income, and core PCE prices up by a 4-month high of 0.3%.
September’s CPI rose by 0.6% overall and 0.3% ex food and energy, with both slightly more than this before rounding. However with the PCE components of the PPI mostly modest and PCE prices less sensitive to gasoline than the CPI we expect overall PCE prices to rise by only 0.5% and the core rate to be close to 0.3% even after rounding.
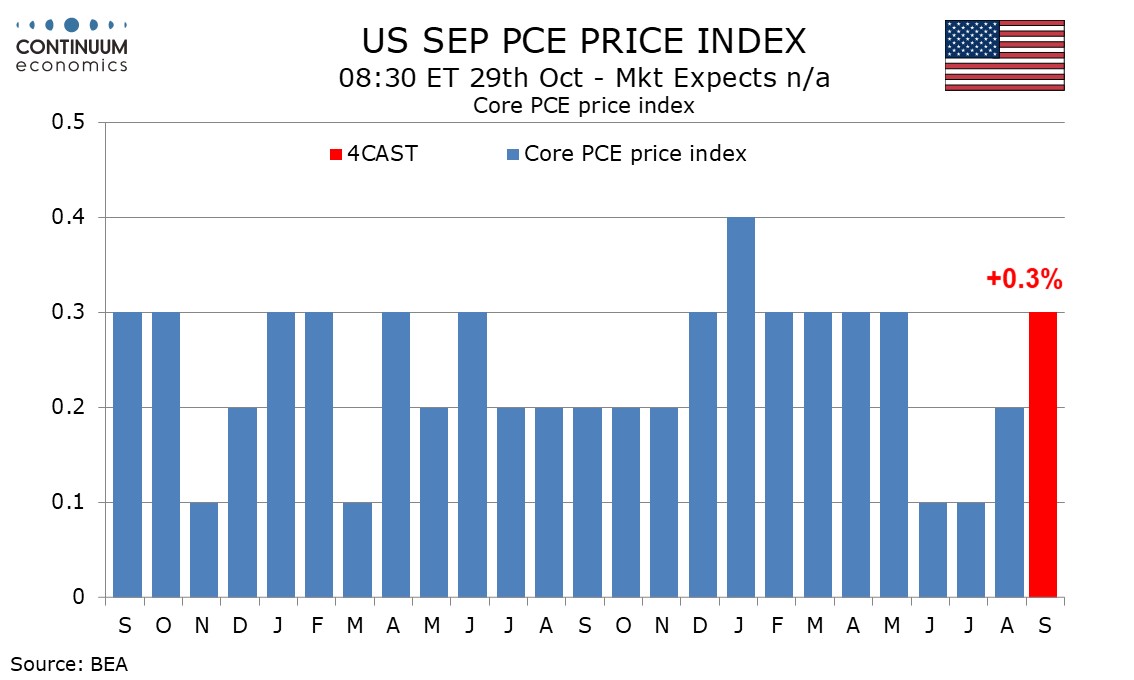
This will still be a 4-month high for core PCE prices where yr/yr growth looks set to rise to 3.1% from 3.0%, while overall PCE prices rise to 3.6% yr/yr from 3.4%. Both these yr/yr rates would also be 4-month highs.
Retail sales rose by 0.8% with a 0.9% rise ex auto but most of these gains came from higher gasoline prices. The control group which contributes to GDP rose by only 0.1%. We expect a 0.5% increase in services, matching August’s gain, leaving overall personal spending up by 0.6%.
We expect a 0.3% rise in personal income, with a third straight 0.3% rise in wages and salaries, marginally stronger than implied by the September’s non-farm payroll, after August data which underperformed the payroll implications. This would see the savings rate slip to 3.9% from 4.1%, reaching its lowest level since October 2022.