FX Daily Strategy: Asia, Sep 22
USD/JPY nudging up in the 157-158 band, while keeping ear out for the MoF during Japan holiday
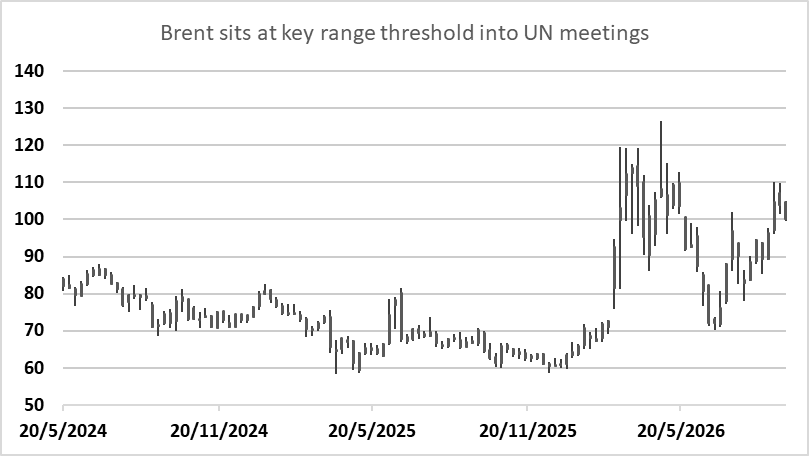
Key focal point remains word on diplomatic efforts and US plan at UN meeting. Oil sitting at key $100~ Brent range threshold support prior
Outcome will be pivotal in setting this week's tone for risk, dollar, bonds
Tuesday is a relatively quiet day on the calendars (key event aside) and Japan remains on holiday so that may tend to reinforce the early lethargy as the market absorbs last week’s events. The remaining central banks, the most interesting of which will be Norges, arrive on Thursday.
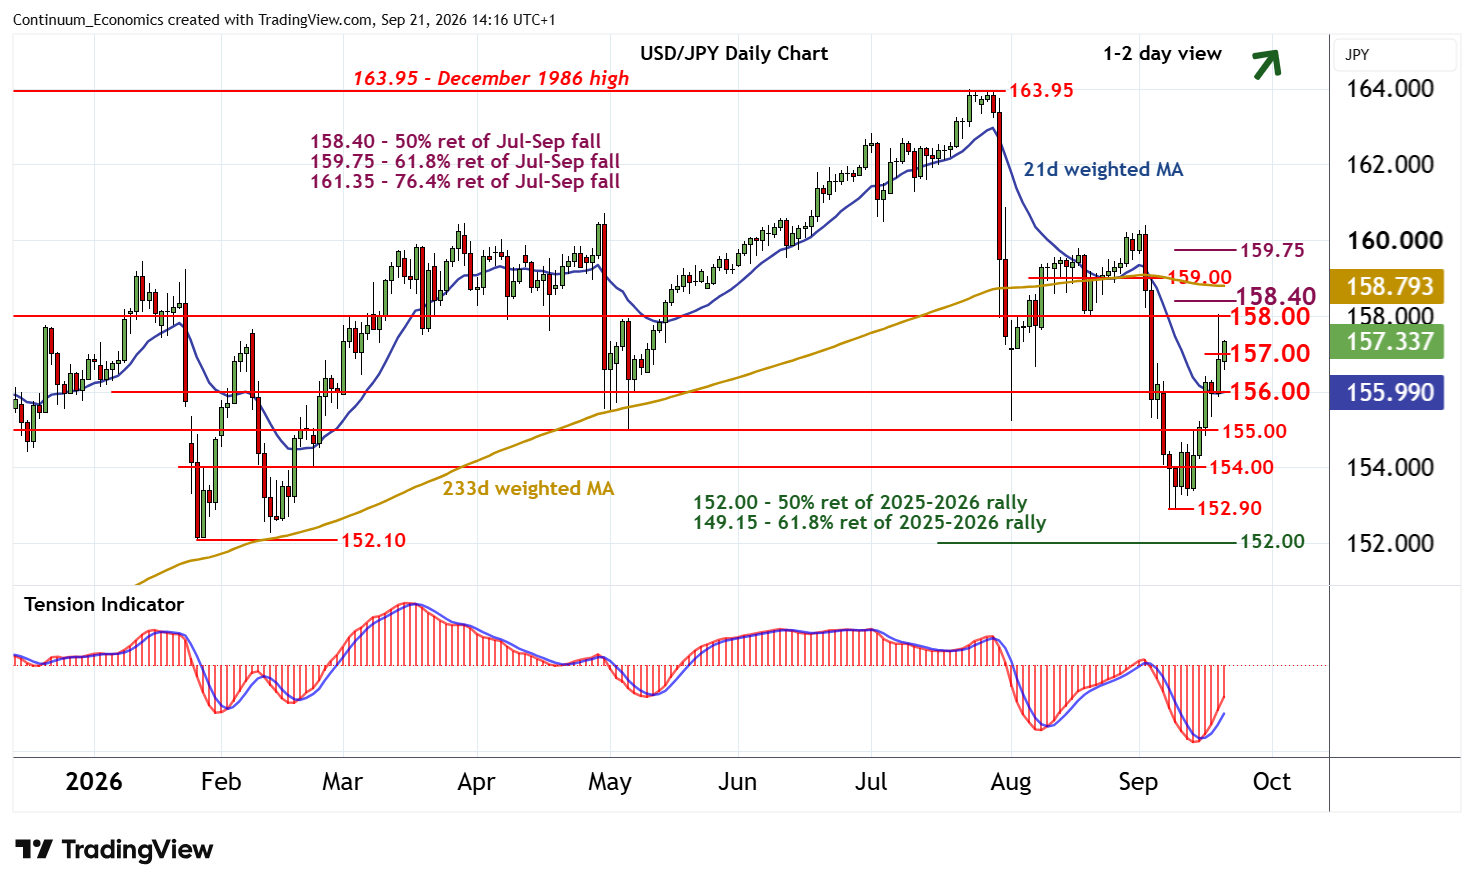
USD/JPY is nudging its way up within the 157-158 recovery band from last week, with one careful ear open for MoF noises. ‘Checking’ talk helped, well, check things on Friday. This remains a useful occasional tactical tool for Japan authorities, helping to stop the market getting on a fast money tear. But it’s one that doesn’t survive overuse in MoF want to avoid 'cry wolf' diminishing returns.
Japan is on holiday until Wednesday and that environment does, in theory, imply elevated intervention risks, given past behaviour. At the moment however, it doesn't really make sense for MoF to get involved down at these levels even with the recent smart bounce.
That just wastes ammunition, generates trading ranges and sets up an unnecessary fight. Current action remains well within the bounds of a corrective move from the big leg down and it’s better for Japan to bide its time. The BoJ could have been a little more street smart but that is another story. “If I were chancellor”, the recommendation might well have been to speed up the remaining policy normalisation, while slowing down the QT. At the moment though, the BoJ does not seem game to react on either.
Technically, USD/JPY does look like it will want to tiptoe to a 158 re-test, but 158-158.40 offers resistance and should see capping. The market might ‘spoof itself’ if it makes a faster upside test and then gets cold feet or chopped by false rumours. IMM data showing the market caught long yen into the sharper bounce last week also sets the backdrop to the current squeeze and the current positional churn (some shorts wanting to enter at better levels, but also stale short and caught positions looking to exit flat).
Geopolitics remains the big driver this week, with the UN in sharp focus given the heightened interest in potential diplomatic efforts on Iran and the Middle East, amplified by last week’s Axios story.
The latter suggested the US could be presenting a new plan to leaders Tuesday, and oil has already been trimming back to key support around $100 on the Brent front month prior to this, while risk has been supported and yields trimming back. This is pivotal to the week’s price action as any genuine signs of progress could see a risk on, carry mood take over the week’s trading vibe, with bias towards some oil currency slippage, while another false dawn and oil bounce from the support test would keep the skew towards immediate dollar follow through.
As for data Tuesday, UK PSNCR (mkt GBP15.5bn) always of background interest and into the Budget, though not a current primary FX driver (attention actually more on France in this respect), with CBI trends also later. Fed’s Williams and Jefferson are due to speak in the US, watched for any forward guidance, on an otherwise light day.