FX Daily Strategy: Asia, Oct 29
FOMC offers no great shocks and leaves market pricing for a Dec hike
Focus turns to the ECB, looking for any dovish deviations, with one eye on financial conditions
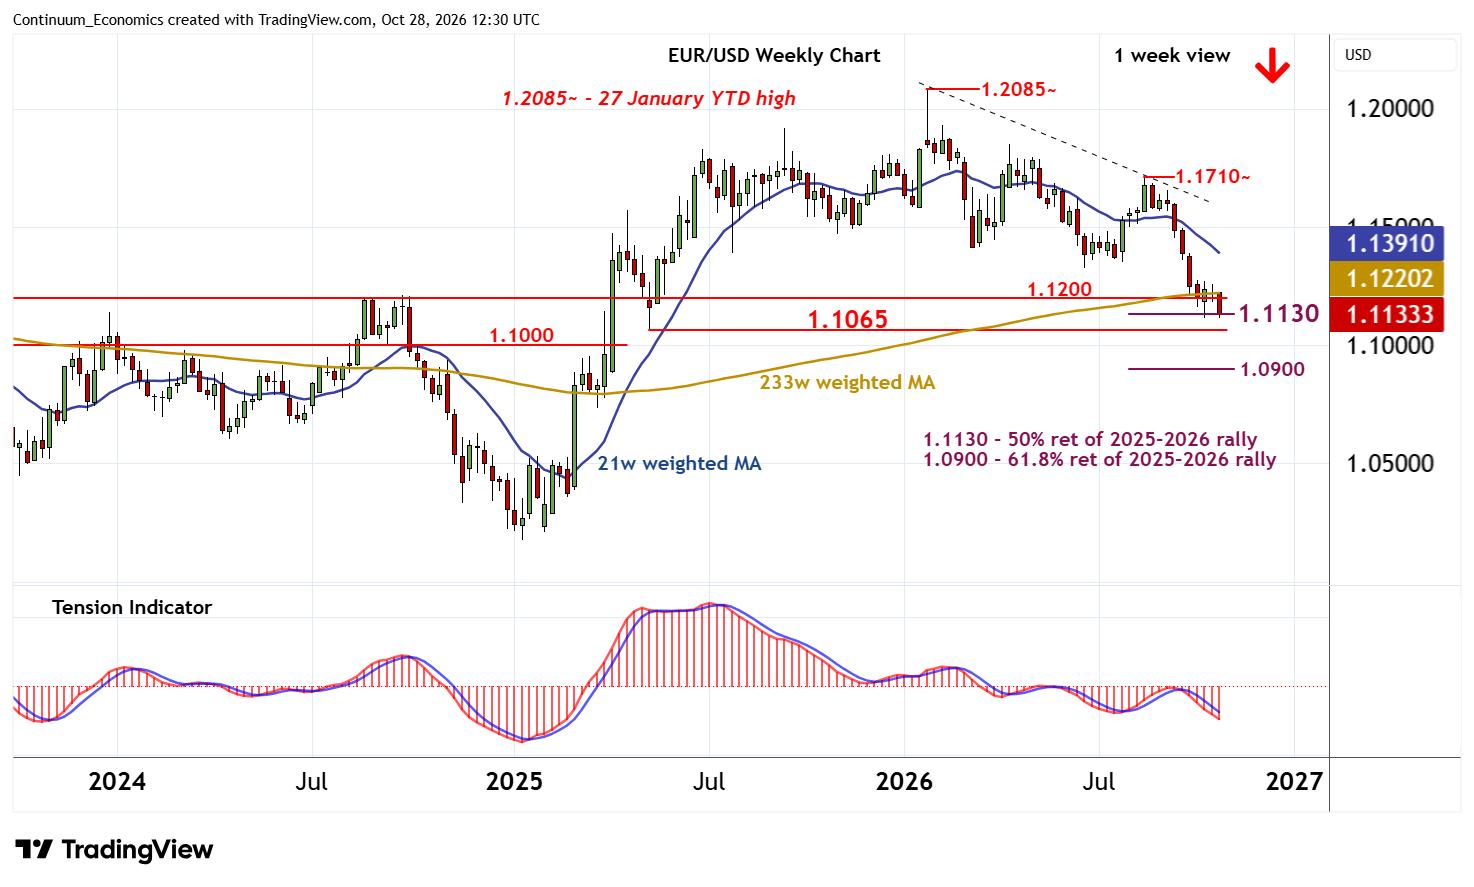
EUR/USD would need to regain 1.12 to point to fast money s/t profit-taking winning out, else bearish structure continues to dominate
US PCE and GDP data main calendar interest, should support Fed assessment
After the big run-in, the FOMC didn’t offer any huge surprises though the tone and, to an extent, the (modestly) split vote, all went with the grain of existing assumptions. In short, the market has few initial reasons to think that a Dec hike does not remain fully on track.
Dissent was not huge in scale - it could have been more, though the personnel were a bit surprising (Cook less likely than some other recent hawks) - but still shows where the bias and direction sit. The statement also largely read like a rationale to hike rather than one to ‘accumulate information’, with its upgraded characterisation of growth as strong, while still viewing inflation as elevated. The overall impression then was of a marking time before delivering the next move in Dec, bar any shocks in the interval at least.
Kneejerk FX reaction was limited, in keeping with that broadly as expected result, with yields also largely cementing rather than notably extending or unwinding the corrective action prior, 2s within a basis point or so of pre-announcement. Recent highs either side of 4.8% still offer resistance and any further backup would likely be more global backdrop dependent (further easing in indirect support from France and tech). There was a touch of dollar sell the fact, to give up the dregs of the intraday event positioning, but not enough yet to be shifting the balance.
Perhaps ultimately the most concretely impactful announcement was the move to 7 policy-setting meetings out of 8 next year and 6 the following, though that is more of a micro-detail for the money market curve and dated futures contracts.
With that event risk out the way, attention now turns to the ECB. Focus here somewhat is different, with interest directed more to whether the statement and the presser give more dovish prominence to tighter financial conditions than recent meetings, building on the recent remarks by Lagarde. See (here) and (here) for more on that.
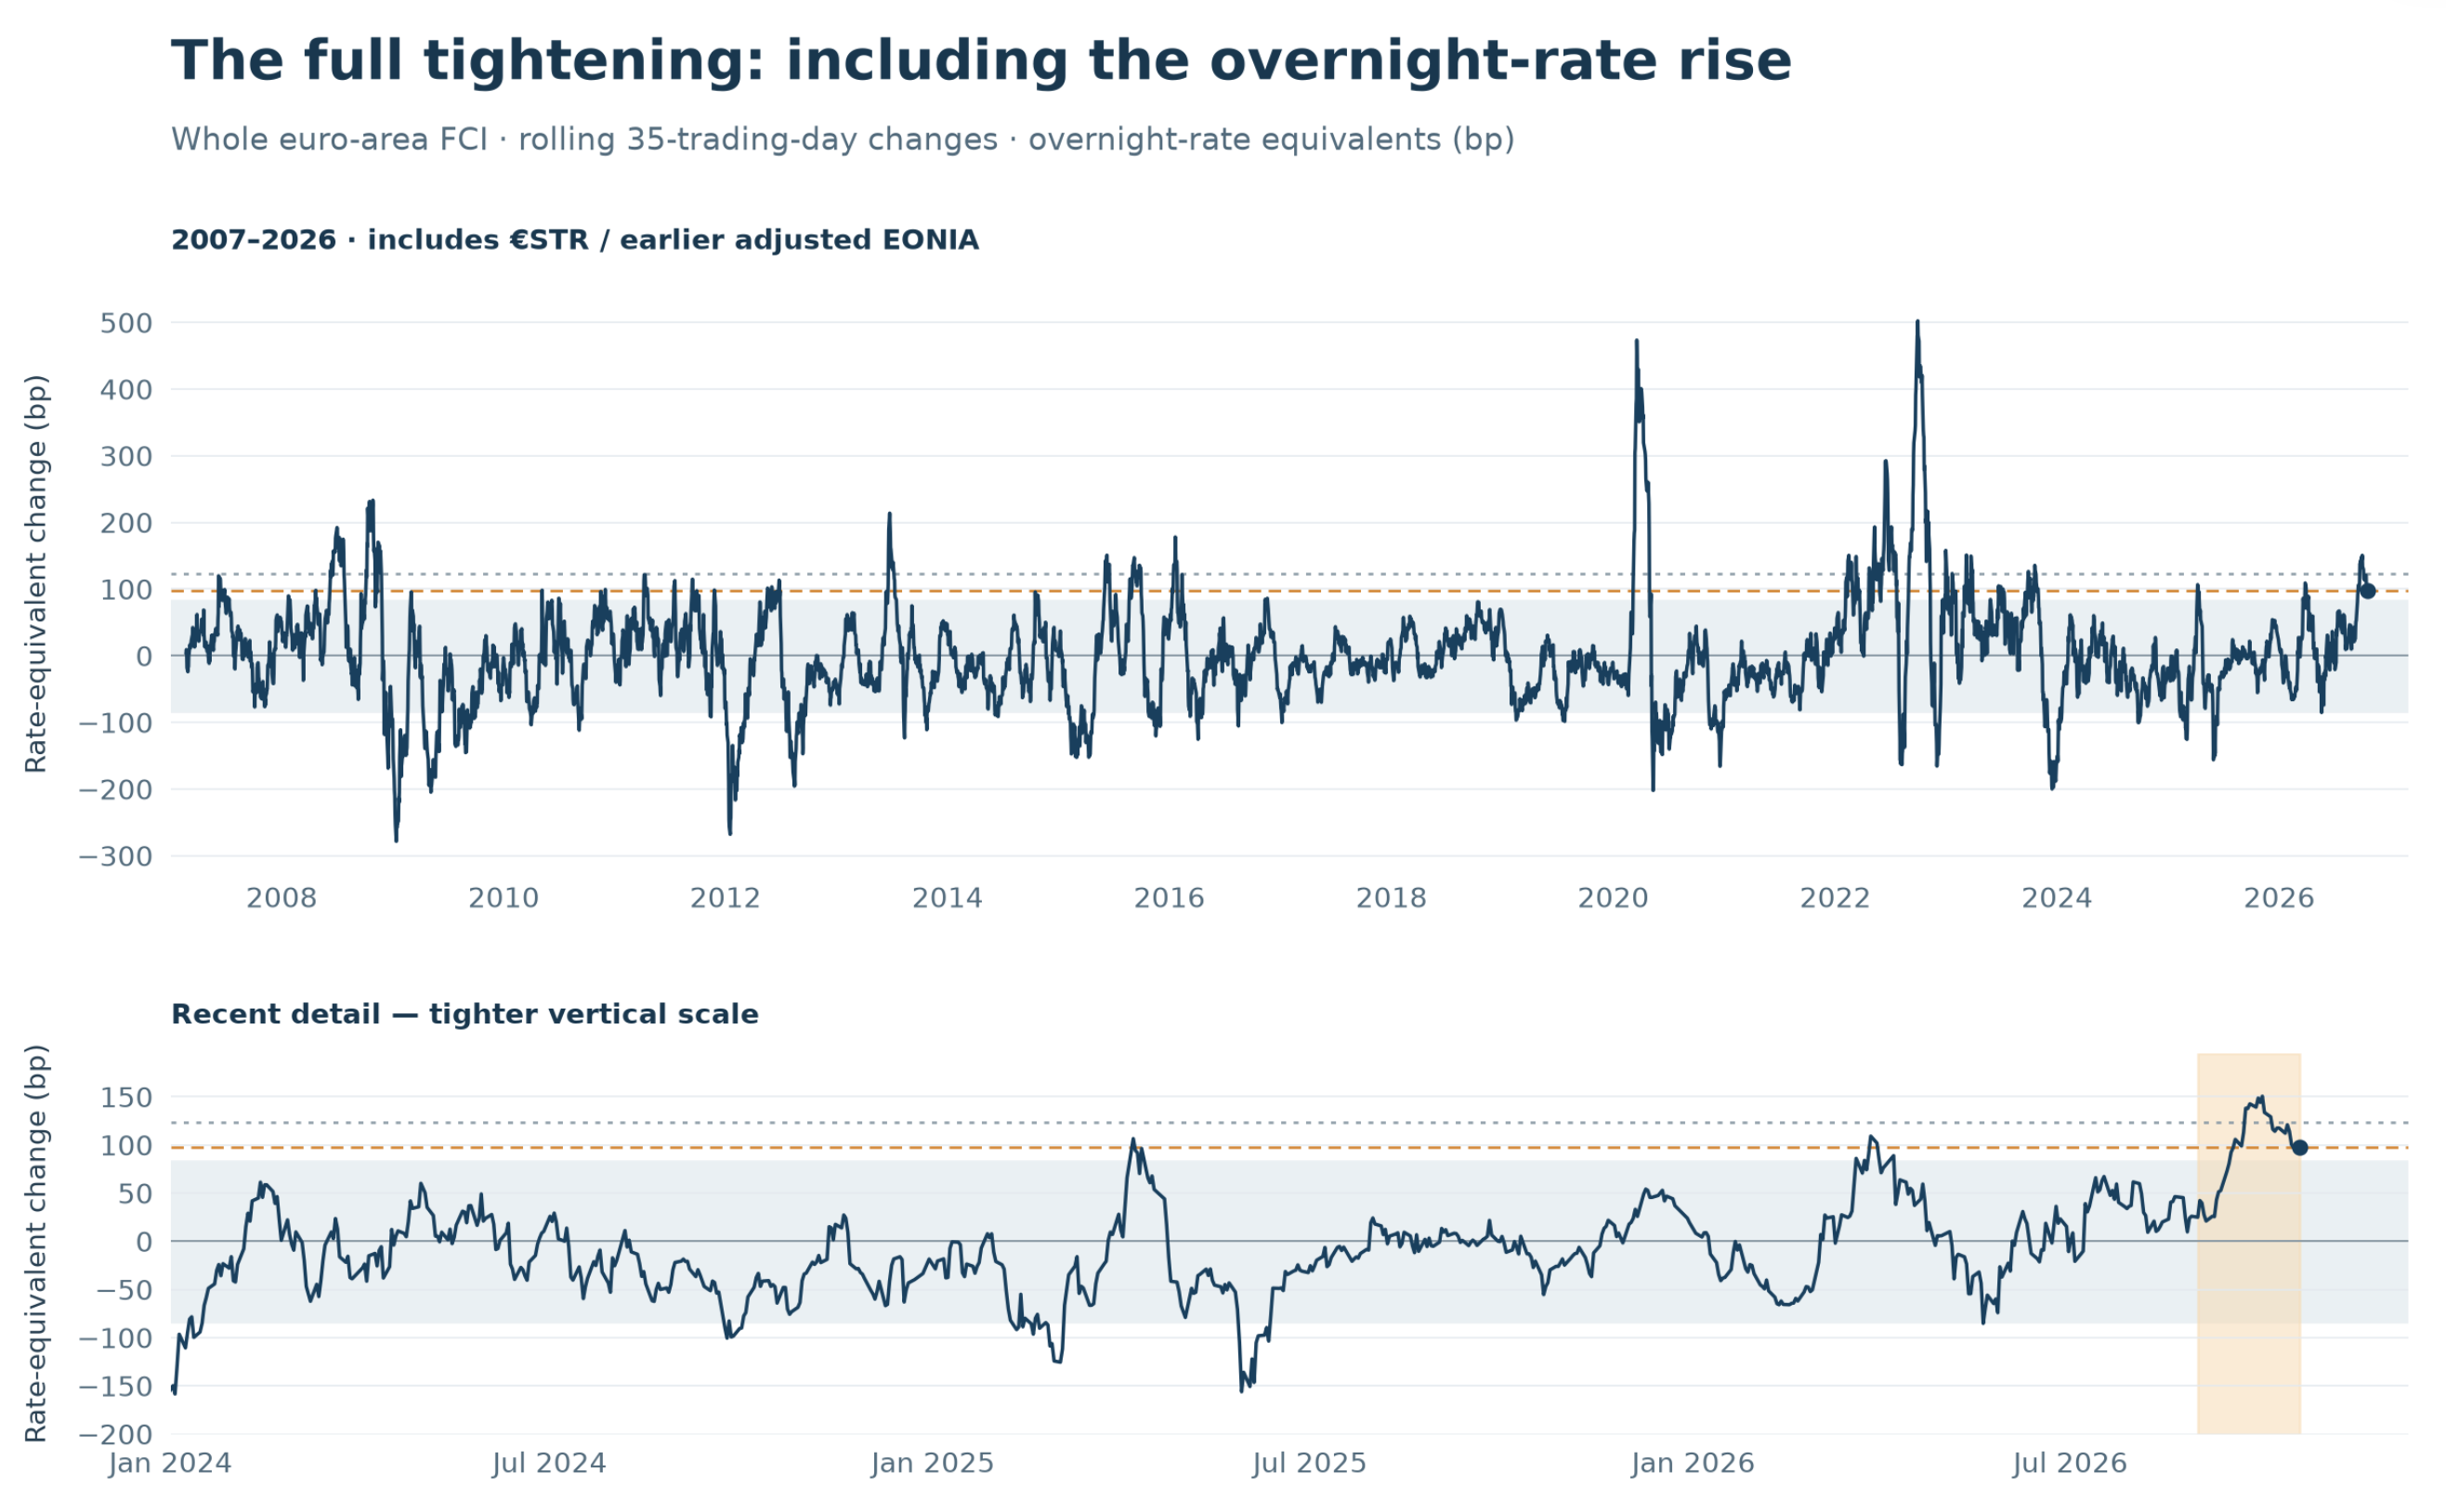
We maintain our call that the ECB is likely to hike once more, and likely in December, taking the deposit rate to 2.75%. But any further significant tightening in financing conditions between now and December could change that view. Markets are currently pricing 3 hikes by December of next year while we continue to see 2.75% at the peak of the current tightening cycle.
For the euro, the question to an extent is how much ECB tone ‘dilution’ has the market already priced in. The overall current structure for EUR/USD does remain bearish and it would need a move clear of 1.12 to suggest some fast money ‘buy the fact’ profit-taking was taking over. Absent that, flat consolidation keeps things bearish and a break of recent lows could look next to 1.1000~ big figure reference, ahead of the 1.0900 Fibonacci retracement.
Outside of the ECB, today also sees Swedish Q3 GDP were expectations centre on some moderation to 0.3%q/q and 2.9% from 3.3%, still a pretty decent pace. SEK remains very sensitive as ever to the wider risk environment more than domestics.
UK only has money and credit data, after sterling came unscathed through the low-key Budget.
Eurozone sentiment survey is seen showing some slippage with economic sentiment consensus of 97.5 from 97.9.
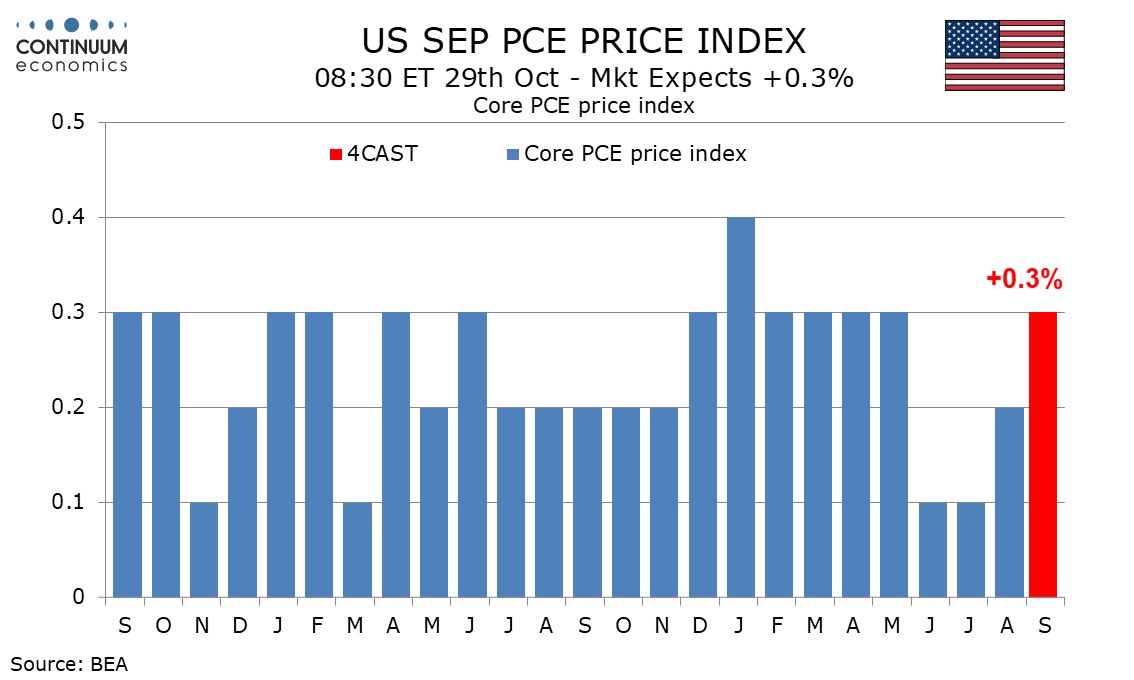
More notable from the US later is the latest PCE report and Q3 GDP that should overall leave the post FOMC outlook intact.
We expect a 0.3% rise in personal income and a 0.6% rise in spending, with overall PCE prices up by 0.5%, exceeding personal income, and core PCE prices up by a 4-month high of 0.3%.
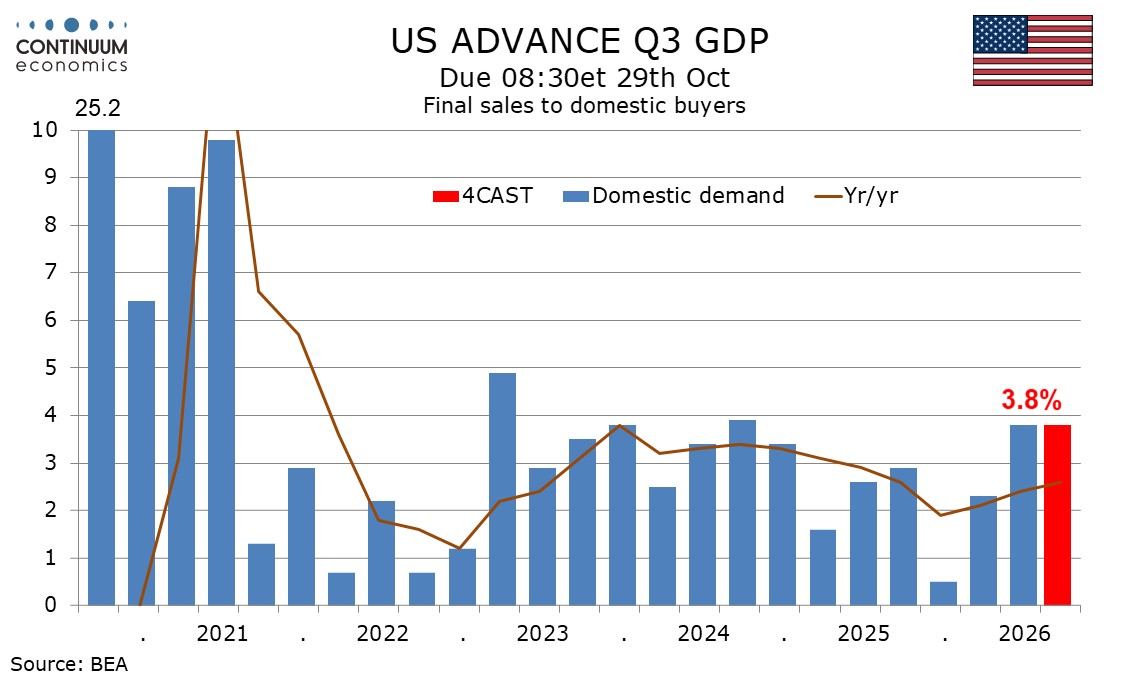
We also look for a Q3 GDP increase of 2.8% annualized, a modest acceleration from the two preceding quarters to a 4-quarter high, consistent with the Fed’s relatively upbeat assessment. We expect a 2.4% increase in core PCE prices, still above target but the slowest since a matching Q3 2024.