FX Daily Strategy: Asia Oct 6
• USD watching U.S. Bond yields.
• French budget and EUR/USD and EUR/CHF.
• Trump need a positive October surprise – 2nd ceasefire?
The rise in U.S. yields outright, as well as widen spreads against certain DM government bonds markets has been an important factor behind a firmer USD through September. However, the latest NFP report dampens Fed tightening prospects and Fed Williams and Logan on Tuesday and FOMC minutes Wednesday will likely reinforce this trend. If the core CPI is also controlled it would help temper 2027 tightening fears, but still keep December a live meeting. This could mean that 10yr U.S. Treasury yields could now pull back to 5% multi week, as the scale of the recent selloff was amplified by liquidation by speculative holders of Treasuries.
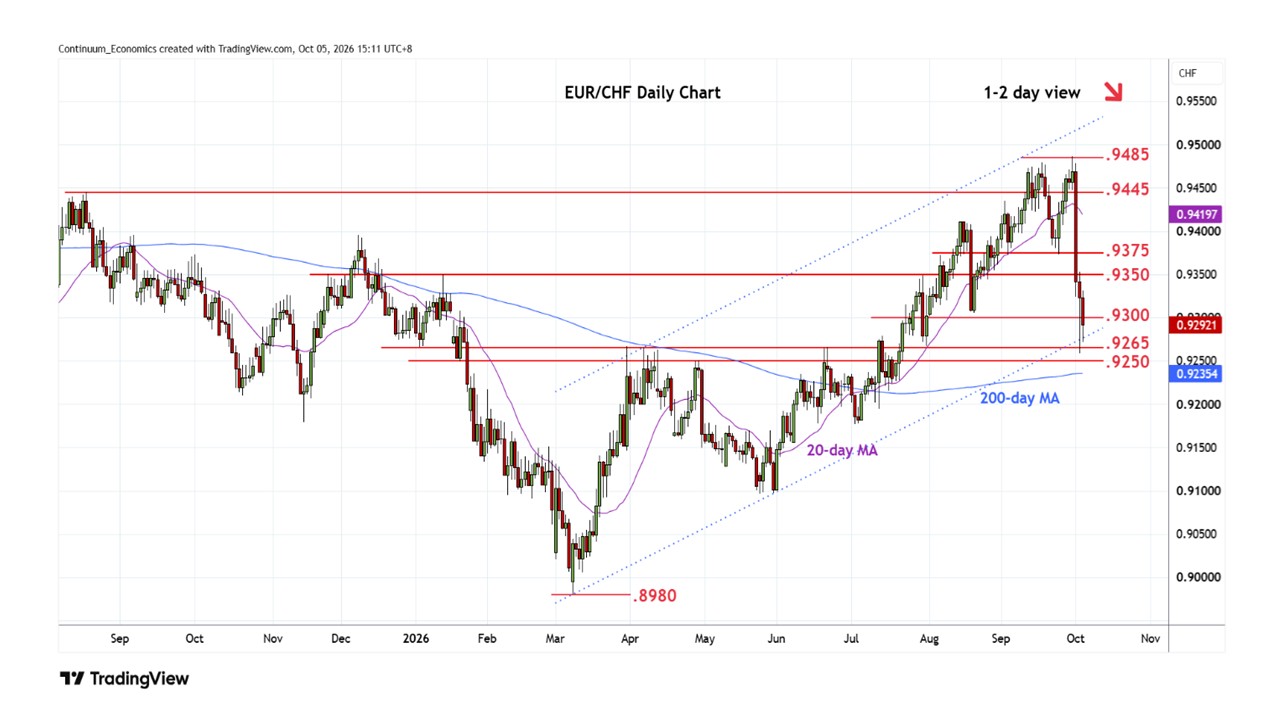
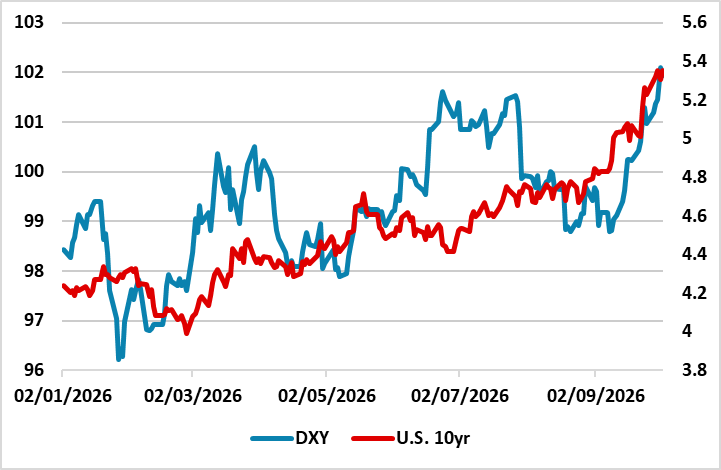 In turn this could mean that October sees a partial correction to the September USD strength. Some of this could be seen in the coming days. This could be GBP/USD more than EUR/USD, with scope on cable to 1.3300. USD/JPY would normally sees JPY gains in this type of environment, but the critical support at 158.00 (200 day MA) could need a new catalyst to trigger a break down to 156.50 and 155.00. EUR/USD can see something of a correction as well after last week selloff, but it depends on the French-Bund government bond spread narrowing. Hopes are growing in Paris that the National Rally will support the 2027 budget bill, where the debates start on October 13. With Le Pen ahead in the 2nd round presidential polls, she likely does not want to inherit a fiscal emergency. Even so, the French-Bund spread would likely have to lead EUR/USD. The same holds true for EUR/CHF, where the CHF has benefitted from safe haven flows with the sharp rise in 10yr French spreads. Narrower French spreads could prompt a correction to 0.9350 on EUR/CHF.
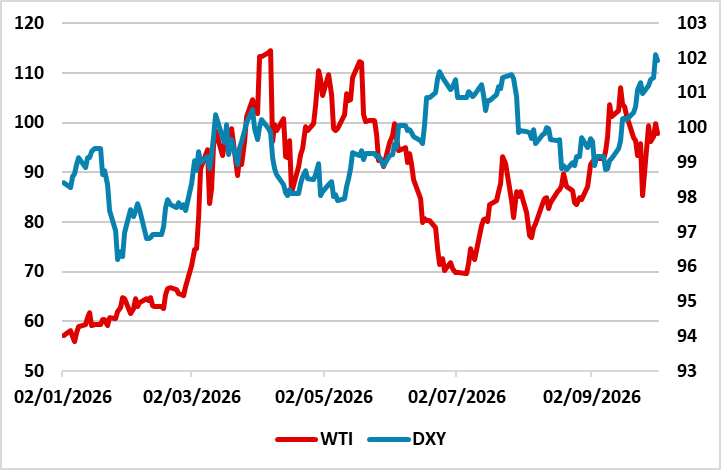
Finally, President Trump needs a positive October surprise to help the GOP in the November 3 mid-term elections. A 2nd ceasefire with Iran would help to produce lower gasoline and diesel prices and perhaps help the GOP. However, tactically it is better to do this in the W/S Oct 19 or Oct 26, given the risk that the ceasefire may not hold. Reaching agreement with Iran too early, risks it unravelling before the mid-terms. However, the June/July ceasefire in the Straits of Hormuz did lead to a noticeable decline in oil prices, but the USD did not fall. Though the direct effect of a 2nd ceasefire may not hurt the USD with lower oil prices, the indirect effect could be to bring 10yr Treasury yields lower and prompt a 2nd corrective phase for the USD later in October.