FX Daily Strategy: Asia, Nov 5
Dust settles on midterm, chaos avoided, mkt focus on implications for oil and tech
BoE hike a done deal, but build up suggests a 'dovish hike' relative to mkt
The day after an election is often not necessarily the time for sweeping conclusions on the path ahead – first, and even second reactions, especially during Trump’s terms, haven’t necessarily always held, especially with regard to the swinging implications for the dollar.
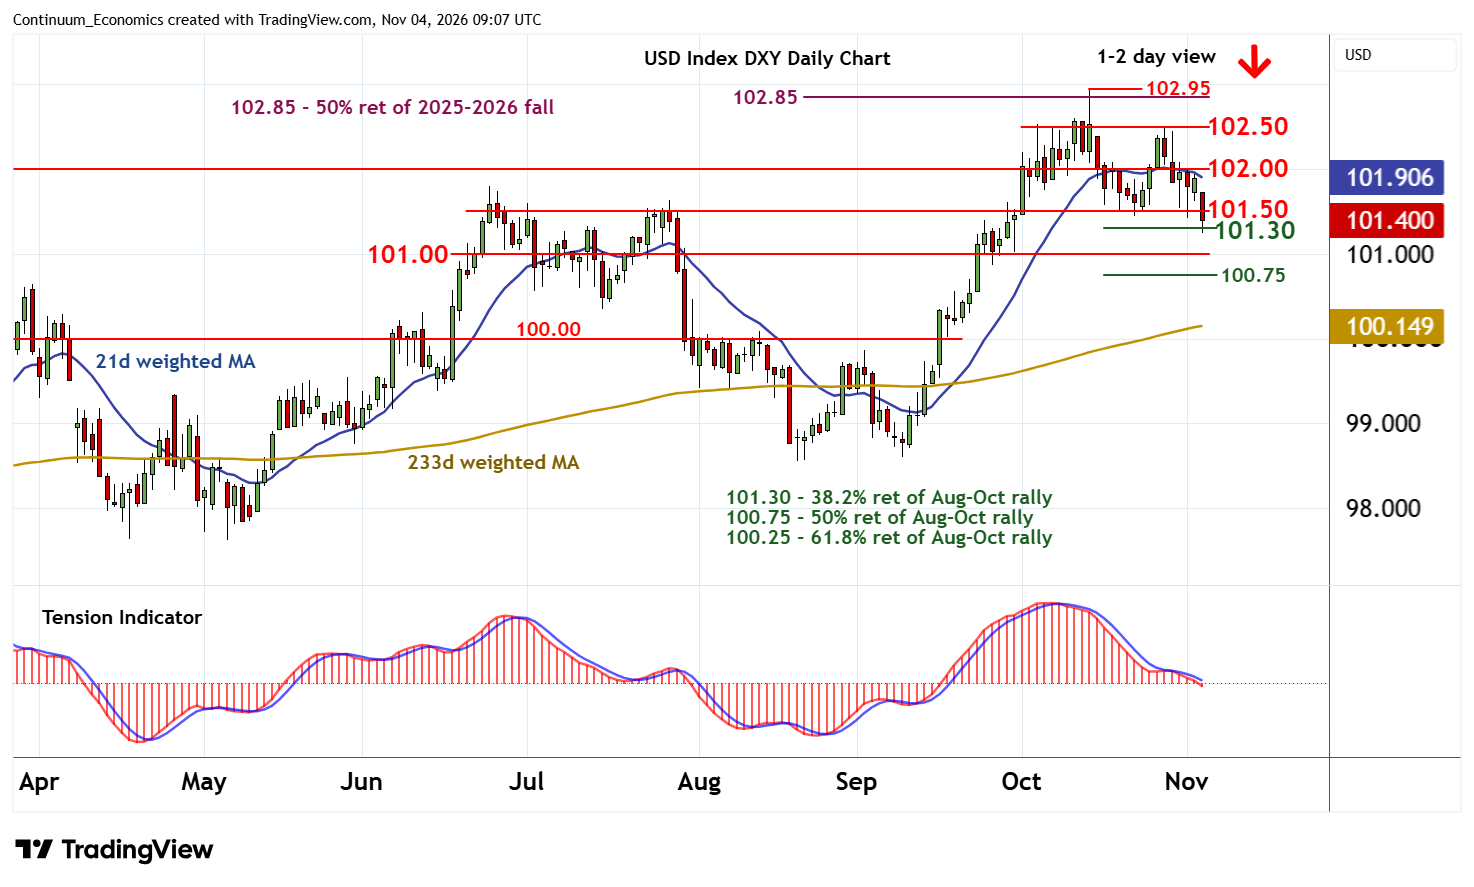
Two key inflection points however clearly do emerge out the other side – one in tech sentiment and the other in geopolitics and oil.
Focusing on oil, Trump himself has acknowledged that Iran was ‘part of it’ when it comes to the trouncing, though that doesn’t necessarily translate into obvious repentance nor necessarily reasons and incentives for lessons learnt. Still, we’ve been discussing the potential for US and Israel results to significantly impact on the path ahead from here. Even before the vote, it has been clear that Trump was already apparently rowing back from the Israel-led post-election strikes strategy, towards some recent reaching out, via written communications and more recently through intermediate talks. The market had become quite pessimistic in terms of the odds, and skew of different scenarios. As such, even the reintroduction of resumed diplomacy has been enough to drive prices back into the Oct range. For US crude, on the front month that band extends back down to the $90-85 base.
NOK has typically been the beneficiary of hawkish recent sentiment and has the most ground to lose in the event of strikes being parked for the next 2 months, potential Congress funding constraint in the new year, and more broadly positive hopes regaining ascendancy.
EUR/NOK squeeze could continue to 10.5~ retracement next.
On the wider risk side, today’s action leaves the nearby situation genuinely balanced on a tipping point, with price action in the next session or two potentially quite decisive. The Asia post-result spike test into the summer lows region and then recovery could prove to be a stop-triggering end to the leg, with parallel action seen in volatility.
In that event, recently favoured defensive positions (yen and swiss risk crosses) could come in for some correction and then consolidation. There are certainly some new grounds for positivity having cleared this event risk.
For one, the decisive nature of the results prevented the chaos of any dispute and obstruction, Trump instead throwing in the towel in accepting the results and the Democrat’s ‘good job’. That political disorder scenario was a very material unspoken background risk prior, and result look to have removed a major end of year factor. More generally, while the economy will miss the direct support of further ramp ups in pro-cyclical fiscal support escalation, this driver was anyway at the point of adverse effects starting to dominate through the bond market. If pressure on US bonds at the margin can ease, at last in terms of some premia escalation, then that is also helpful.
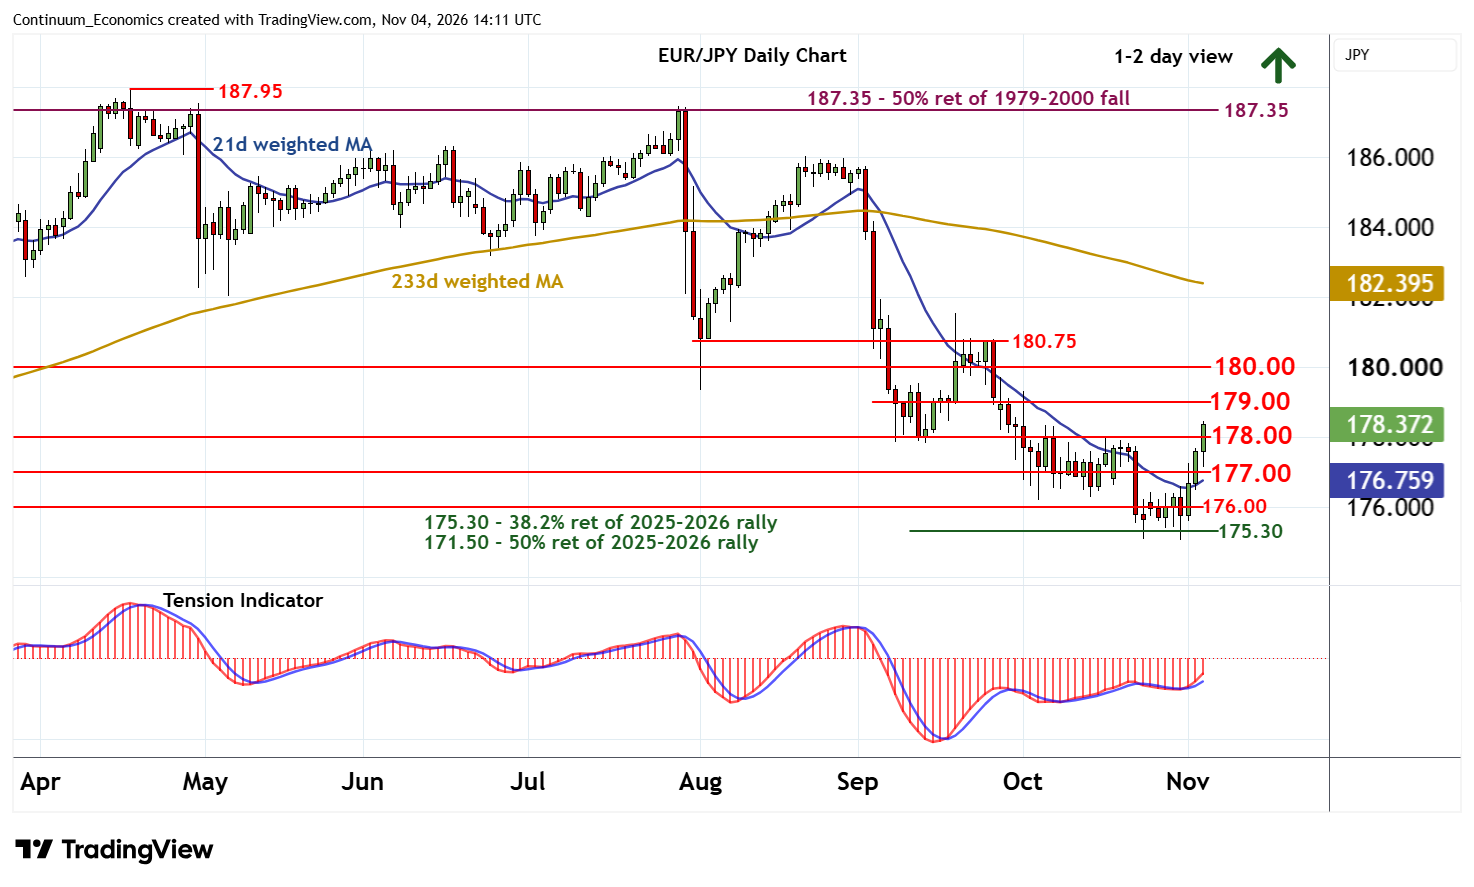
The glass half empty view is to view the shift in power as removing the previous tech carte blanche, be that in local build out or other general areas. More importantly perhaps is simply the mood of the sector, irrespective of the election. The current spike-low bounce hasn’t actually taken out the downtrend in the Nasdaq yet and recent daily action has been much wider. Election dust settled, the market still has a lot more to do to suggest the end of year de-risking and doubts have dissipated. Ultimately tech direction will dominate for the next few months and will be much more relevant to risk-haven FX action than many other factors, Iran aside.
Narrowing the focus to Thursday, the BoE MPC meeting is the main much-awaited event, though a hike itself is now 100% priced in so there is no scope for surprise on the outcome. Inflation Report projections, statement and guidance will be much more relevant. While ‘one-and-dones’ have historically been quite rare for the BoE (and indeed for any major central bank first hike in fact) - and we will take stock out of the meeting - we nonetheless feel that the amount of further tightening priced in is too hawkish. Indeed, the profile has already been deemed as much even by some hawks on the board that have viewed it with ‘scepticism’, even with CPI assumed to move above 4% in the near-term.
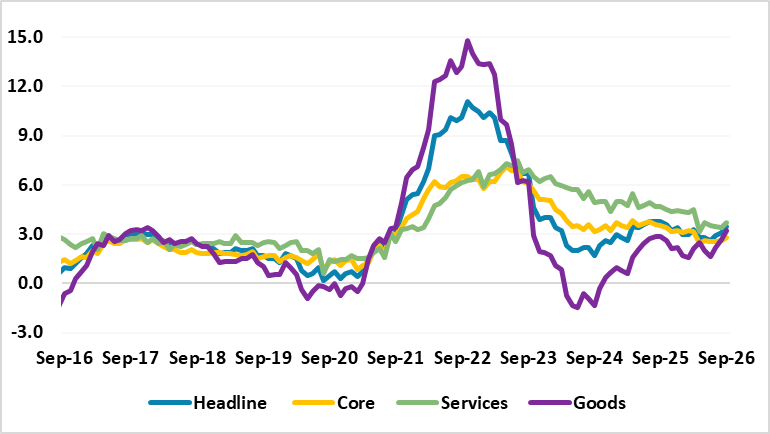
Whether this allows much in the way of ‘sell the fact’ though is to be seen, given some of the wider framing. Technicals allow room for a break above 0.8365 towards 0.8380 on EUR/GBP, though are currently cautious of any covering beyond 0.84 at this point.
Elsewhere, Germany has industrial orders (mkt 4.8% from -10.6%), and Sweden CPIF, on the back of the Riksbank – seen a modest 1.4% from 1.5% and 0.5% ex energy. The Riksbank still signalled it expected policy to be tightening further but only ‘in the coming year’ while also seeing upside and downside risks. We still don’t think the market’s assumed two further hikes through Q1-Q2 will need to be exercised.
In the US, Thursday sees weekly initial claims and the Q3 productivity and costs report, ahead of Friday’s more important payrolls release, where ADP data has suggested some potential upside risks to forecast.