FX Daily Strategy: Asia, Sep 29
CHF still slipping as the unicorn zero-rater
GBP got stretched (over?) short last week, EUR/GBP resistance failure weighs
RBA meeting the big event. Hike priced in so all about the forward guidance
US-Iran jockeying continues, with oil forced to dance along to the tune. Brent front months settle nearer $110 than $100, but still necessarily left straddling the fence. Back months though remain towards the upside and refined products are still an issue. Talks are said to continue this week but it’s not clear who is willing to blink first – Iran has been dangling the carrot of a pre-midterm deal, but the US has been baulking at giving all of Iran’s financial pressure easing concessions upfront (unsurprisingly).
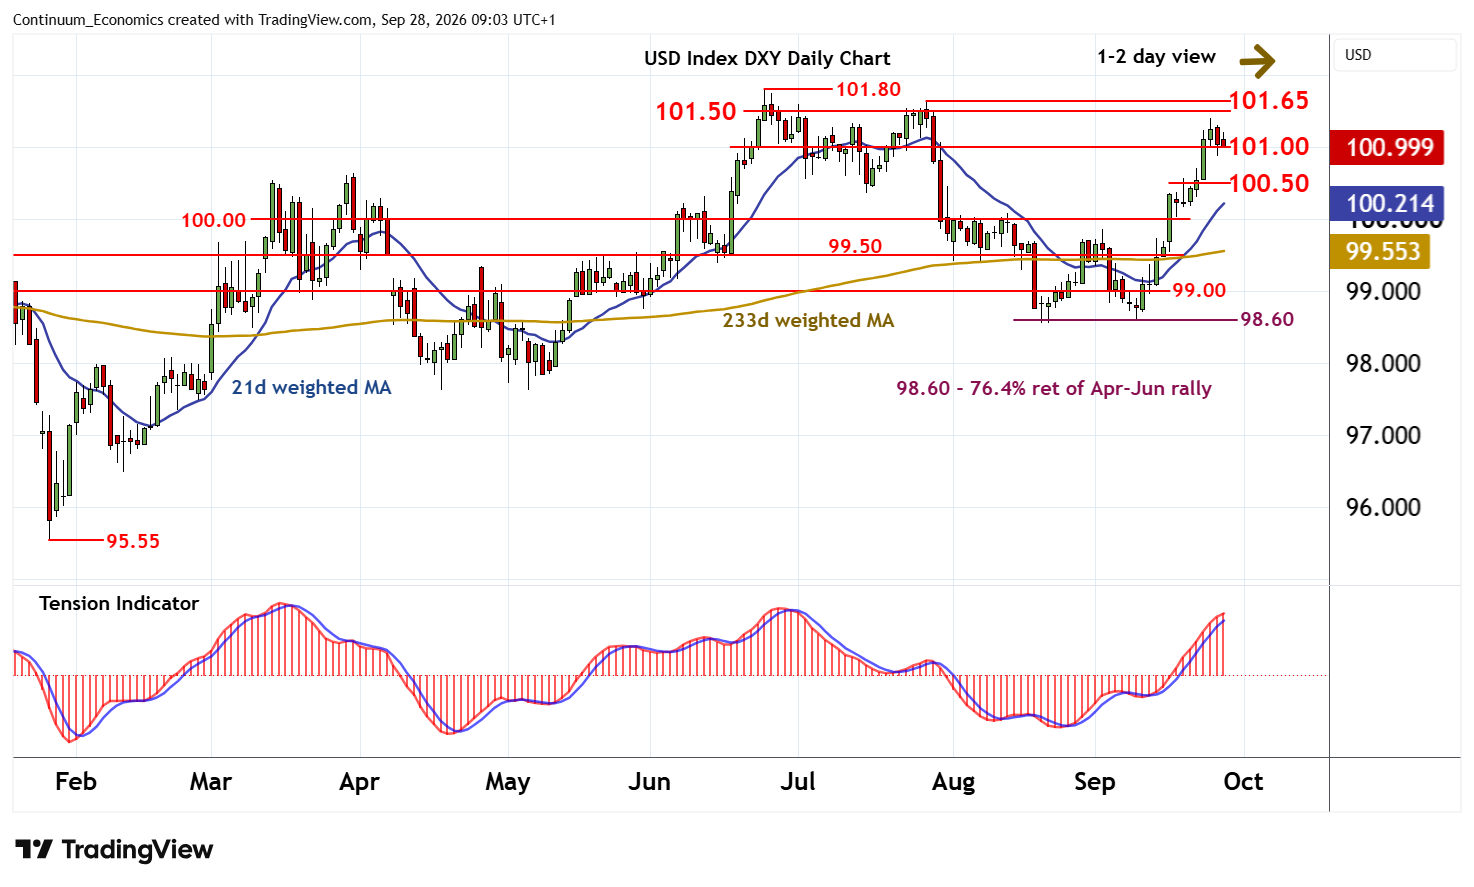
Risk markets not loving the current impasse to start the week but at the same time the Nasdaq is only 1% down from the 3100~ tops retest at present, and even after the recent Oracle woes. If that turns into a clearer double top rather than resistance hold and minor pullback then the wider FX market might start to take note, but at present its just minor chart noise.
Elsewhere, after the recent sharp dollar action, the focal points are a little more idiosyncratic and counter specific.
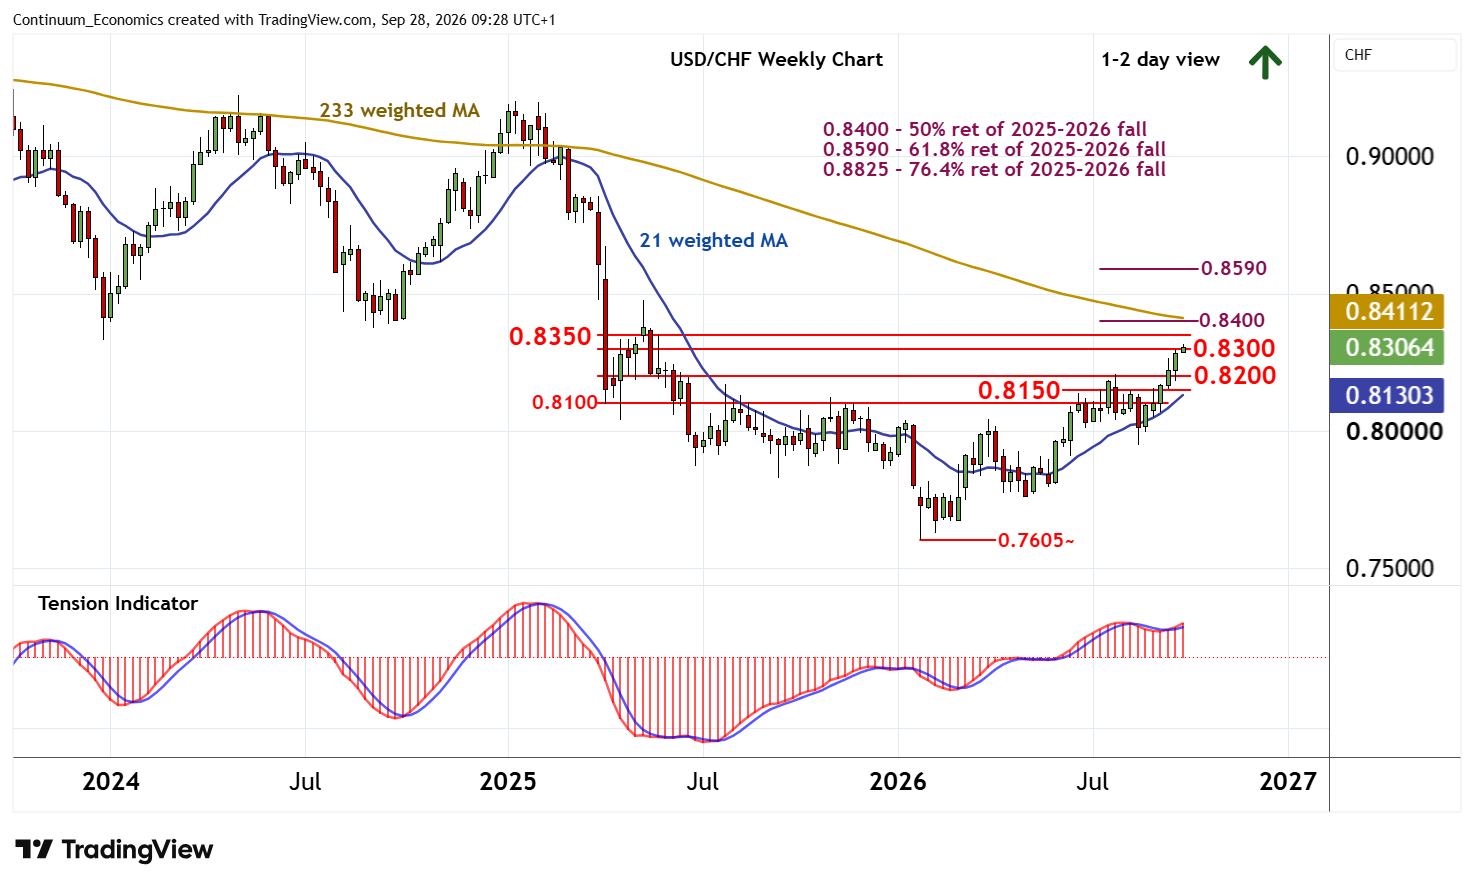
CHF is still getting well and truly ZIRP’d by its policy stance unicorn status, with USD/CHF stretching towards 0.8350 highs with the major retracement around 0.84 above and EUR/CHF back towards its recent highs. While the market is even creeping some tightening into SNB pricing, it still only has a 25bp hike in by Q1 next year. The SNB was itself more adamant that it sees inflation low at zero rates over the full horizon to 2028, granted that this message was partly delivered with one eye on its preference for a softer CHF. That preference vs Japan is itself another standout reason for it being under pressure right now.
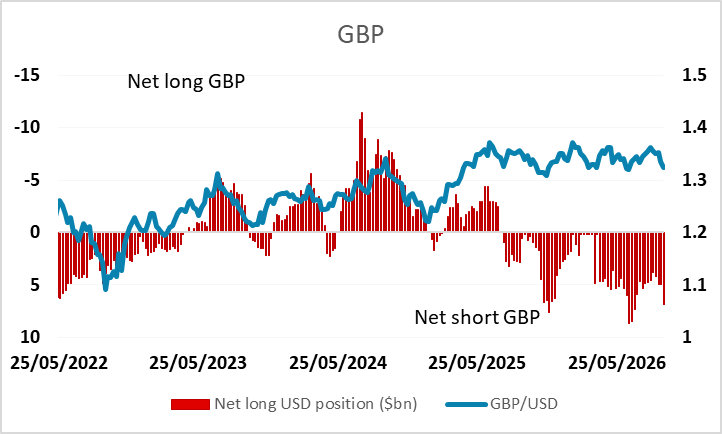
IMM data was notable for highlighting just how far the market have moved on GBP as the most popular "obvious short" last week amid the various central bank moves and with an eye on the upcoming election, while also running fast into the big lows on cable. The failed test of EUR/GBP resistance has done a bit of chart damage near term though and the cross has been a bit of a bull trap of late. That’s left it a bit exposed to consolidative/corrective action and even a bit of a possible GBP squeeze, especially with BoE speakers flagging a likely Nov hike now unless the energy backdrop changes swiftly before then.
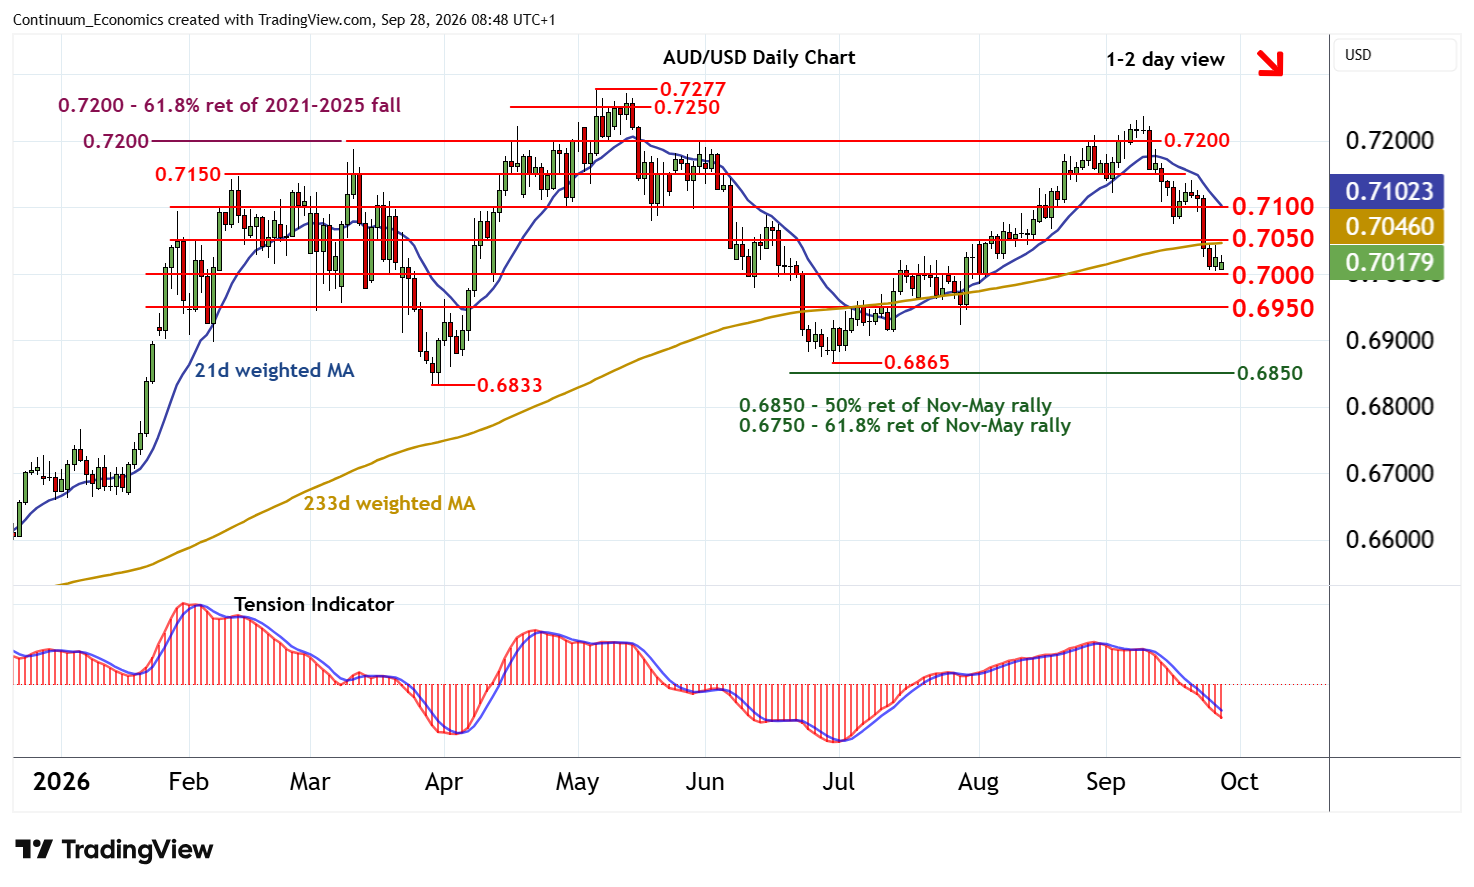
For AUD, the RBA is the major event today. A hike is 100% in the price so its all about the guidance in the statement and presser. There’s another hike fully in the price by Q1 and hedged towards a further (or at least policy premium in that direction). There’s some attention on how far the RBA can go before it starts to pressure the housing market too much, so that balancing act is part of the delicate equation. AUD/NZD has been weighed back from 1.25 over the last week and has 1.2285 May high and the 1.2250/1.2200 congestion area as support. Spec data shows the (contrary indicator) NZD longs have now covered and switched back moderately short.
Tuesday has largely minor data out. Spain starts of the Sep flash inflation data, with HICP seen rising to 4.9% from 4.6%. The UK has the usual BoE money supply and credit data. EZ has the monthly round of sentiment indices, with economic sentiment seen nudging to 99 from 98.4.
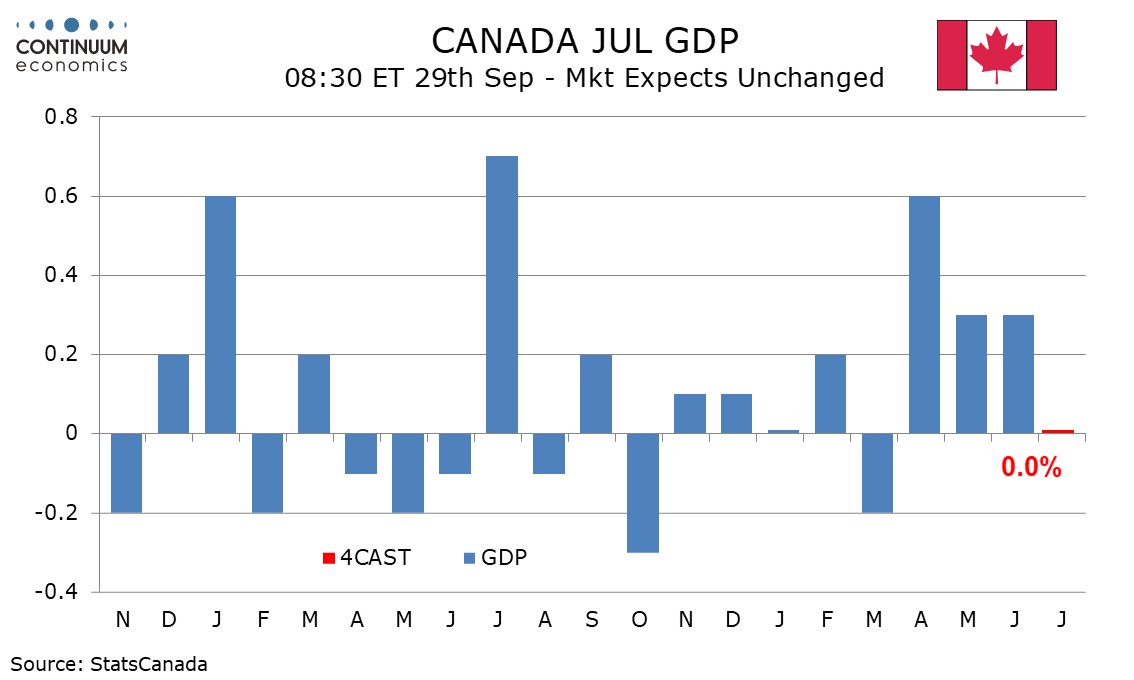
Canada sees monthly GDP data July, where we look for a subdued start to the quarter with a flat monthly outcome.
In the US, in the run in to payrolls, September consumer confidence and August’s JOLTS report on job openings are due today. July house price induces from the FHFA and S& P Case-Shiller are also out.