FX Daily Strategy: Asia Oct 8
· USD watching U.S. Treasuries
· ECB monetary accounts and France
· GBP safe haven
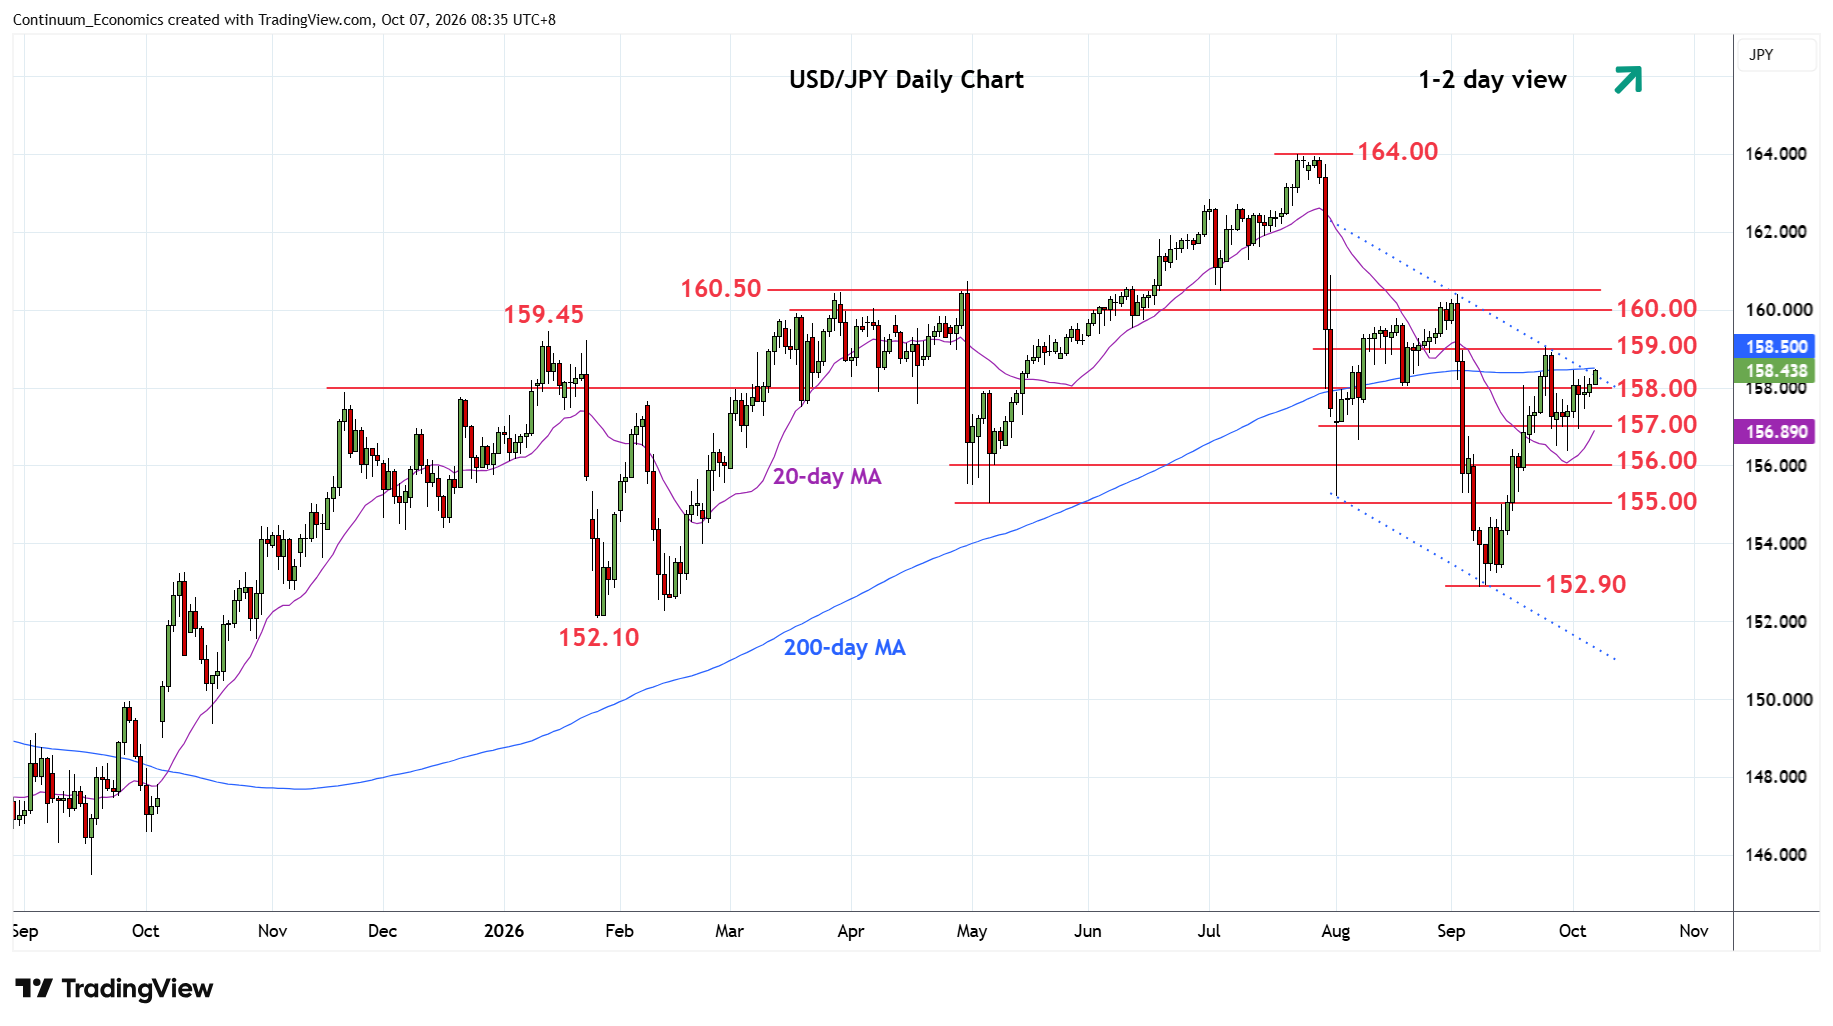
With a lack of major U.S. data this week, the focus is on the U.S. Treasury movement and whether a corrective move lower will be seen. This has not gathered ground, as oil prices have remained volatile and moving higher on Wednesday with Houthi attacks. Additionally, the U.S. government bond market is discounted that the Fed will hike in December and twice in 2027 and it could take significant data to change this mood. A mild drift lower in U.S. Treasury yields could be seen, which could see a consolidation/mild drift down in the USD in the last few days of the week but this will likely be marginally and focus will switch to the September CPI release on October 14.
The ECB monetary accounts from the September meeting on Thursday will attract some attention and they are likely to hint at a December hike. The market will look at whether this is broad agreement or whether a minority wants to pause after 50bps of hikes. Additionally, traders will watch out for any comments on sovereign bond spreads, which some feel could make a December ECB rate hike less likely. If the ECB minutes mention the Transmission Protection Instrument (TPI), then this would dampen December rate hike expectations and hurt the EUR. TPI to help France would in the market mind set suggest that the ECB is less hawkish. Even so, it is worth remembering that the ECB meeting was on September 8 before most of the spread widening. However, Lagarde will have to address TPI questions and whether sovereign spread widening is tightening financial conditions at the October 29 ECB press conference.
Near-term the EUR crosses have stabilised meanwhile, with the focus remaining on the 10yr French-German government bond spreads. Further narrowing could help EUR sentiment further, but the National Rally will likely ask for some of their politically sensitive expenditure cuts, which could led to disagreement when the debate starts in earnest on October 13.
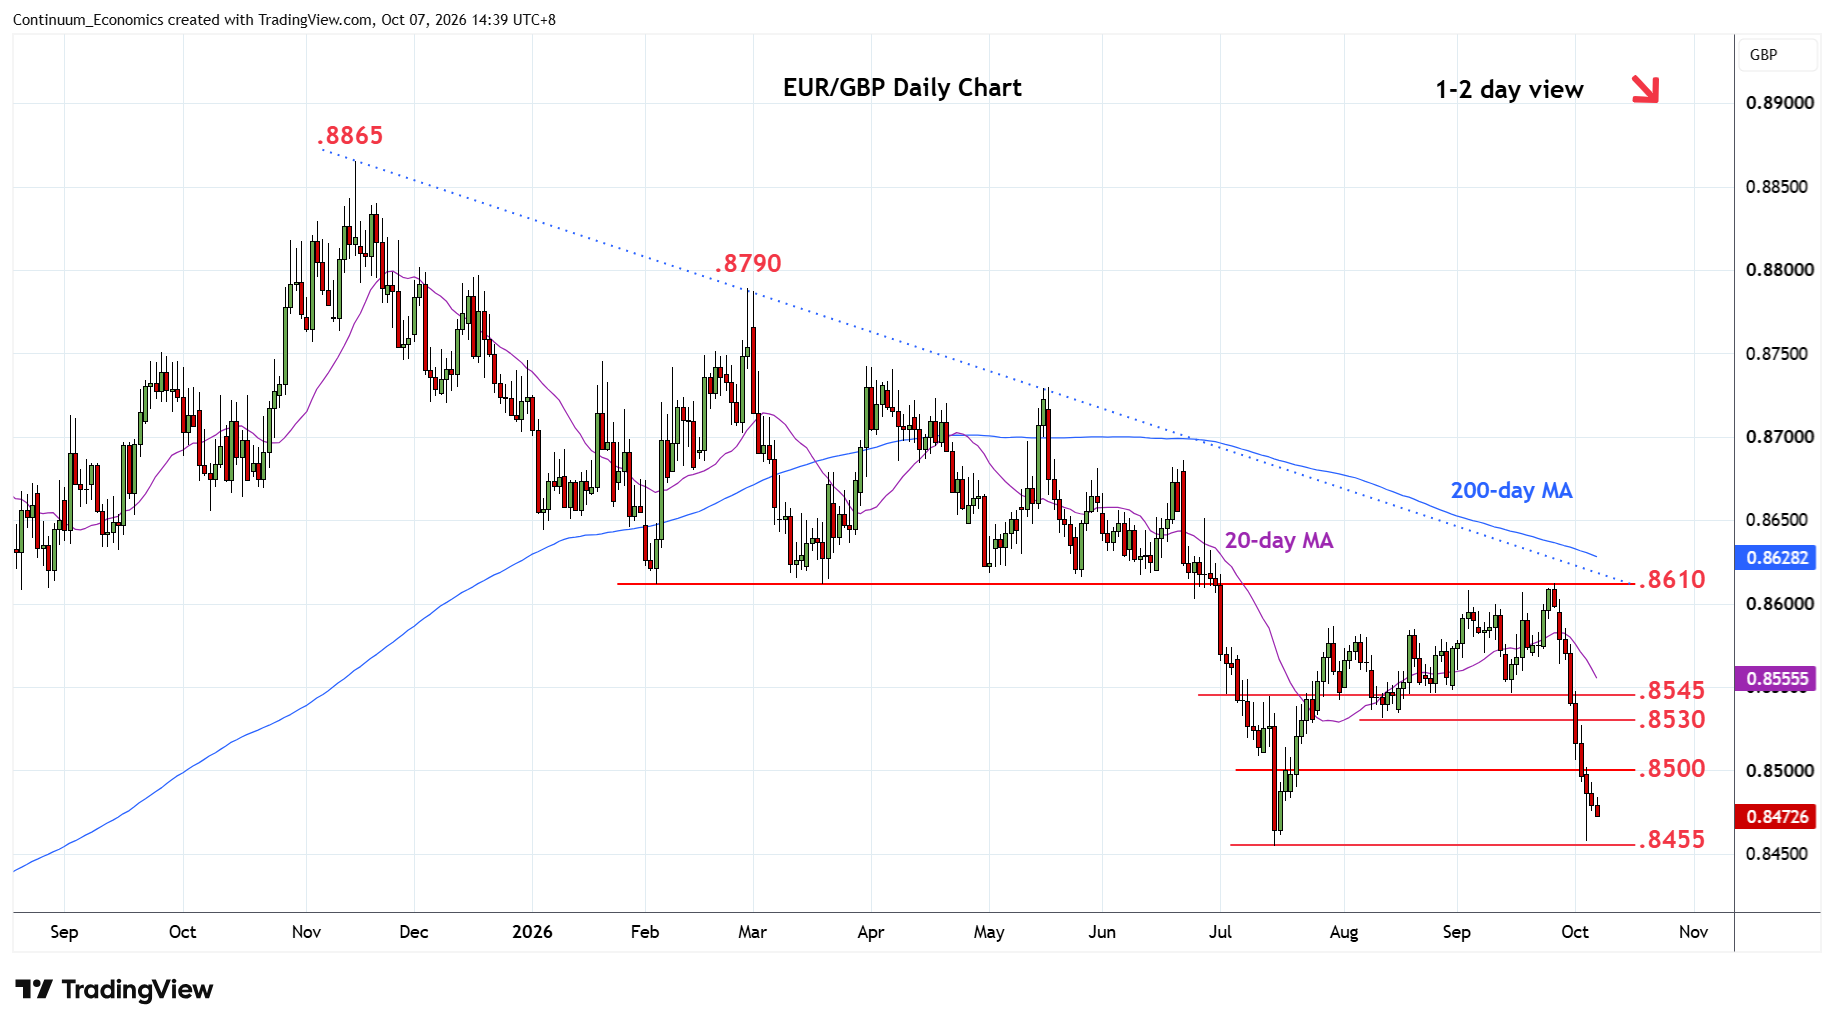
GBP sharp rally against the EUR in the past 2 weeks on French budget woes has stabilised with the hopes around the 2027 French budget. However, GBP performance recently shows echoes of the GBP safe haven flows during the 2010-12 Eurozone sovereign debt crisis, except that this time the UK has a much higher yield than the alternative CHF safe haven. In the government bond market it is also noticeable that the 10yr Gilt-U.S. Treasury spread has narrowed in September. Though UK fiscal tightening is not perfect, the new Burnham/Healey team are committed to fiscal consolidation via the fiscal rules ahead of the October 28 budget. UK fiscal policy is better than the U.S. or France. While EUR/GBP looks consolidative short-term, a break of 0.8450 on bad French news could prompt a move to 0.8300.