FX Daily Strategy: Asia, Oct 27
Dollar starts the week with a lift into event risk, as US tech and US yields see some bounce
BRL very much its own step adjustment, but does further reinforce a wider EM carry turn
Interesting one to monitor and to keep tabs on what sits on the other side
After last week’s pressure, the dollar starting the week on a slightly better footing, with a number of factors in the mix: some steadying in US risk (Nasdaq +0.8%); some levelling and minor lift in yields especially at the short-end, with one eye on an FOMC meeting that is not 100% certain (given after all, very valid reasons to hike) and into auction supply; and a splash of short-term technicals.
On the latter front, oversold daily stochastics on DXY are ticking higher, suggesting room for continuation towards congestion resistance at 102.00 and if that is taken out there is stretch room to .50-85.
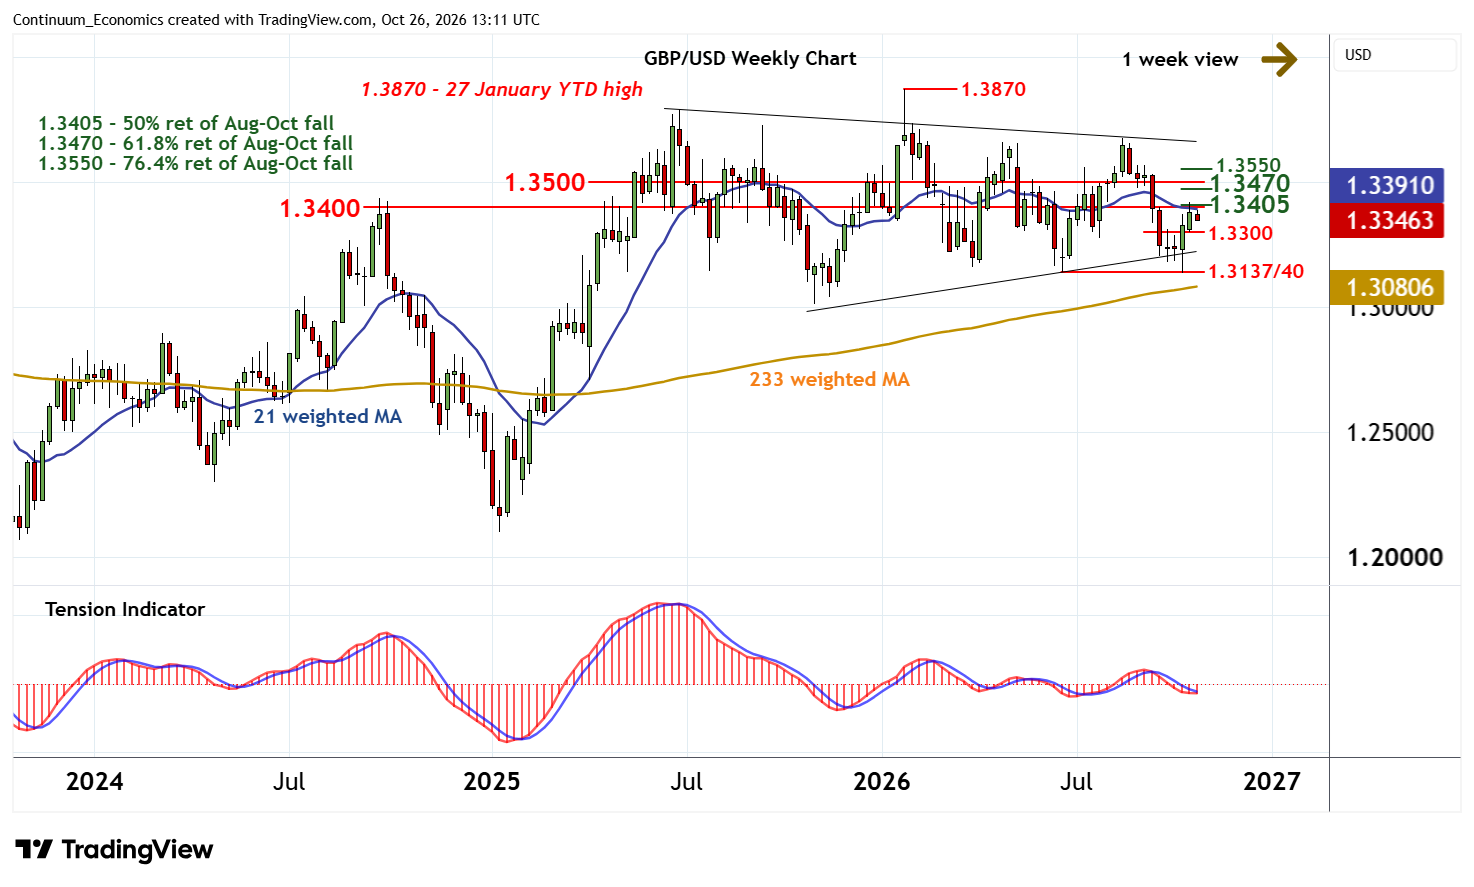
And as noted in the weekly, various pairs have event risk ahead this week, and sterling is among those with some incentive to briefly take some chips off the table. Cable is finding 1.3400 and the 1.3405 Fib to be strong resistance on the recent gains.
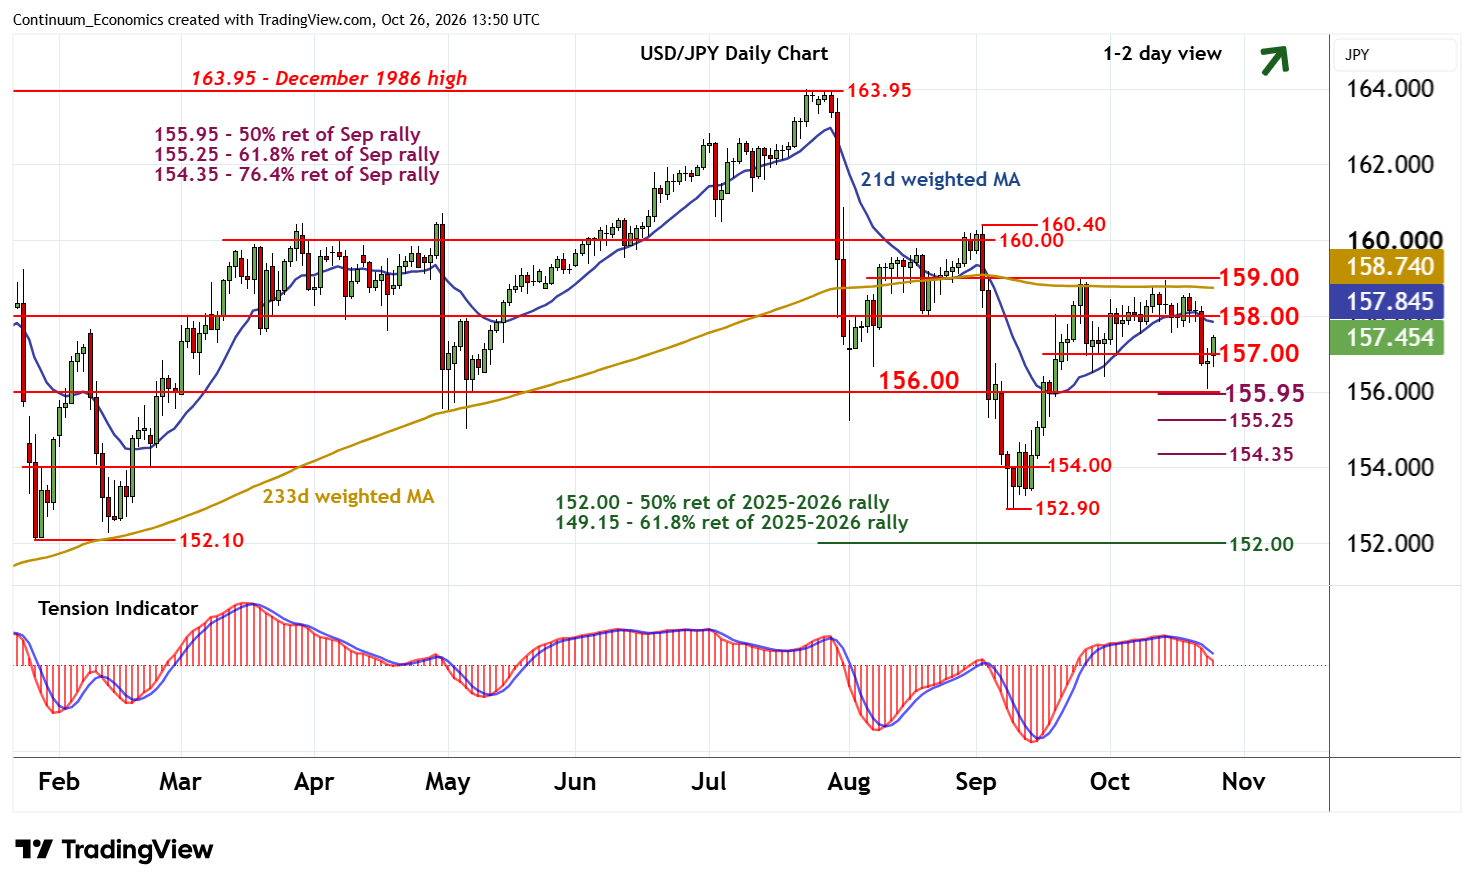
Spike test of 156 and back off 157, along with the cross-asset start to the week, has also been giving USD/JPY the inclination for range bounce near-term as well, though supply should thicken back up again towards strong resistance at 158 and capping remains a feature.
One interesting factor in the mix, if not a prime mover on the session, was the post-election action in BRL, seeing a significant surprise result step-jump move to unwind the YTD BRL gains in one gap, hitting big retracement levels in the process. While there weren’t any big ripple effects on the day, either on other carries, or on carry funders (on the contrary), there was perhaps a touch of reinforcement of the dollar bid.
Looking more generally at popular carries, BRL joins MXN that has been under pressure in recent week, and the fading of other popular EM counters, while the likes of USD/TRY also remain one way on the currency side. A crude basket of a selection of such names underscores the recent potential major trend break and scope for possible further retracement ahead.
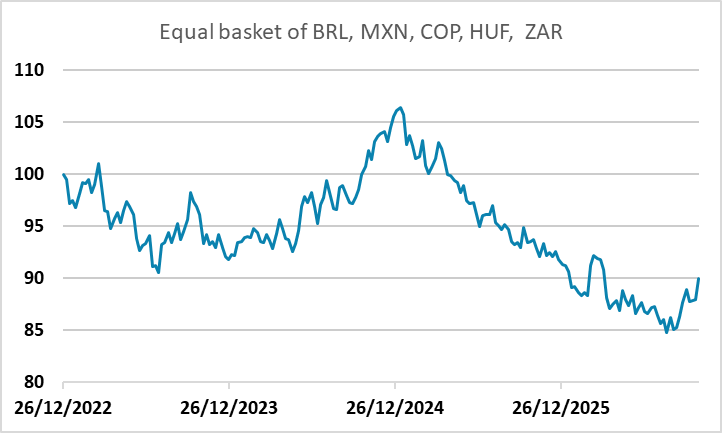
If that transpires, the question becomes whether a more established deeper trimming of longs and profit-taking retracement moves start to have some spillover. Counter-parties in that event are in interesting question – that is, adding thematically to the recent revivals of the JPY and CHF, with JPY carry funding having been in established retreat since the summer and CHF joining since France troubles? Or, as with today, support for the dollar on the pure dollar pair unwinds? Another big picture topic to ponder as we enter the winter months.
Turning to Tuesday, some data to watch, but nothing that will distract too much from the central bank build up, nor monitoring price action out of France. Eurozone has money supply data, less of a current ECB focus than at times, seen sticking at 3.4% from 3.5%.
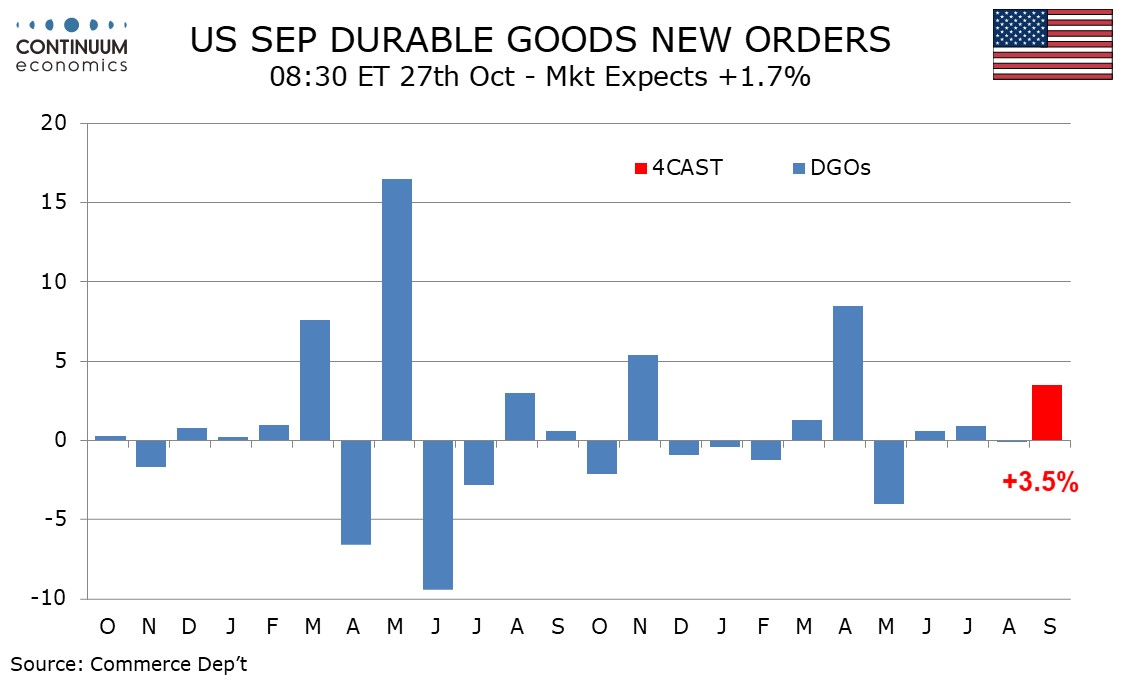
The US has durable goods. We expect a 3.5% increase in September after a below trend 0.1% decline in August. While aircraft are likely to lead the increase we expect a healthy 1.0% increase ex transport, also picking up from a below trend 0.2% rise in August. Non-defense capital orders ex aircraft trend is seen remaining strong.